

Welcome back, Fluenteers! 👋🏻
Not too long ago, someone in our community brought Norbit ASA to my attention. At first glance, I thought nothing special of the business. Yet, when I delved deeper into the company, its management, products, services, and niche market, I was blown away.
Today we’re peeling back every layer of Norbit ASA, and by the end of this investment case, you know:
Everything about the company, the market, management, and its future.
Is now the right time to add Norbit ASA to the portfolio?
Happy compounding!
What Will Be Discussed:
Corporate Analysis
1.1 Business Overview
1.2 Revenue BreakdownExecutive Leadership
2.1 CEO Experience
2.2 Management Compensation
2.3 CEO Value CreationInsider Ownership
Competitive and Sustainable Advantages (Economic Moat)
Industry Analysis
5.1 Industry Growth Prospects
5.2 Competitive BenchmarkingRisk Assessment
Financial Stability
7.1 Asset Evaluation
7.2 Liability AssessmentCapital Structure
8.1 Expense Analysis
8.2 Capital Efficiency ReviewProfitability Assessment
9.1 Profitability, Sustainability, and Margins
9.2 Cash Flow AnalysisGrowth Projections
Owner Earnings & Expect Annual Return
Value Proposition
11.1 Dividend Analysis
11.2 Share Repurchase Programs
11.3 Debt Reduction StrategiesQuality Rating & Checklist
Valuation Assessment
1. Corporate Analysis
1.1 Business Overview
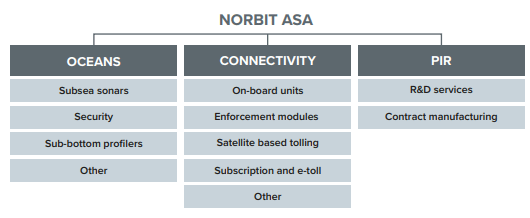
Norbit ASA was founded in 1995. The company was established to provide tailored technology solutions to a selection of niche markets. Norbit ASA’s mission ‘‘Explore More’’ reflects its purpose of solving challenges through advanced technology in three key segments:
Oceans: To deliver advanced sonar and subsea technology for maritime markets, including aquaculture and defense, addressing needs like surface and subsea imaging and mapping.)
Connectivity: To enable digitization through data collection, sensor analysis, and connectivity solutions, such as intelligent traffic systems and smart data for vehicle and asset monitoring.
Product Innovation Realization (PIR): To offer R&D services and contract manufacturing for demanding industrial customers, fostering innovation and tailored product development.
Norbit ASA did not immediately adopt this segmented structure. Through strategic acquisitions by management, Norbit ASA, as we know it now, was established in 2009 with three key segments that comprise the company. Norbit ASA isn’t scared to do value-accretive acquisitions; it’s part of their growth trajectory. We’ll go into greater detail about their value-accretive acquisitions in Chapter 8.2 Capital Efficiency Review, so hang in there.
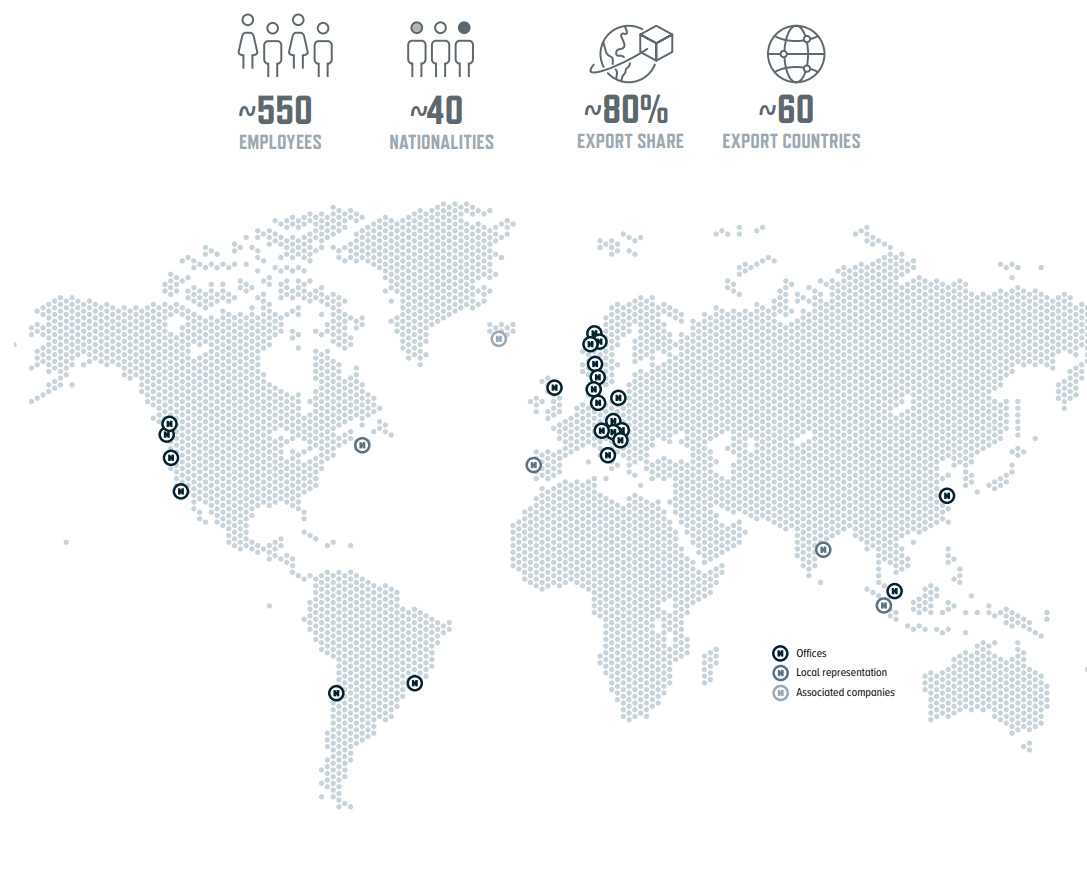
From a small company in Norway, we're inching closer to becoming a global multi-national. Norbit ASA operates in 20 countries and has ~600 employees, ~40 nationalities, 80% export share, and exports to ~60 countries.
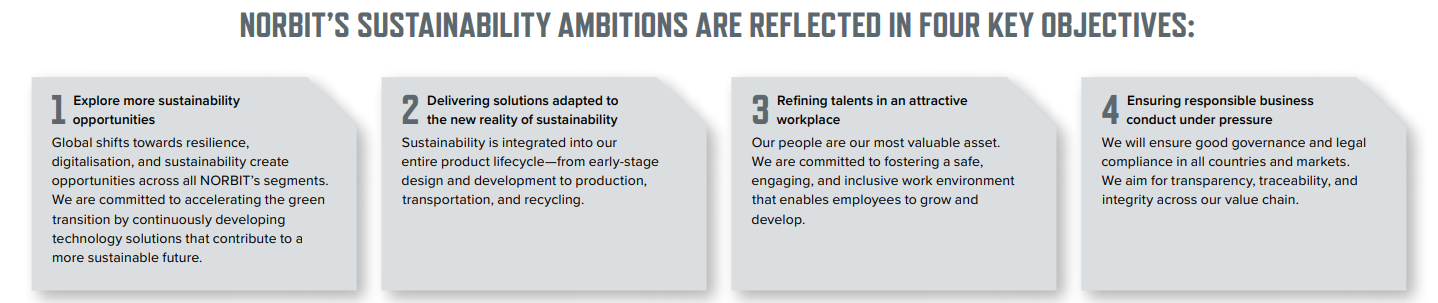
Despite the explosive growth Norbit ASA is experiencing, its sustainability ambitions and key objectives have never changed.
From the very beginning, Norbit ASA has been highly focused and has pursued a strategy of relentless focus on market-driven innovation in carefully selected applications. Norbit ASA invests in the development of new products and solutions when it understands the needs of its customers in its niche. Norbit ASA’s tremendous focus on research and development ensures that they stay at the forefront of technological innovation.
The majority of Norbit ASA’s success has been the diversification of their business model, thereby reducing dependence on any one market of products while also taking advantage of opportunities for growth and expansion. Tailoring the growth strategy of each business segment has been their intentional choice.
1.2 Norbit ASA Revenue Breakdown
As mentioned earlier, Norbit ASA has three revenue segments:
Oceans (Account for 43.19% of total revenue based on 7-year median)
Connectivity (Account for 27.45% of total revenue based on 7-year median)
Product Innovation Realization (PIR) (Account for 36.94% of total revenue based on 7-year median)
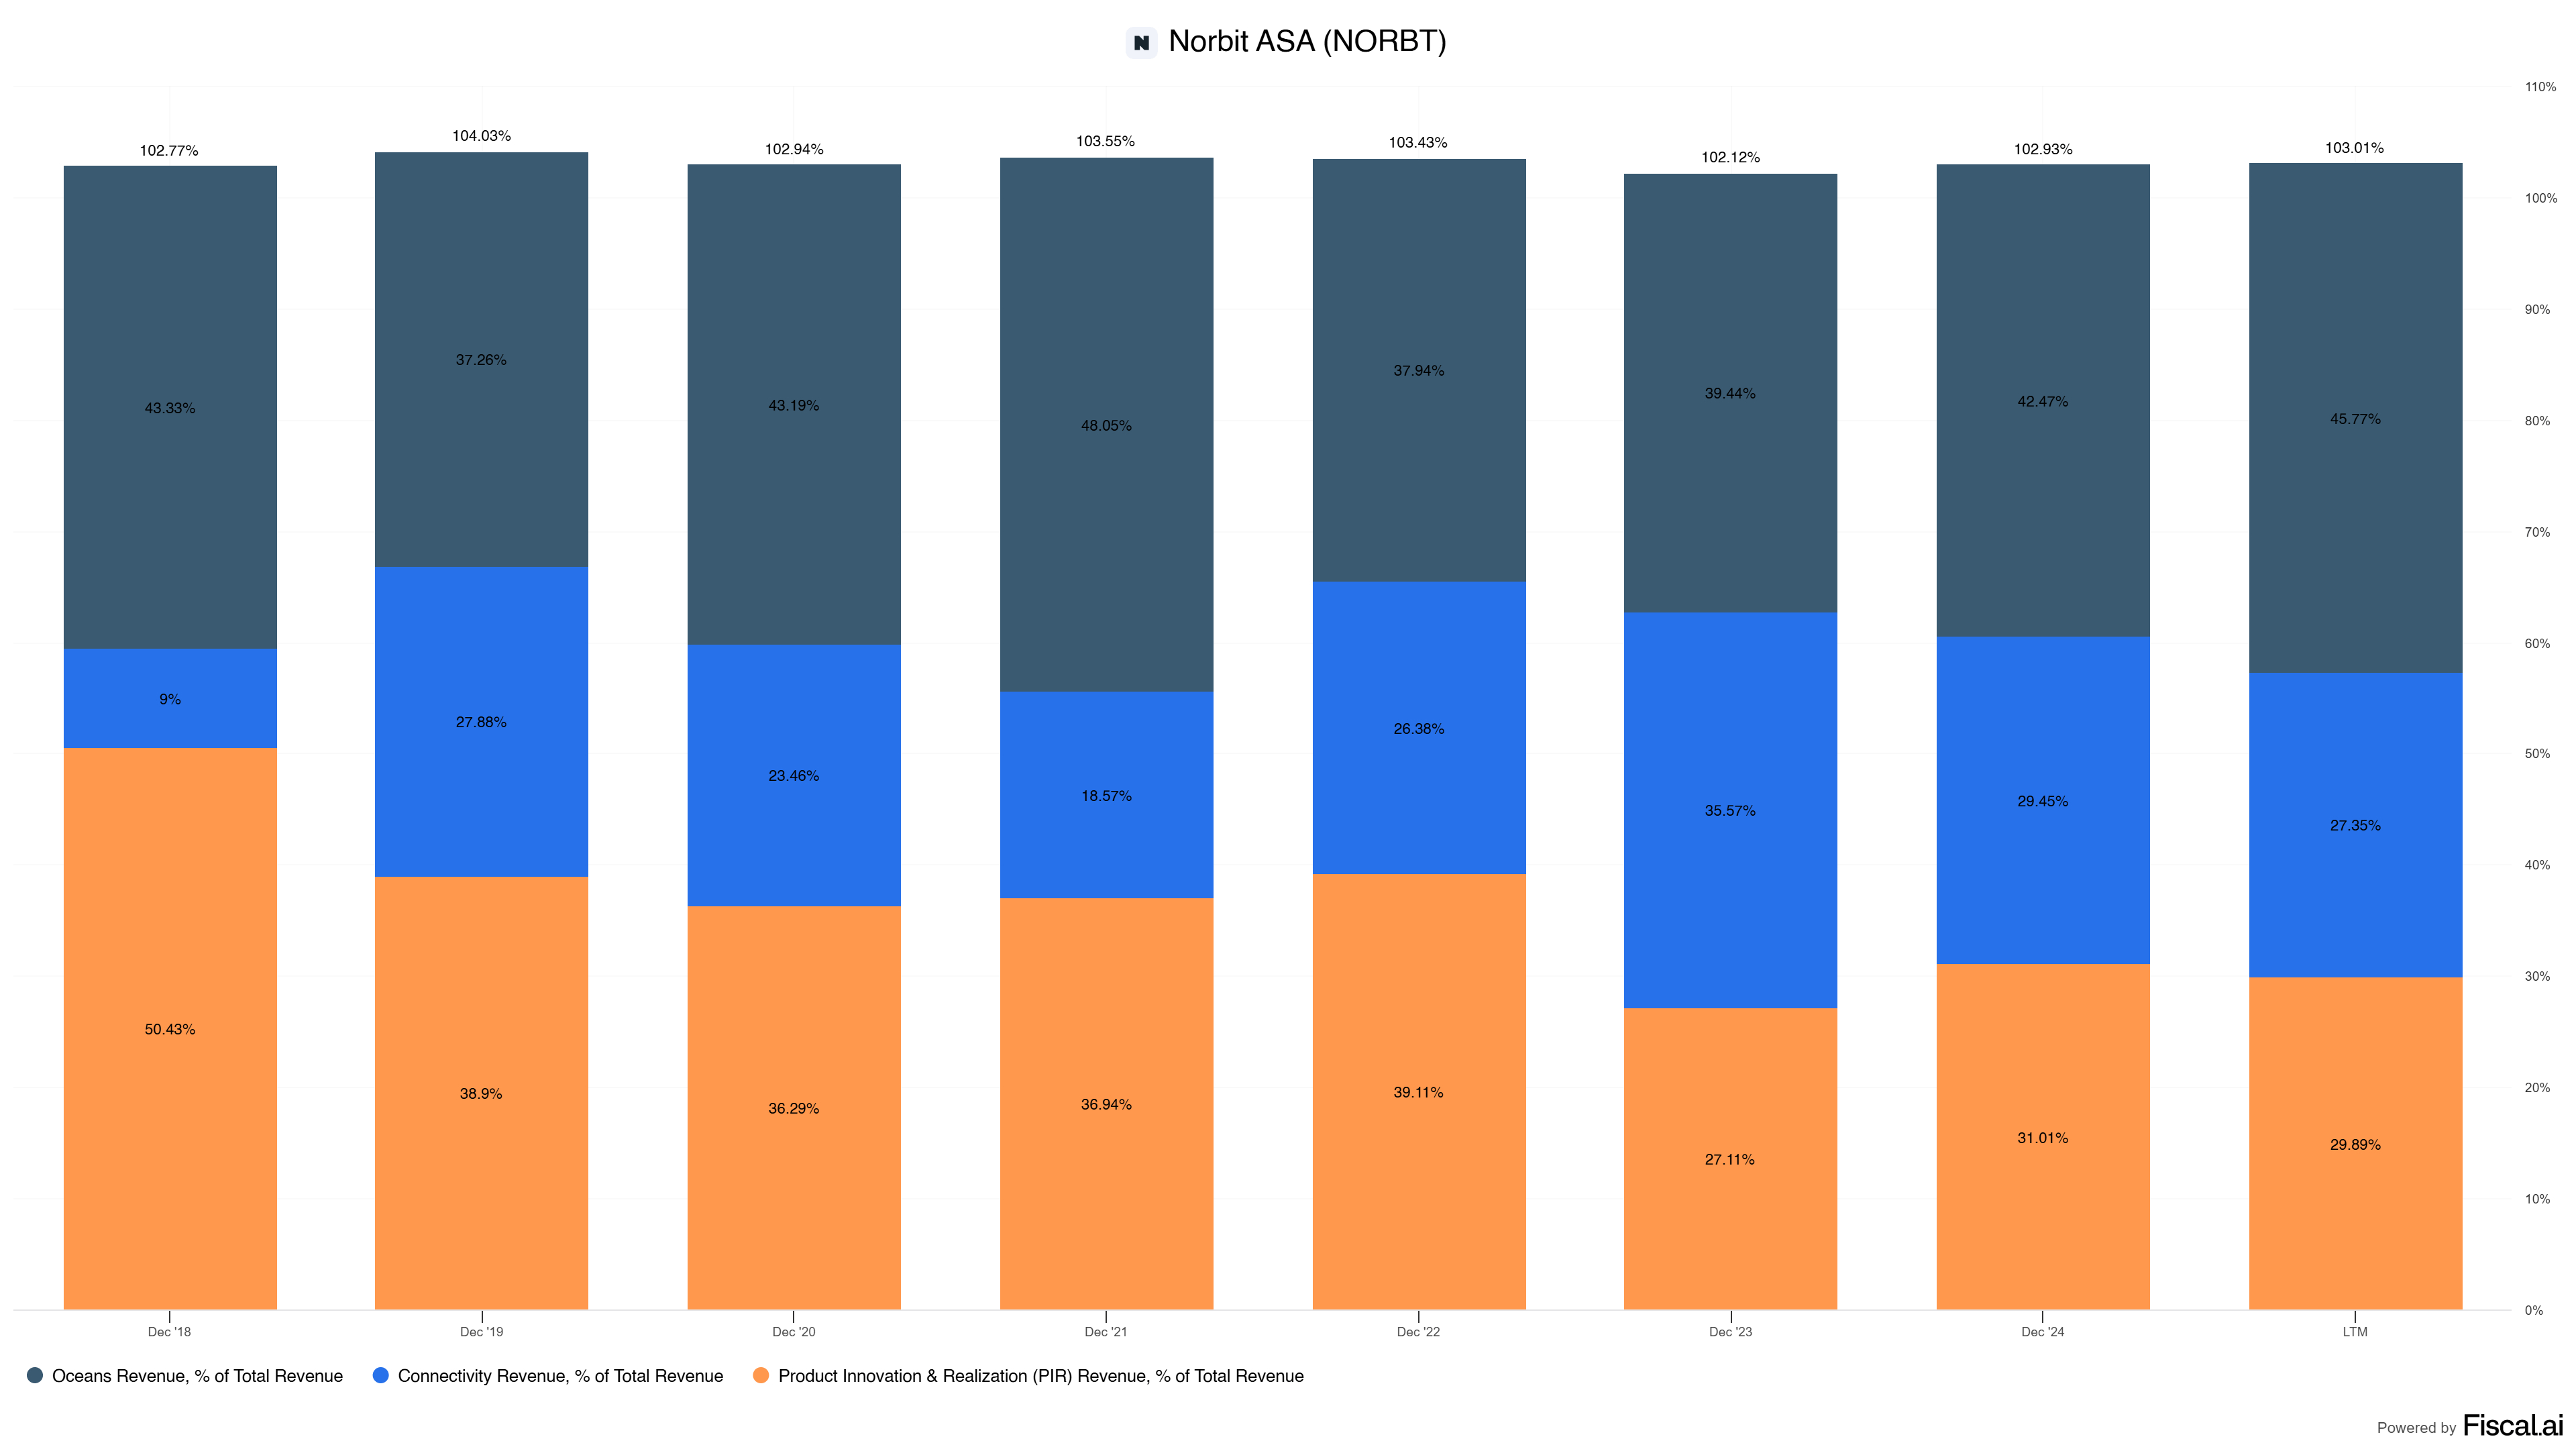
There’s clearly a positive shift in the dependence on segments. If we look at 2018, their PIR (Product Innovation Realization) segment accounted for 50.43% of their total revenue, while Ocean accounted for 43.33% and Connectivity only made up 9% of their total revenues.
As of 2024, PIR accounts for 29.89% of total revenue, Oceans accounts for 45.77% of total revenue, and Connectivity accounts for 27.35% of total revenue.
There’s been a significant shift in management. They had realised their dependence on two segments and turned this around. Although reliance on a particular segment isn’t necessarily awful, having less dependence does make you more resilient in case one segment starts to face (temporary) headwinds.
Norbit ASA was able to break free from this dependency by increasing its focus on high-growth niches within connectivity, through strategic acquisitions and partnerships, and by investing significantly in its R&D (Research and Development) and innovation.
Their shift from dependence, luckily, didn’t impact their overall growth in other segments, as shown in their yearly revenue chart.
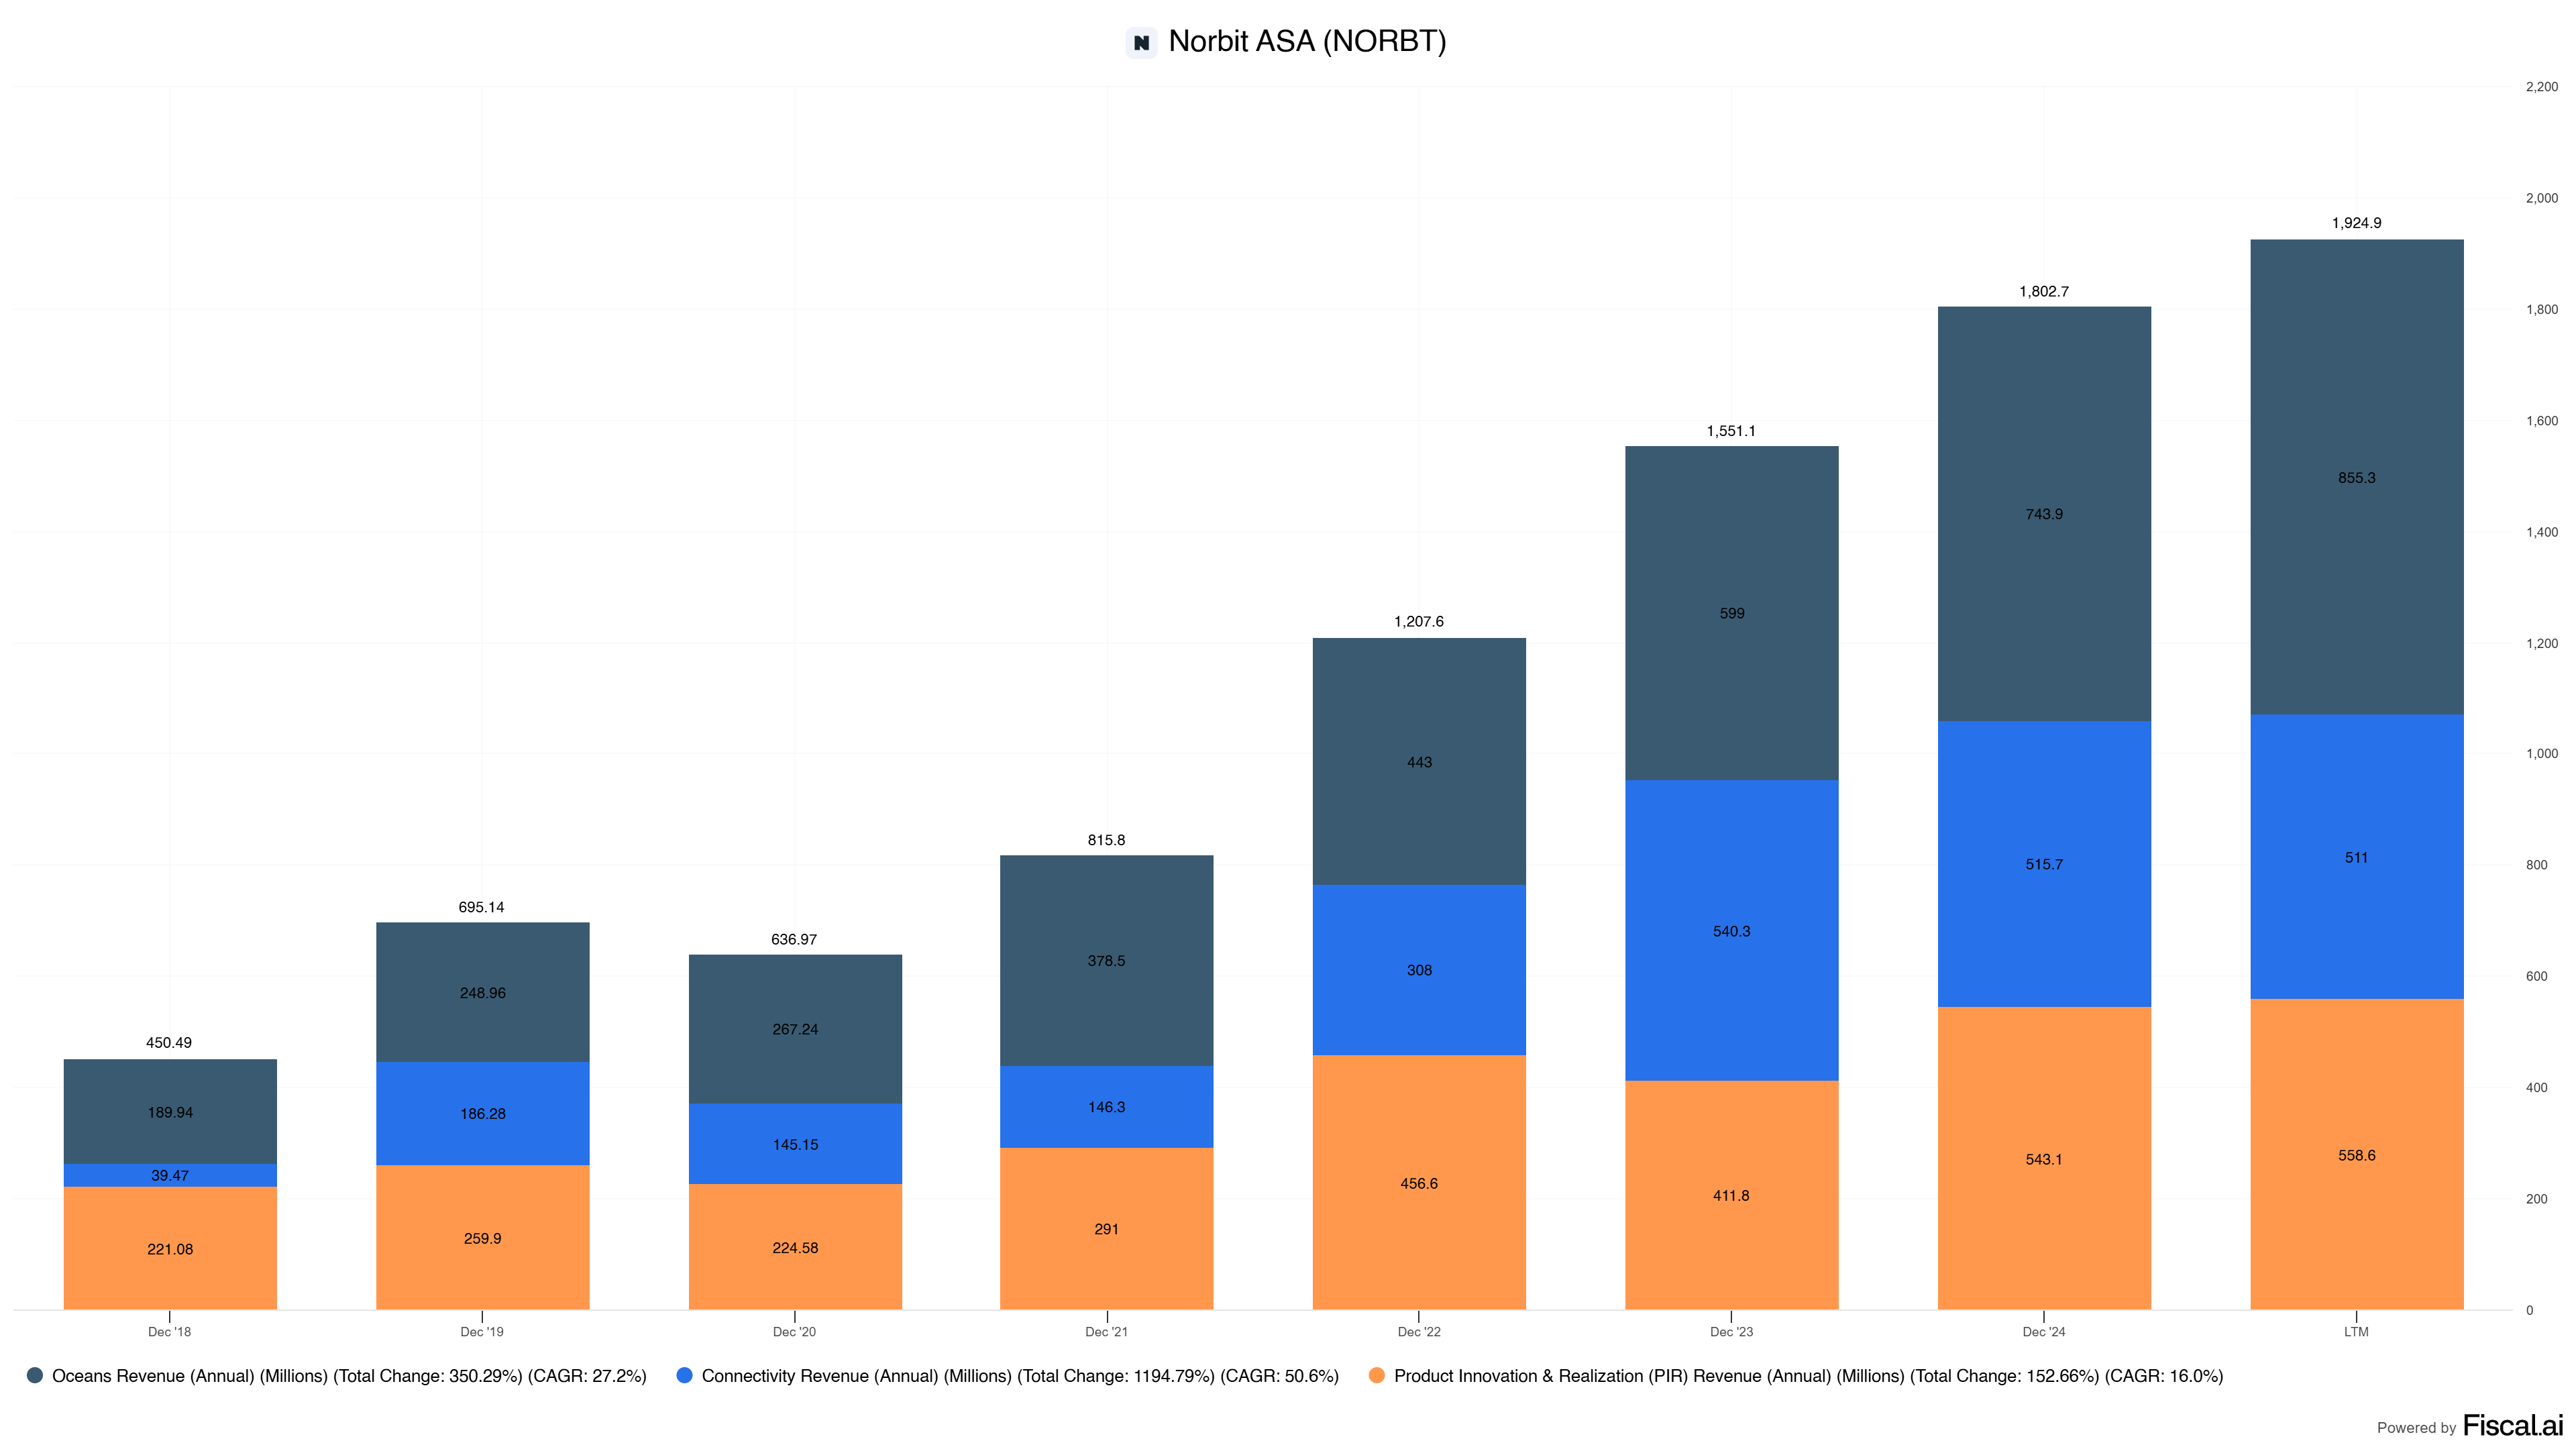
As shown in the chart, all three segments still grow at excellent rates. Connectivity is now taking the cake based on growth with a CAGR of 50.62%, Oceans comes second with a CAGR of 27.12%, and last but not least, PIR comes with a CAGR of 15.98%. The growth rate of Connectivity is higher due to their strategic move to remove dependency on their other segments, but as mentioned previously, growth in their different segments wasn’t impacted.
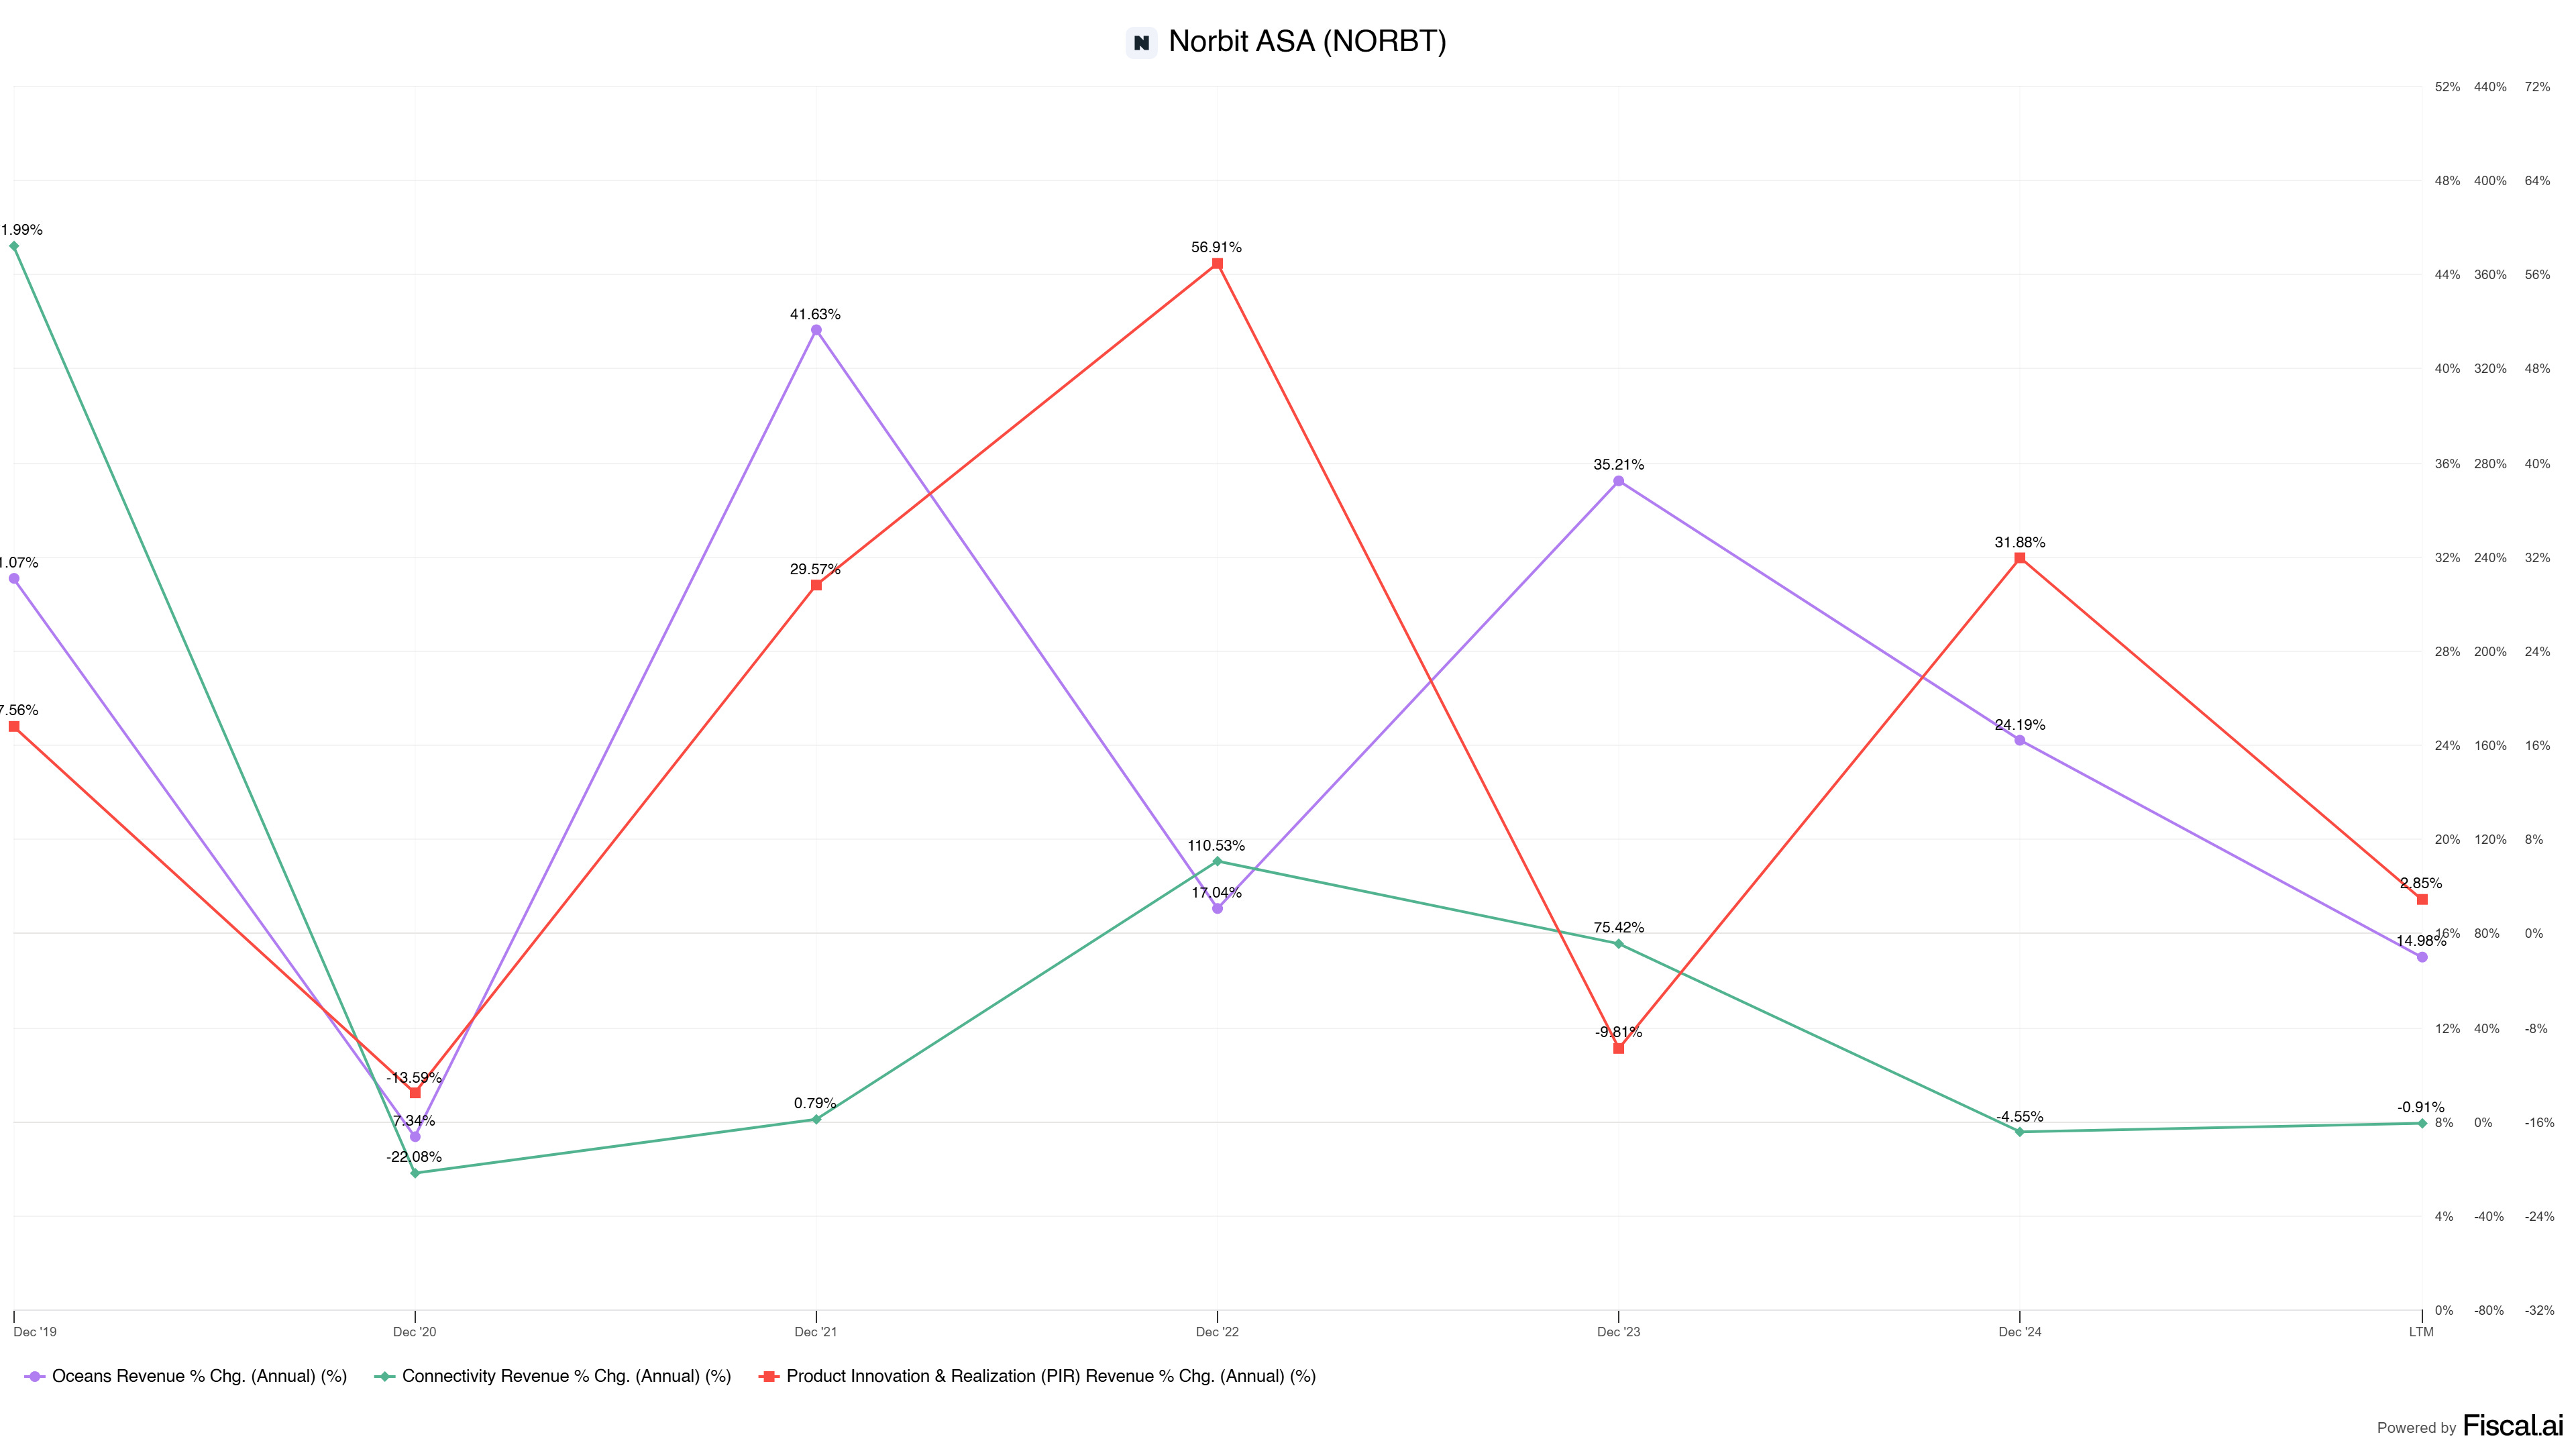
How can one make that assumption? Well, to put it simply. Although Connectivity outgrew the other segments, the segments still showed healthy YoY (year-over-year) growth, as shown in the chart below.
2. Norbit ASA Executive Leadership
2.1 CEO Experience
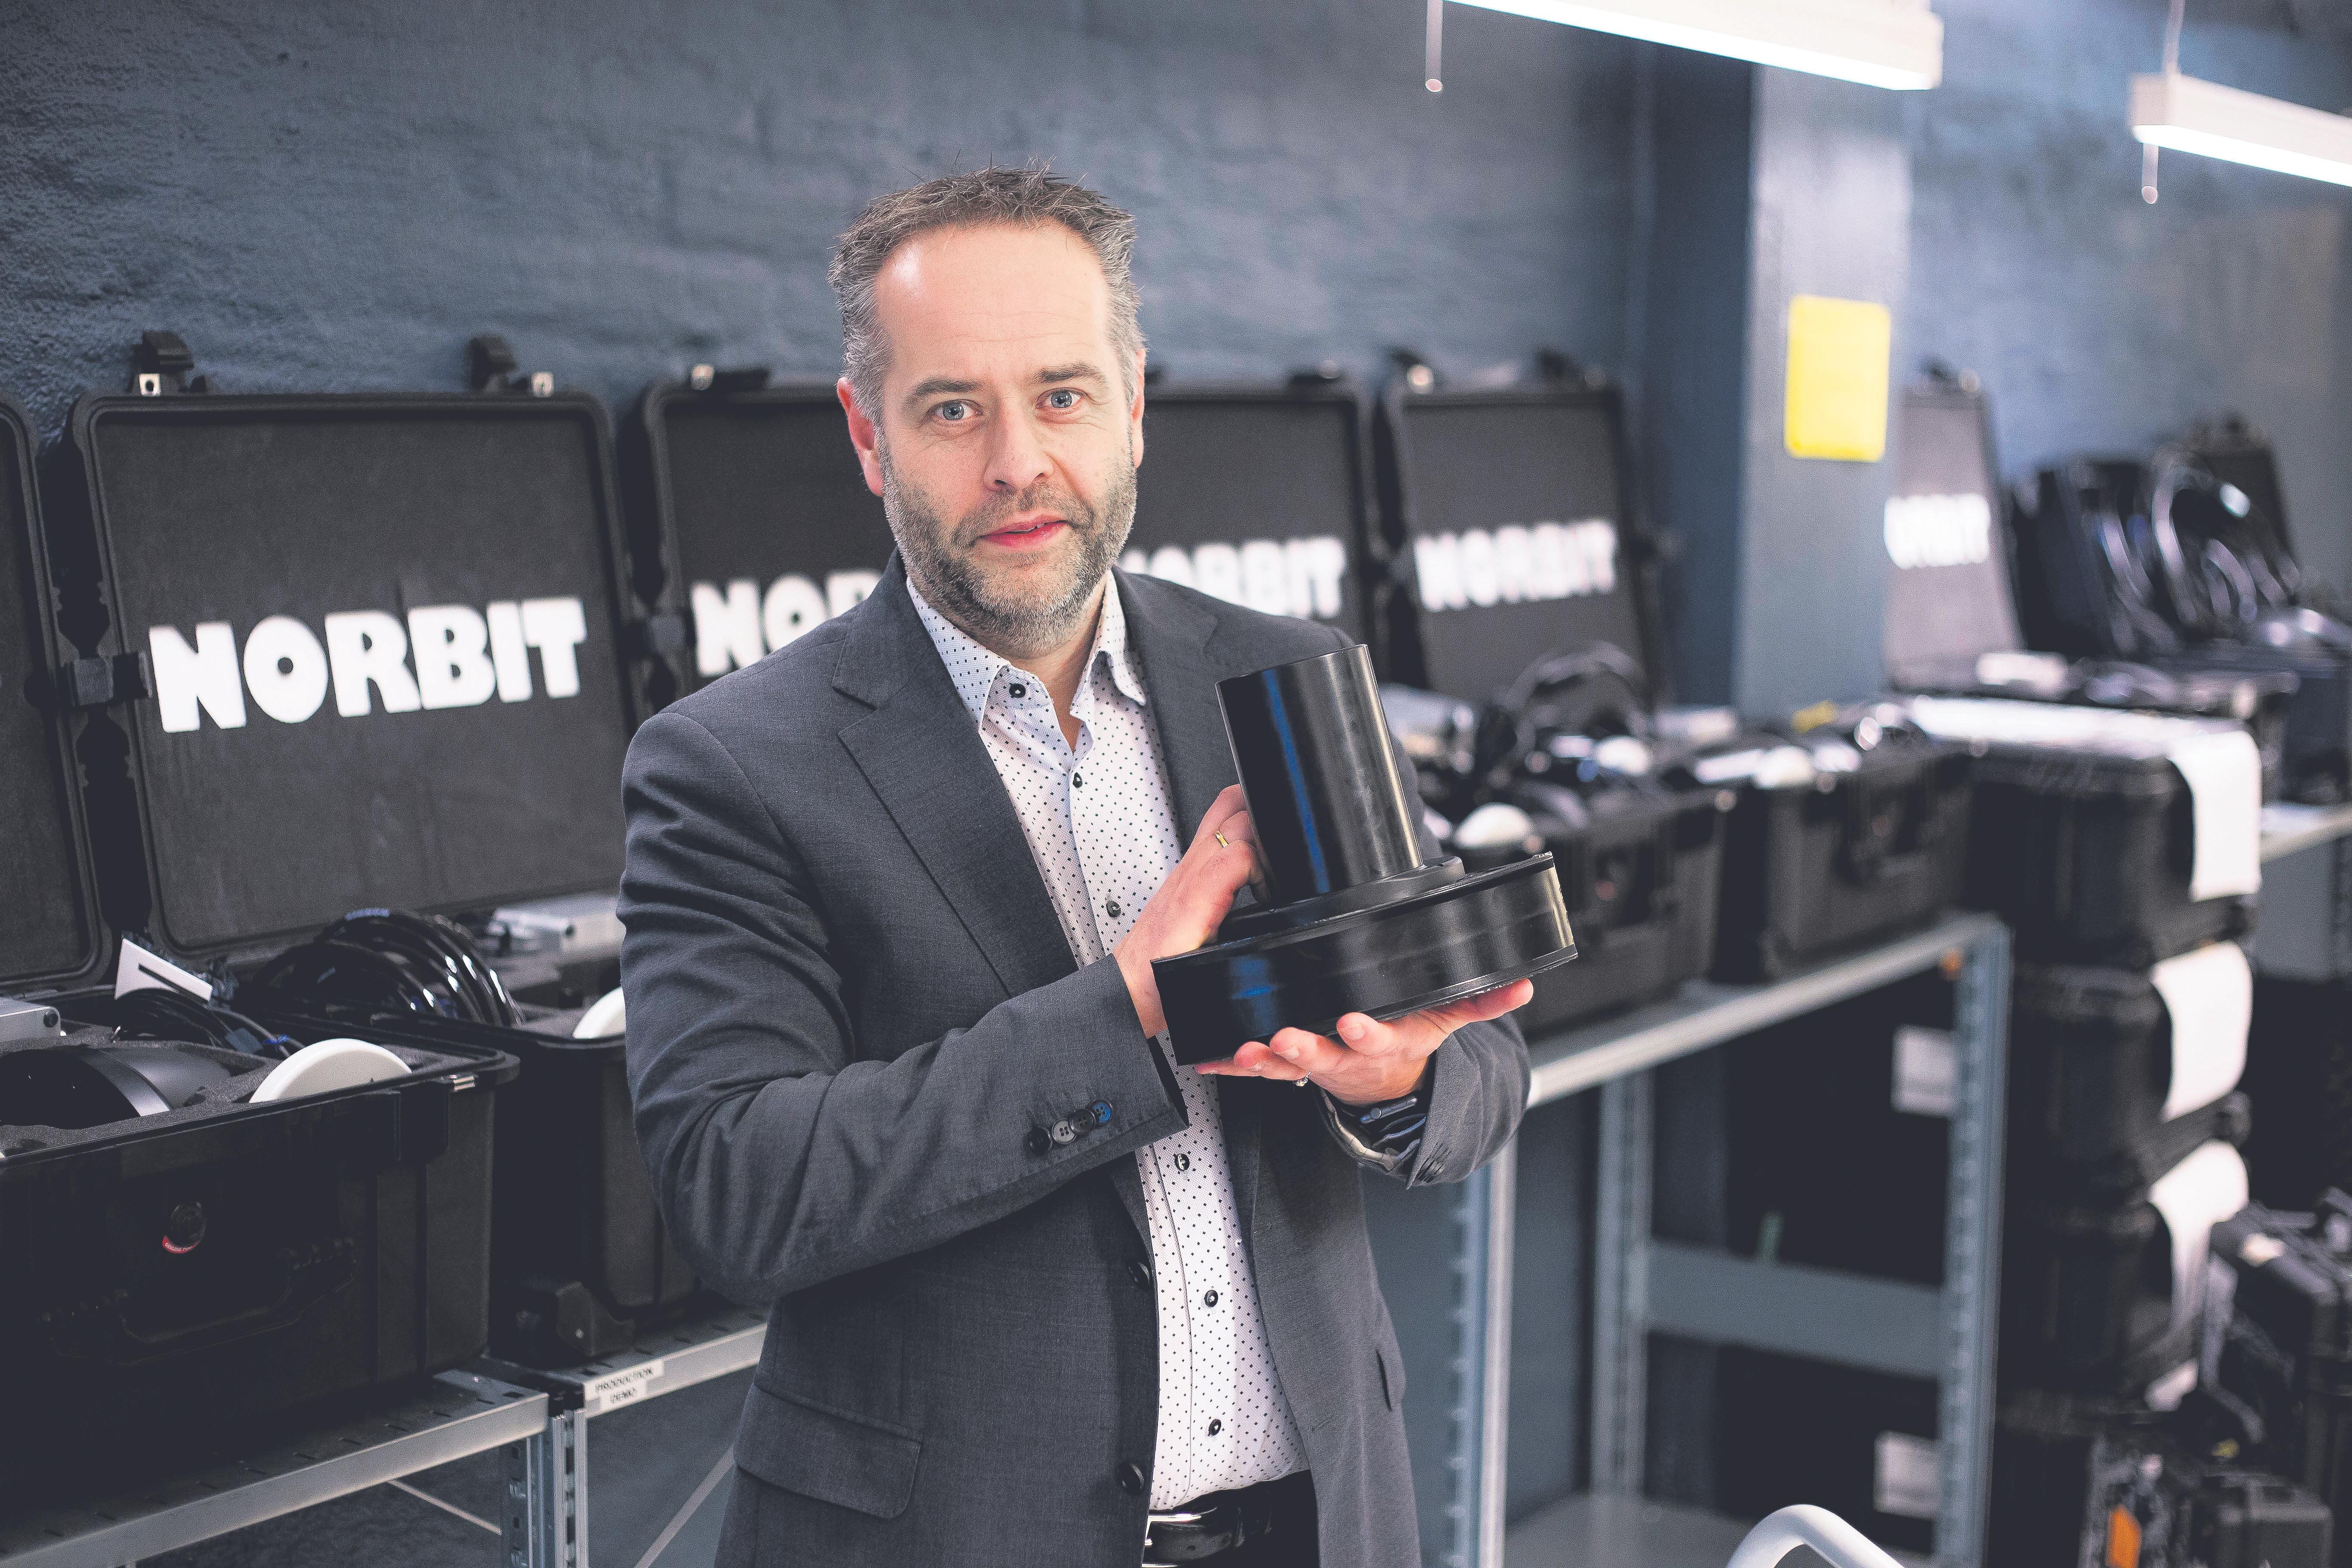
Norbit ASA’s CEO is Per Jørgen Weisethaunet. Per Jørgen Weisethaunet has held the CEO position since 2001. Per Jørgen Weisethaunet has been the co-owner of Norbit since 2008.
Per Jørgen Weisethaunet has a Master’s in RF & Microwave Electronics from the Norwegian University of Science and Technology, a Bachelor’s in Electronics from the Trondheim University of Engineering, studied Business Economics at Trondheim Economic University, and studied Supply Chain Management at BI Norwegian Business School.
Per Jørgen Weisethaunet carried Norbit ASA from 7 employees to ~600 as per the latest quarter, with a determined focus on technological innovation in Oceans, Connectivity, and their PIR segment. Per Jørgen Weisethaunet spearheaded the strategic shift to reduce segment dependency, boosting Connectivity’s revenue share through, as mentioned before, R&D investments, acquisitions, and targeting high-growth niches like IoT and traffic systems.
Per Jørgen Weisethaunet oversaw the 2019 IPO of Norbit ASA on the Oslo Stock Exchange and recorded performance, achieving 2024 financial targets early 2023.
Per Jørgen Weisethaunet emphasized the ‘‘Made in Norway’’ production, regional technological self-sufficiency, and sustainability with the “ Notbit ASA ‘‘Explore More’’ mission.
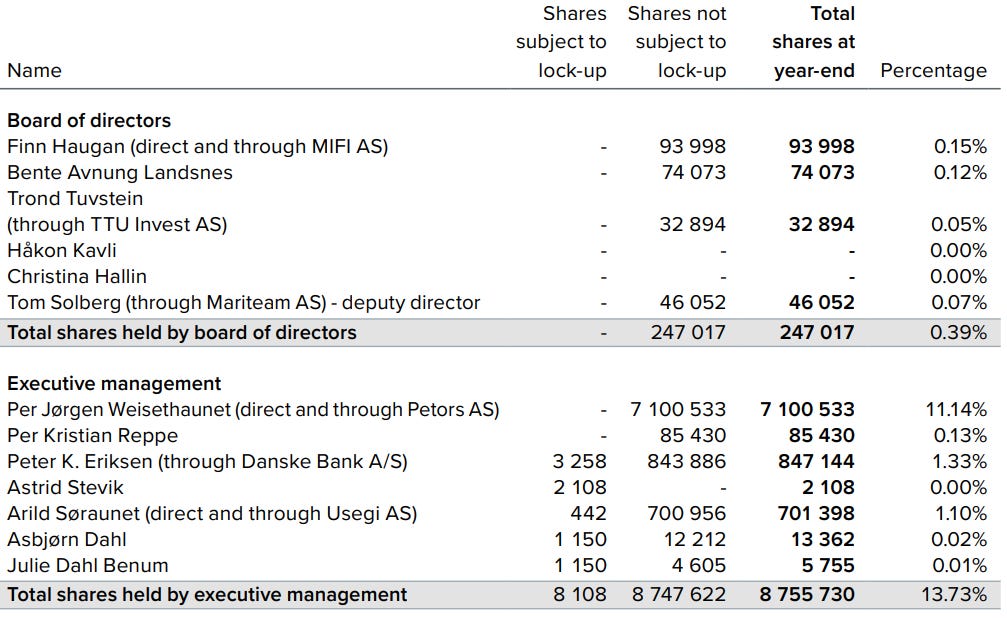
Per Jørgen Weisethaunet is heavily invested in Norbit ASA as well.
As per the latest filings, Per Jørgen Weisethaunet owns 7.1 million shares worth ~1.2B (SEK). Per Jørgen Weisethaunet is not just a CEO, but he’s carrying Norvit ASA to new heights via value-accretive acquisitions, focusing on their core industry, niche down to what matters, and driving for optimal efficiency within their products, services, and workforce.
2.2 Employee Satisfaction Ratings
I love discussing these ‘hidden gems’ with all of you. There’s one downside, however. And that’s the fact that most employees who started with this business stuck around. This, in turn, limits the number of trustworthy employee reviews available. Norbit ASA is a relatively young company with almost no turnover.
Having no or limited turnover is beneficial, but it also means that the reviews are limited as well.
The reviews I did find, ~10 reviews, are all talking highly about the company. There’s a mission that everyone is following, and a healthy work-life balance is achieved. Management seems to be doing an excellent job of keeping all employees, at all levels, extremely satisfied within their respective positions.
I wish I could provide more reviews like I was able to with the big tech companies we’ve discussed. But since Norbit ASA is a relatively young company, reviews are limited.
Nevertheless, the couple of reviews out there are incredibly positive.
2.3 CEO Value Creation
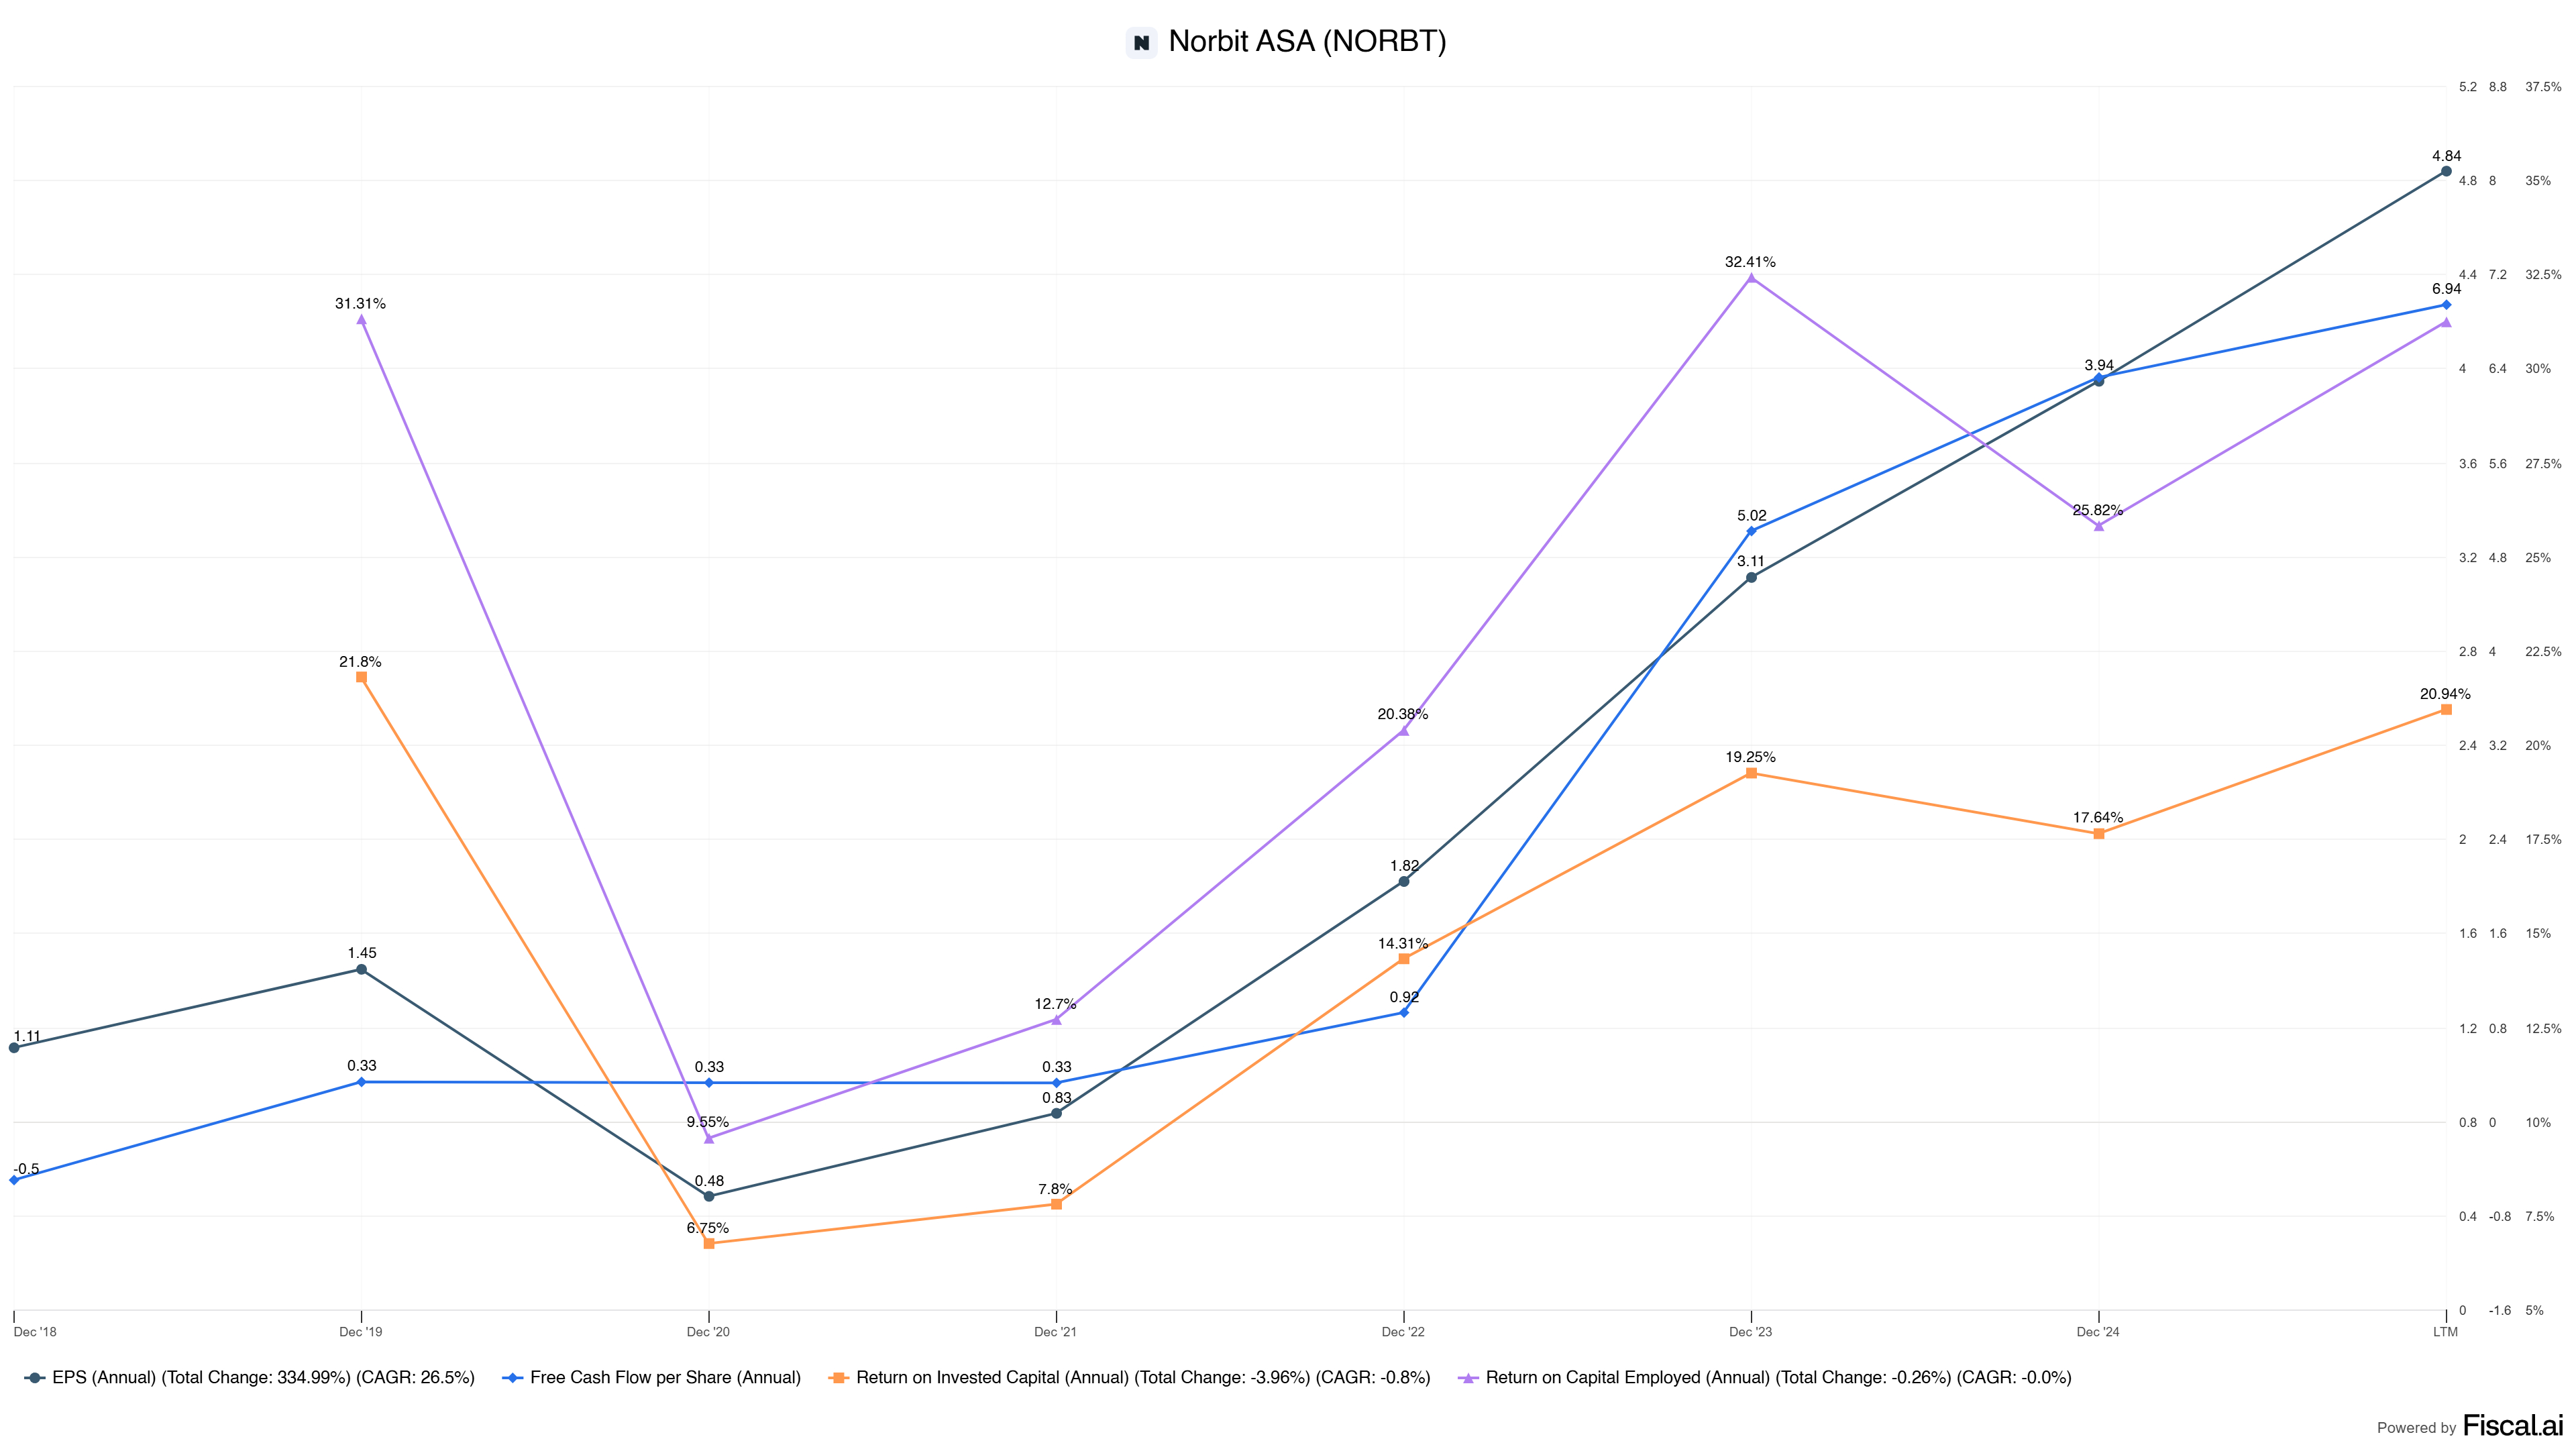
Management is creating value for Norbit ASA.
ROIC (Return on Invested Capital) and ROCE (Return on Capital Employed) have gradually been increasing to excellent levels. The industry average for Norbit ASA is ~15% for both. Norbit ASA has had a higher ROIC and ROCE compared to the industry average since the 2021/2022 fiscal year.
Moreover, Norbit ASA has gradually been increasing its EPS (Earnings per Share) and Free Cash Flow per share. To put it simply, Norbit ASA is generating more earnings and providing more free cash flow on a per-share basis each year. For shareholders, this means you’re getting more cash and earnings for each share you own in the company.
3. Insider Ownership
This is where Norbit ASA truly shines!
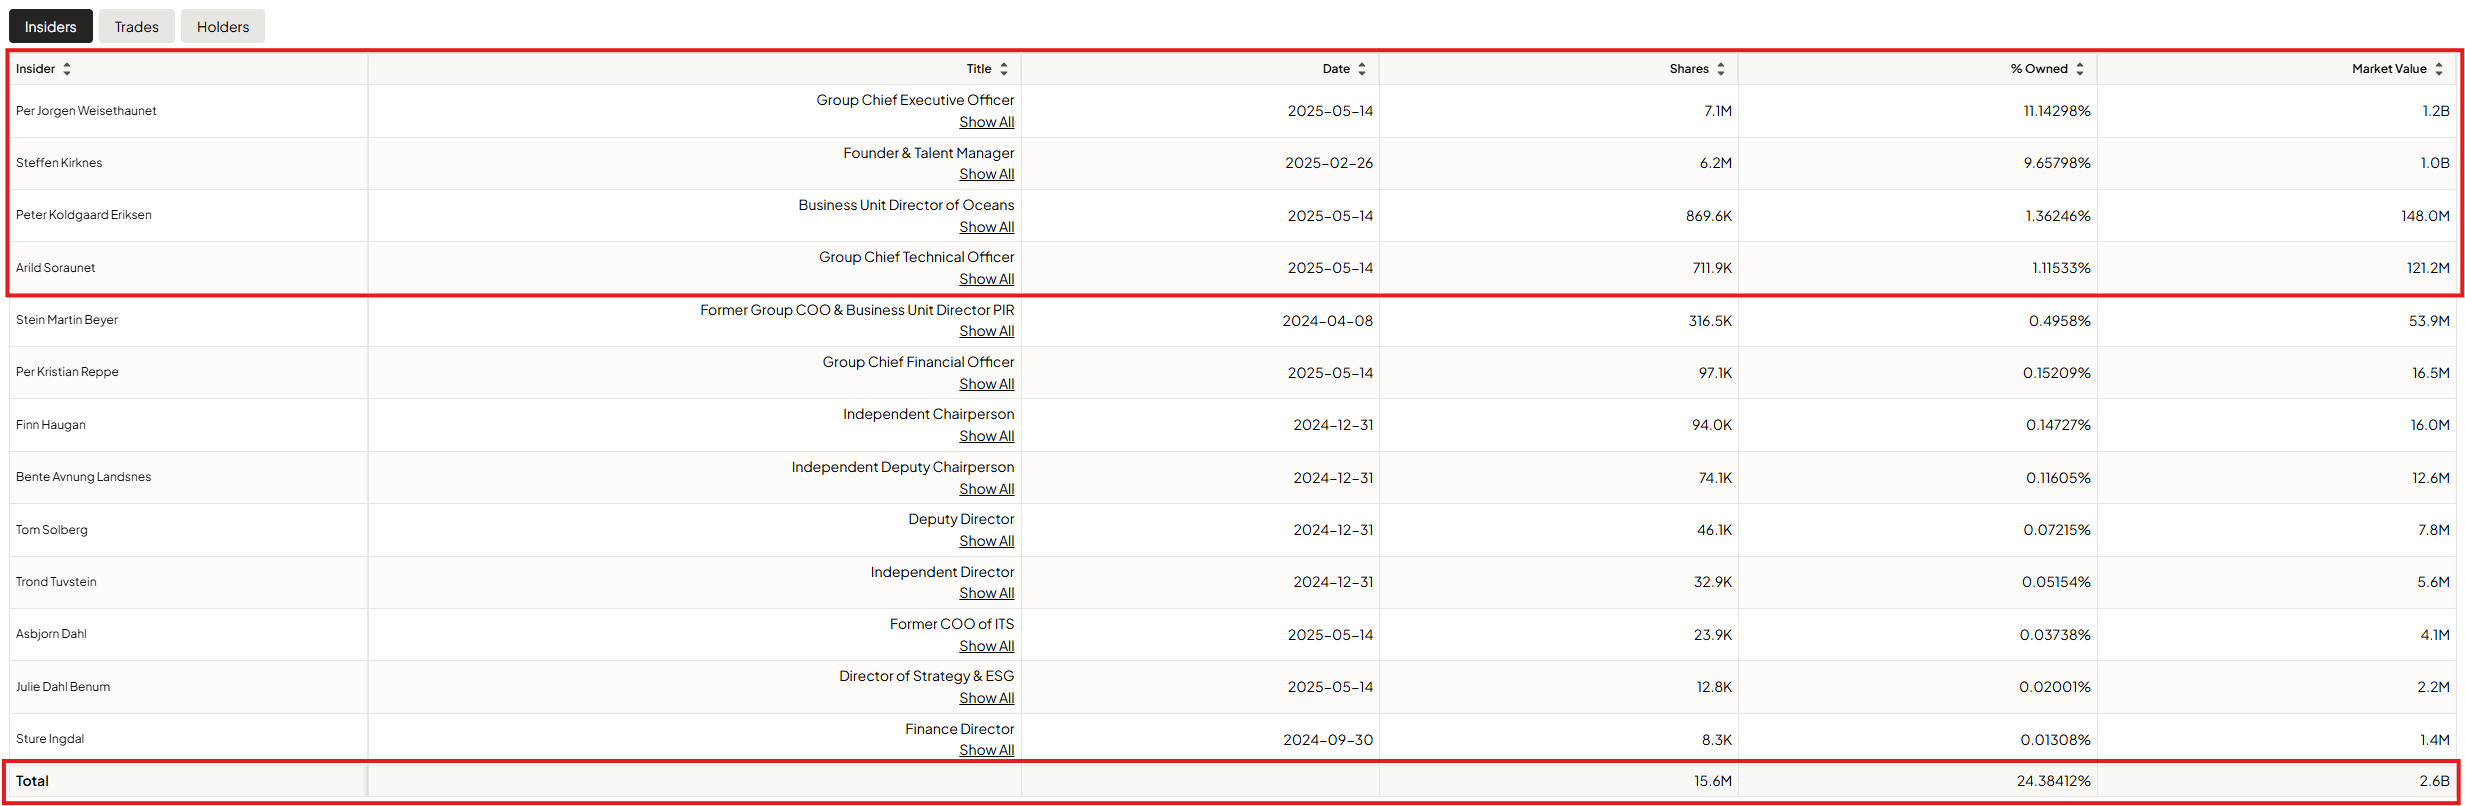
The top four, including the CEO, hold ~22% of the total outstanding shares, talking about insider ownership, right?
In total, insiders own ~24% of Norbit ASA.
I’m a fan of significant insider ownership, but this is beyond my wildest dreams. Management with this type of skin in the game is unreal. Could we expect this to stay like this? Probably not. Dilution of management is common to attract investors or other equity players to provide capital in return for a stake in the company. But, then again, this isn’t always the case.
For now, there’s significant skin in the game. Why is this crucial information to us (potential) investors? Because we have a higher degree of certainty that when management makes an important call for the company, like an acquisition or (international) expansion that comes with significant cost, it will most likely be value-accretive. Why? Because management has a considerable amount of wealth tied up in the company's stock. If management were to start making value-destructive acquisitions or any other plans, both their wealth and the company's are at risk.
Yes, there’s still uncertainty about whether their decision will work out in the company's favor, among investors, and others. Still, knowing that management also faces significant risk on their side, we can be assured that management has thought out their plan extremely well.
Who would make value-destructive decisions that would negatively impact their wealth? Not me!
If you invest your hard-earned money somewhere, you do your best to ensure you make the best decision.
Norbit ASA management does this as well.
👉 You're one step away from joining the Fluent Few, rational investors who don't just watch from the sidelines. Get full access to this investment case, future deep dives, and the private portfolio by upgrading today.
4. Competitive and Sustainable Advantage (Economic Moat)
So, a MOAT can be in one or more of the following forms:
Brand Power
Patents
Scale and Cost Advantages
Switching Costs
Network Effect
Attracting Talent (I consider this a MOAT, others don’t. Decide for yourself)
