

To all the Fluenteers and the Fluent Few, welcome back!
A friend and community member, Mats, recently pulled several high-quality companies out of his sleeve, as if it were no effort at all. It’s amazing. One of these companies, he suggested, is Protector Forsikring ASA, a Norwegian insurer.
In today's investment case, we’re going over Forsikring ASA. After this investment case, you know everything you need to know.
What the company does.
How financially fit is this company?
What we could expect from this company.
Potential risks, headwinds, and tailwinds.
And, of course, if now is the right time to buy or if we should wait.
Thank you, Mats, for bringing this company to my attention.
With that said…
Happy compounding!
What Will Be Discussed:
Corporate Analysis
1.1 Business Overview
1.2 Revenue Breakdown
1.3 KPIsExecutive Leadership
2.1 CEO Experience
2.2 Management Compensation
2.3 CEO Value CreationInsider Ownership
Competitive and Sustainable Advantages (Economic Moat)
Industry Analysis
5.1 Industry Growth Prospects
5.2 Competitive BenchmarkingRisk Assessment
Financial Stability
7.1 Asset Evaluation
7.2 Liability AssessmentCapital Structure
8.1 Expense Analysis
8.2 Capital Efficiency ReviewProfitability Assessment
9.1 Profitability, Sustainability, and Margins
9.2 Cash Flow AnalysisGrowth Projections & Expect Annual Return
Value Proposition
11.1 Dividend Analysis
11.2 Share Repurchase Programs
11.3 Debt Reduction StrategiesQuality Rating & Checklist
Valuation Assessment
1. Corporate Analysis
1.1 Business Overview
Protector Forsikring ASA is a Norwegian insurance company offering a wide range of non-life insurance services. That means they cover things like property damage, motor vehicles, liability, personal injuries, and more, not life or health as a core area.
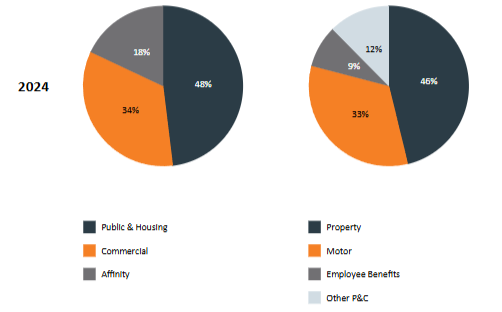
Protector Forsikring provides this insurance service not solely in Norway, but also in the UK, Sweden, Finland, Denmark, and France.
Protector Forsikring targets commercial lines (businesses) and public lines (municipalities/public bodies). This means that Protector Forsikring does not offer its insurance services to regular consumers, such as you and me, but instead offers them solely to companies and public bodies, including governments.
They’re a B2B, not B2C, service provider.
Being a B2B insurer brings significant benefits, which will be discussed later.
Protector Forsikring was founded in 2003 and currently has approximately 600 active employees, helping to bring the Company to new heights globally.
1.2 Protector Forsikring ASA Revenue Breakdown
Insurance companies have different types of income statements compared to your favorite consumer or tech company. Insurance companies have premiums and annuity revenue, interest/dividends from investment, policy benefits, and much more, which ‘‘clutter’ the income statement and all require some explanation to paint the right picture.
So, bear with me here.
For insurance companies, their income comes from investments they make (yes, they’re basically like you and me, investing in bonds and equities), as well as premiums and annuities (Protector Forsikring is a non-life insurer; this means they do not do annuities).
I have confidence that you’re aware of what these revenues are, but to avoid any confusion, I will review them.
These premiums are the price you pay to the insurer for the insurance. These payments are made on a monthly, quarterly, or yearly basis. In return, the insurer covers you in the event of an accident.
Your company insures its car fleet with Protector Forsikring. Protector Forsikring says: “Pay €600 per year.”
That €600 = the premium.
In short, Protector Forsikring earns money from interest and dividends on its investments, the premiums, and the sale of investments.
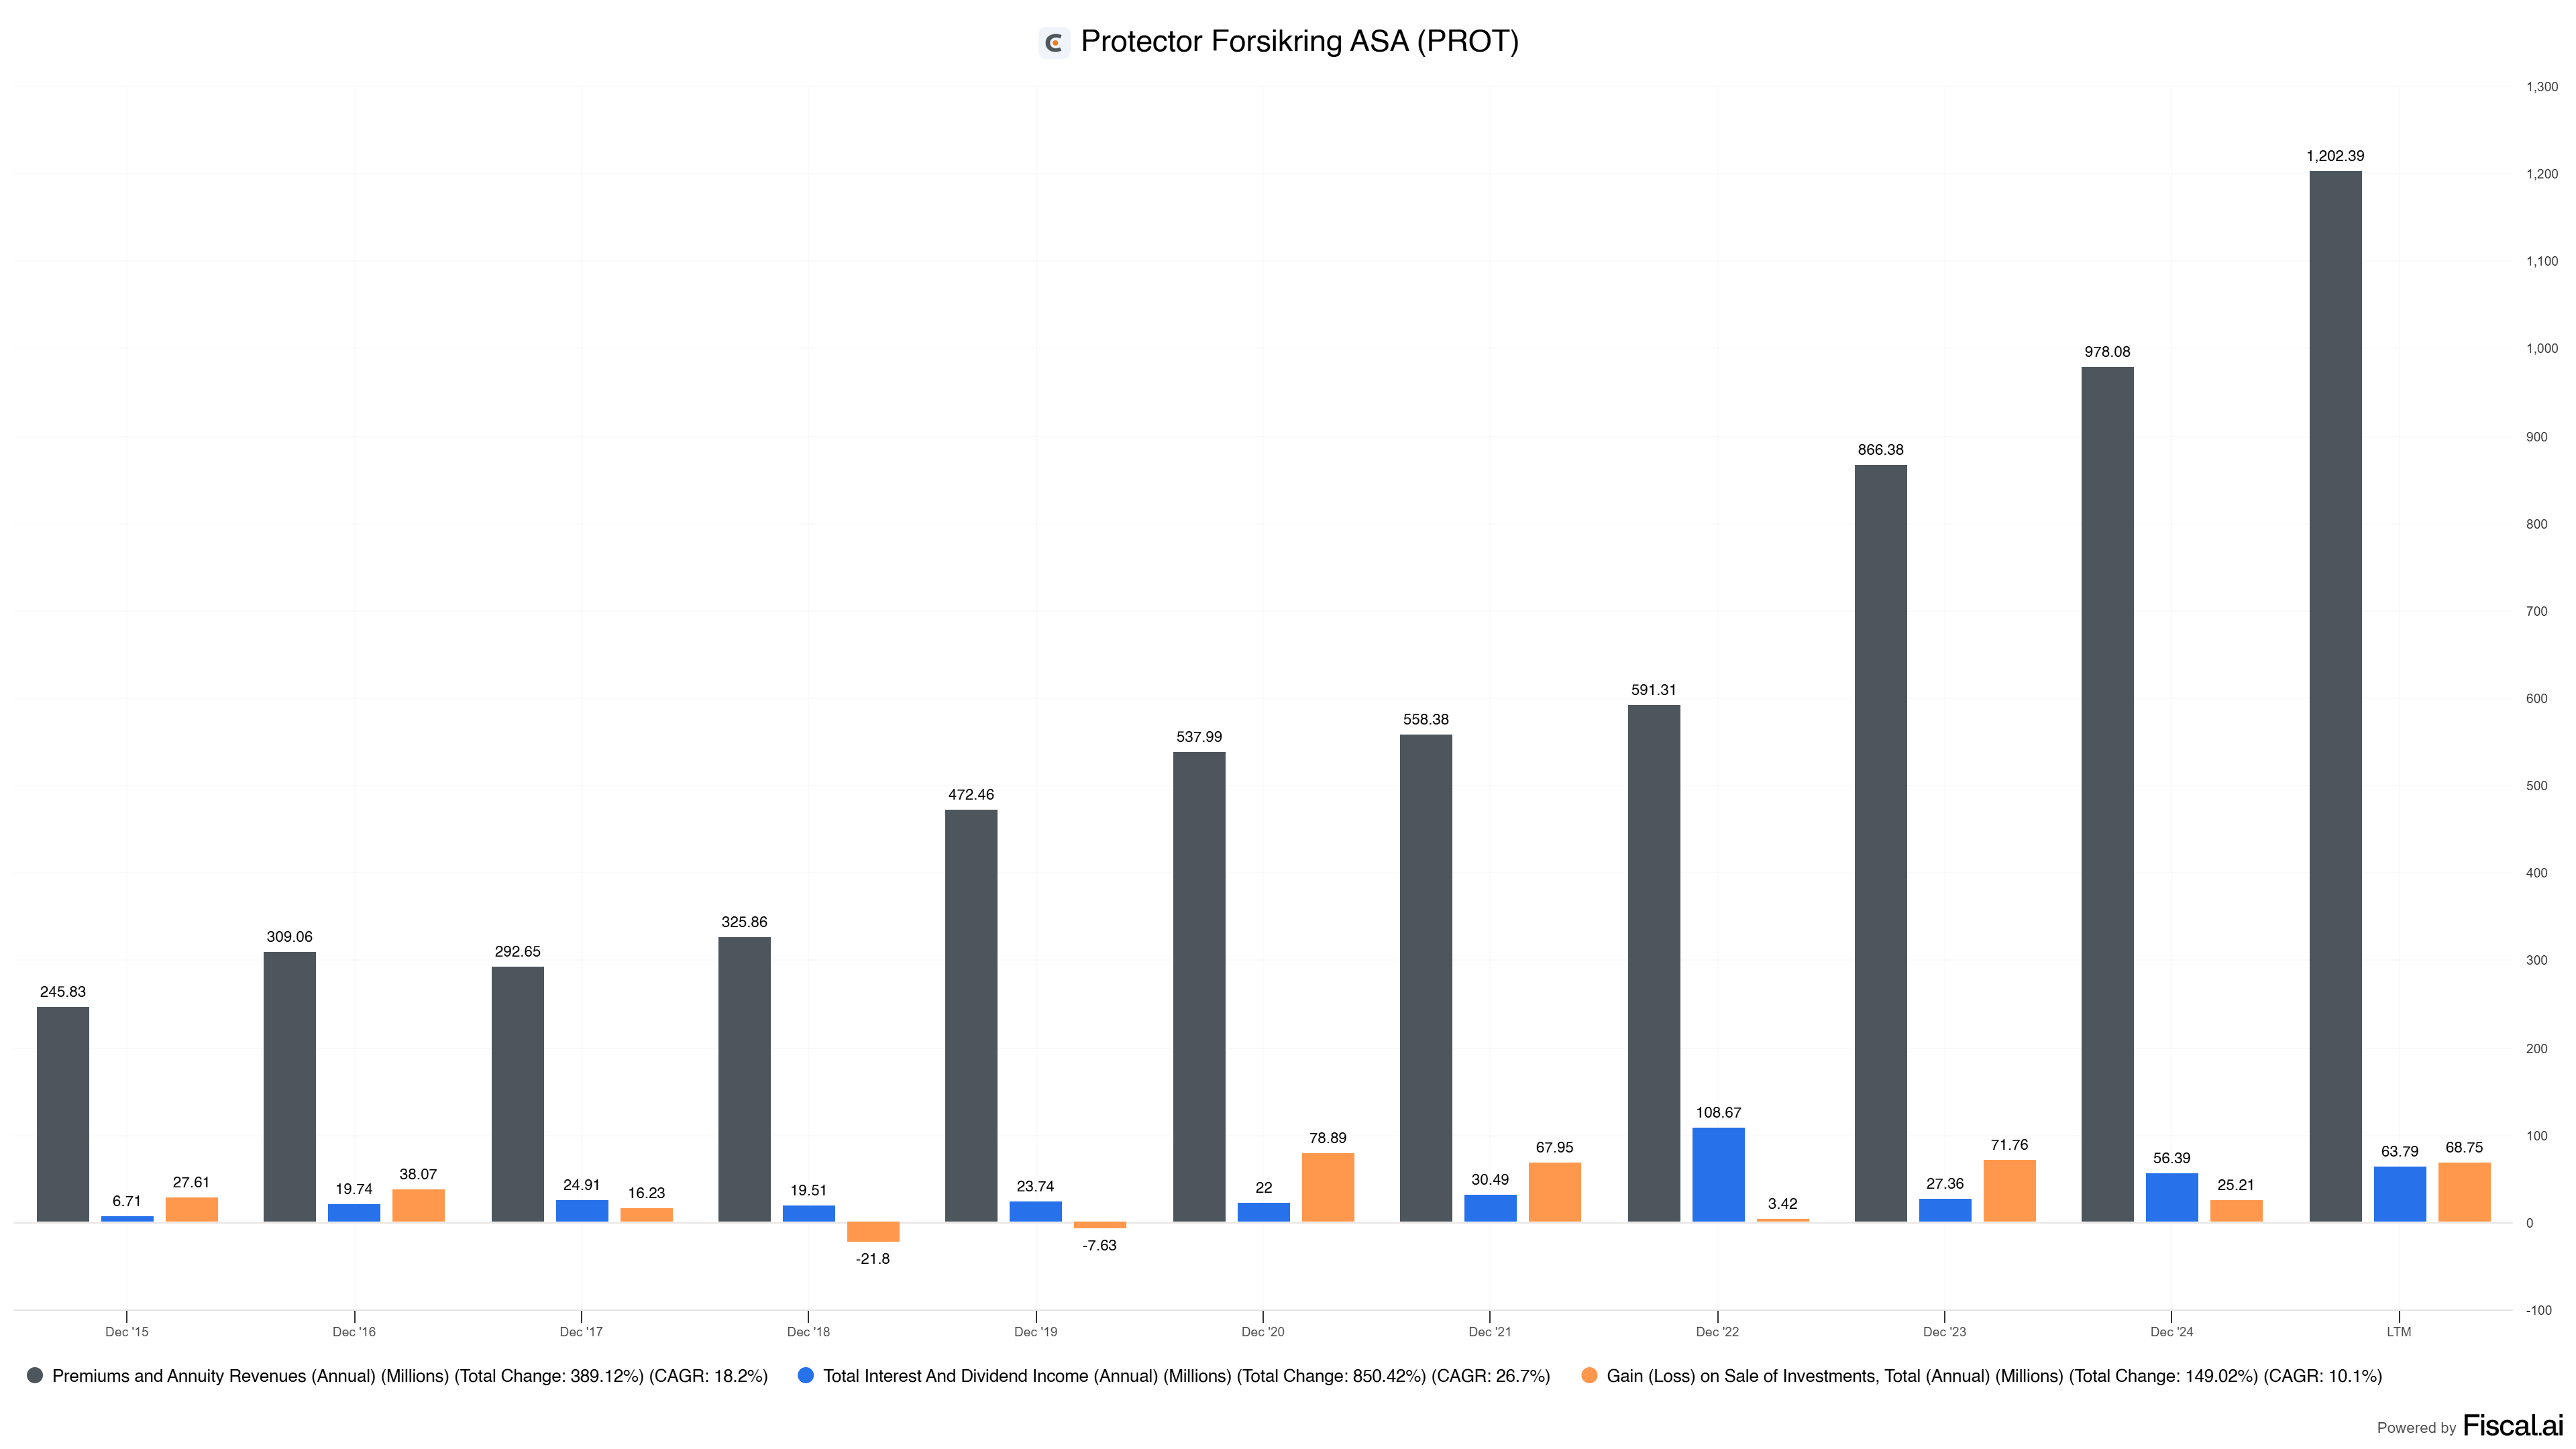
Here’s a clear view of Protector Forsikring’s total earnings over the years.
Why does Protector Forsikring invest cash in bonds and equities? Good question!
Protector Forsikring gathers premiums from its customers. They do not just let these premiums sit and lose value in their banks. Protector Forsikring invests this cash into bonds and equities to generate investment income until it needs to pay any claims. They invest in bonds because these tend to be low-risk and stable investments. This provides predictable interest income that helps Protector Forsikring
Cover claims that come in later.
Maintain financial stability.
Meet regulatory requirements for solvency.
So, why do they also invest in equities?
Equities tend to be riskier but offer higher returns for Protector Forsikring. Look at Protector Forsikring like yourself. You could invest solely in bonds, but if you need a higher return, you steer over to equities. Although there's a higher risk, there is also a higher reward.
Protector Forsikring carefully allocated capital into equities so that Protector Forsikring can
Increase long-term investment returns.
Grow its capital base.
Improve profitability for shareholders.
Protector is essentially doing two things at once:
Insurance business – collecting premiums and paying claims.
Investment business – putting that premium money to work in bonds and equities to earn extra income.
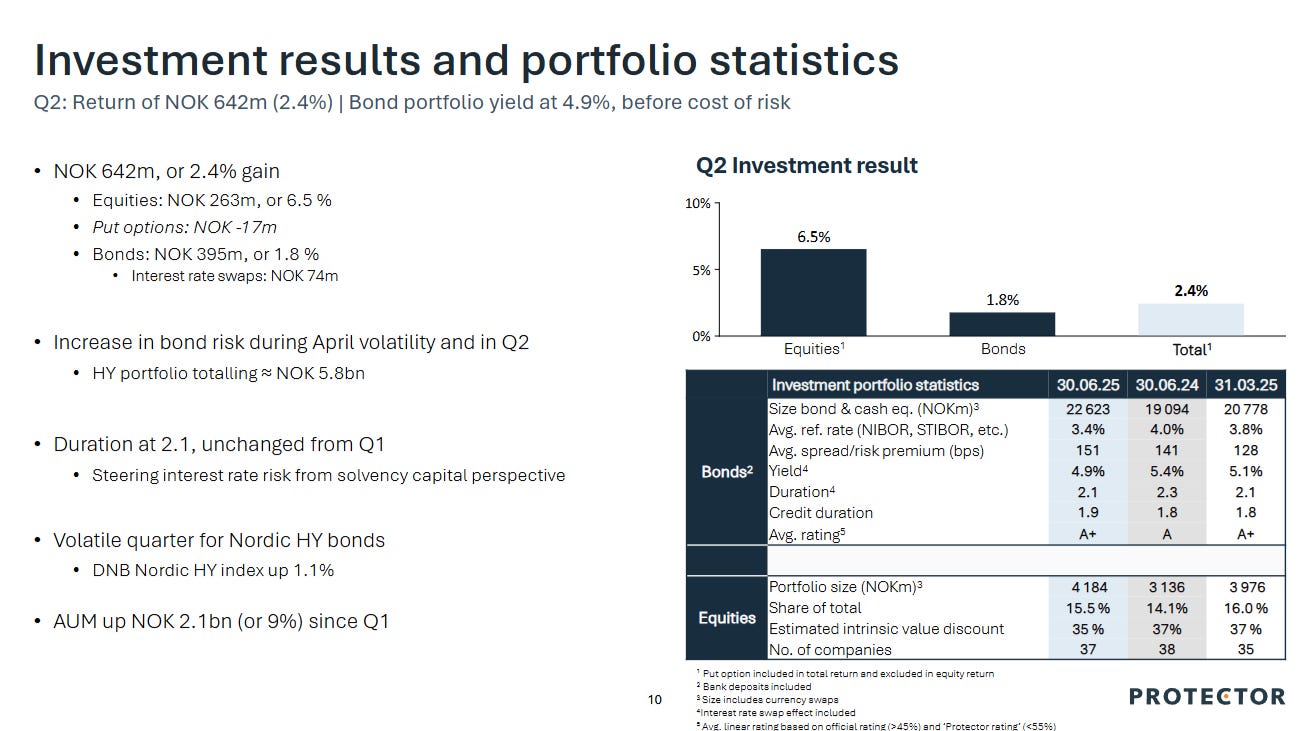
Protector Forsikring currently has a portfolio of NOK 26 billion (approximately $2.57 billion), up 9% compared to the previous quarter.
Protector Forsikring maintains a healthy and balanced investment portfolio. They’re primarily into bonds, as expected, since it is considered ‘‘safer’’. However, they do have some exposure to equities, which provides a slightly higher return boost to their portfolio.
Their portfolio is growing. This means we can expect their interest and dividend income to increase as well, generating additional revenue for both shareholders and the company. However, this also makes Protector Forsikring more solvent.
This is crucial for any insurer.
So, how is their premium revenue split up globally? Let’s go over this.
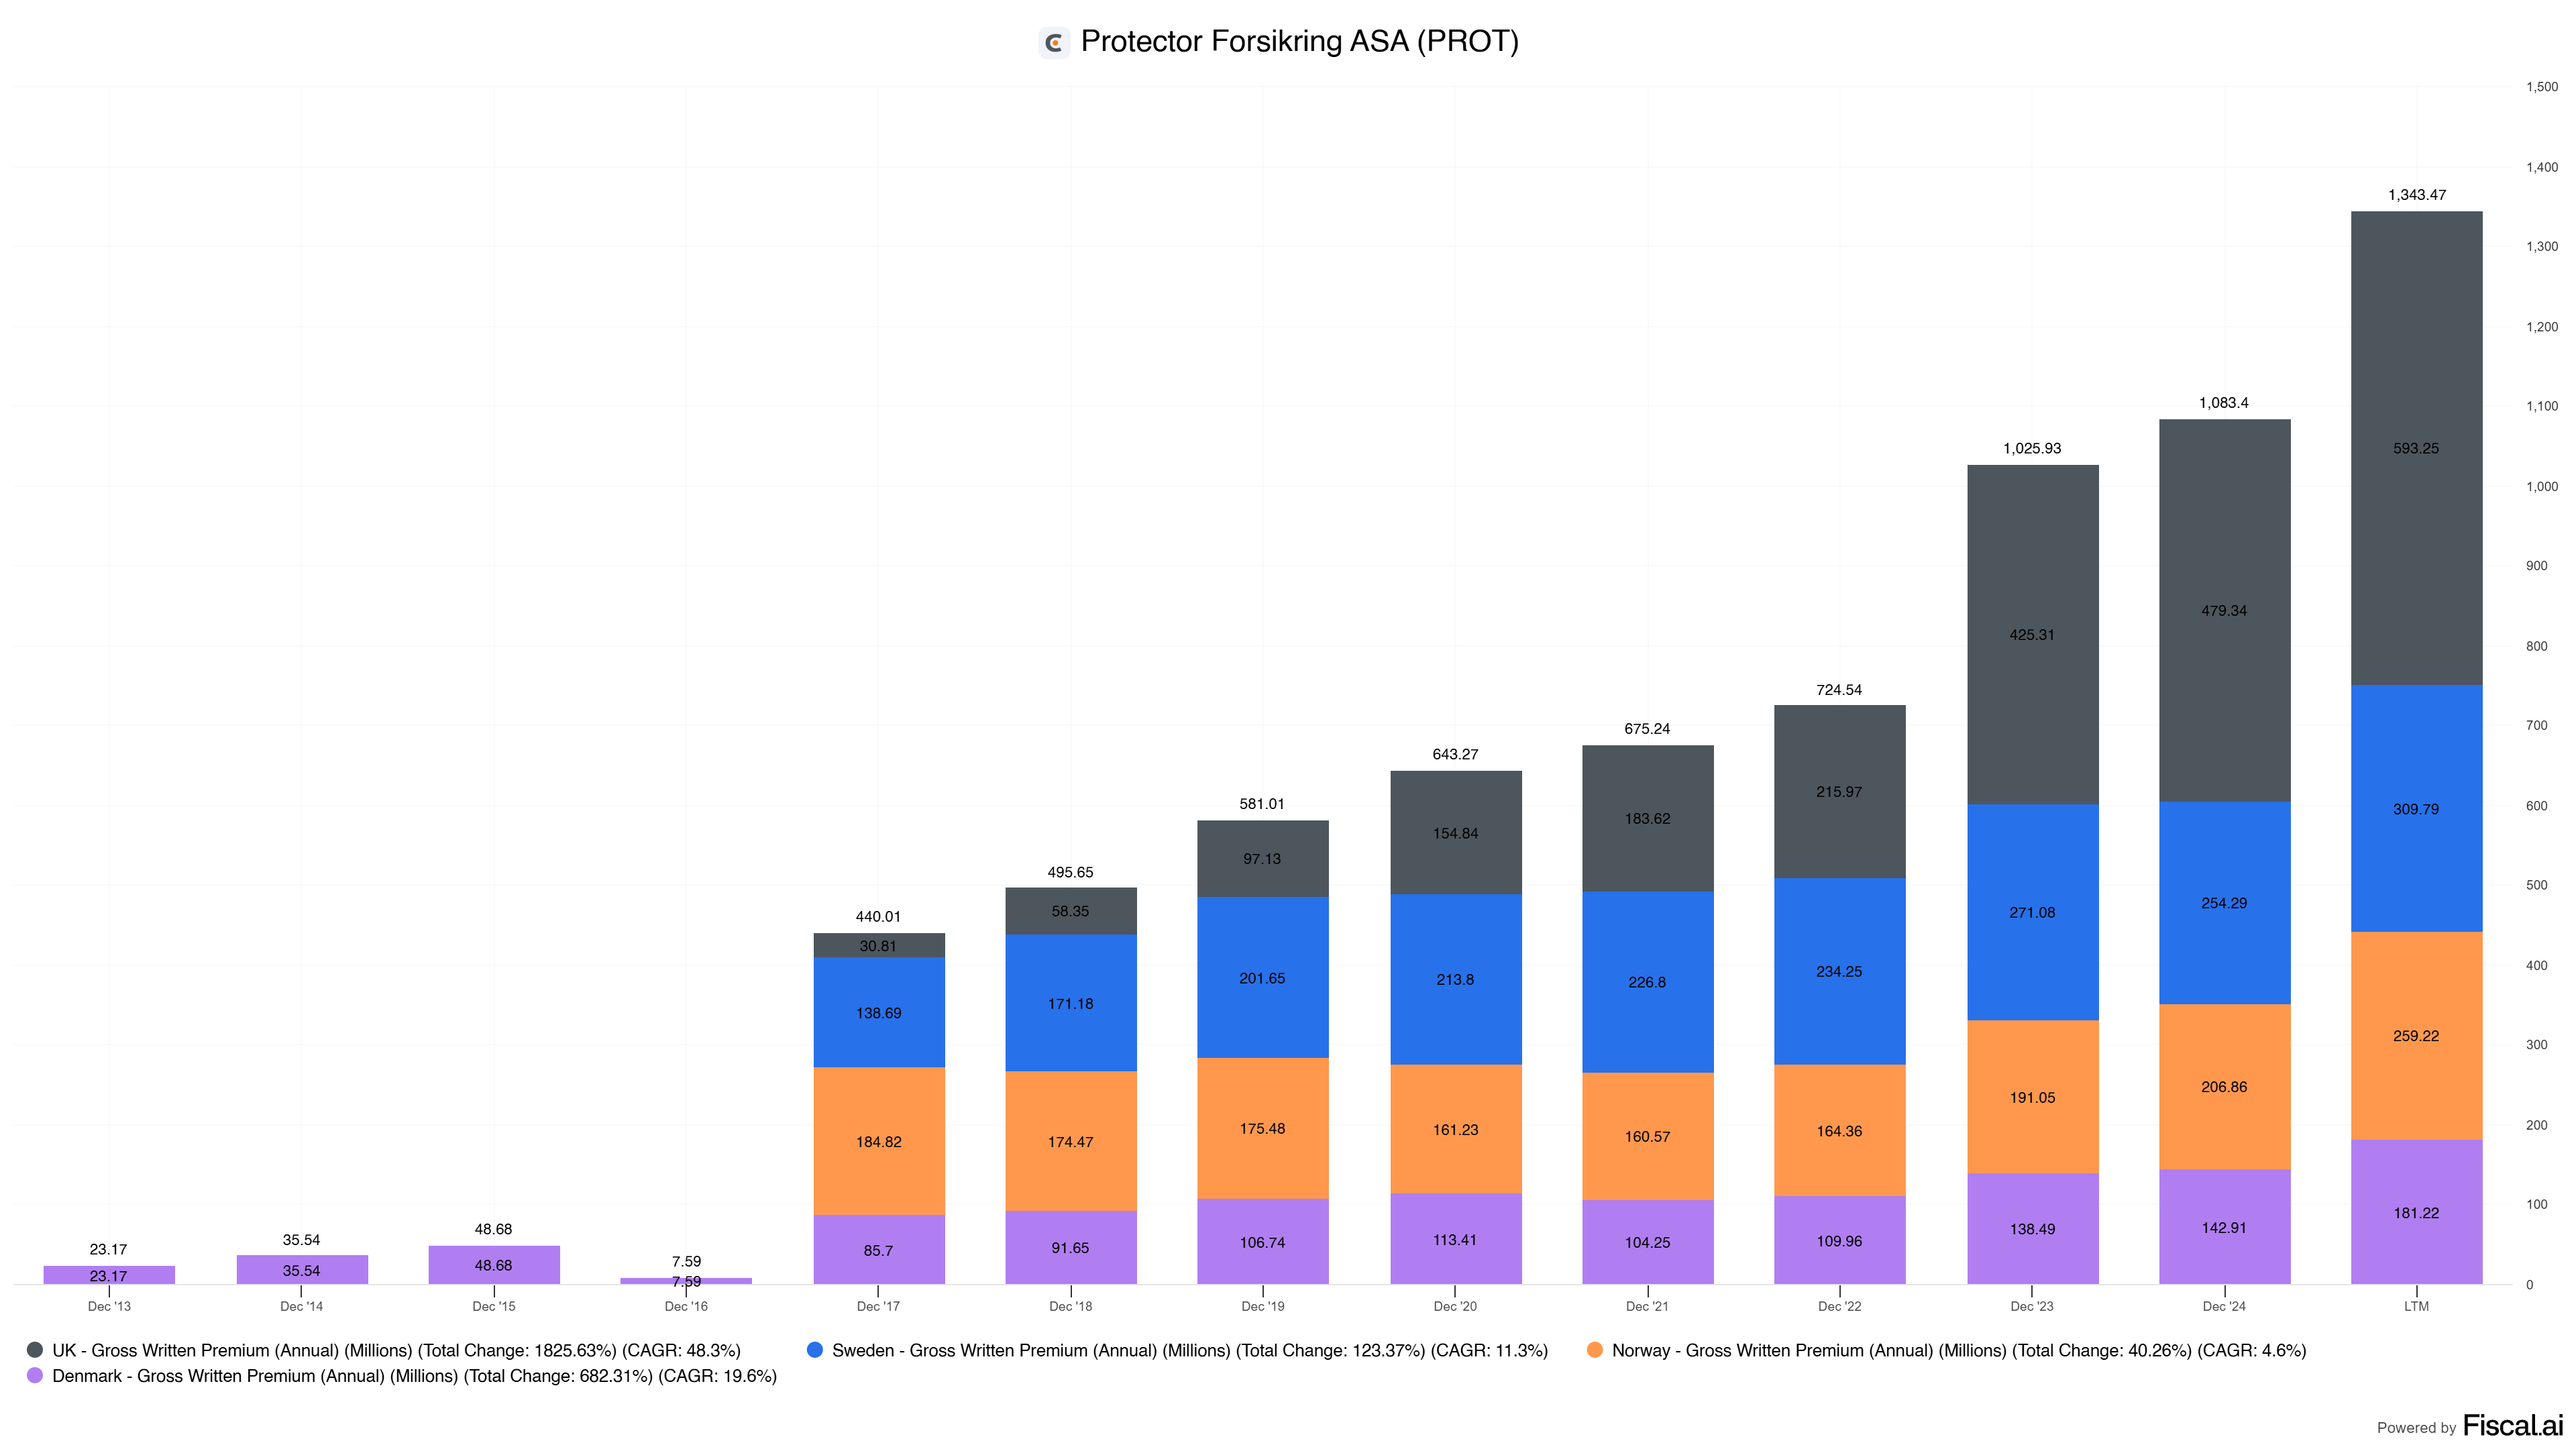
Since its global expansion, Protector Forsikring has experienced significant growth, particularly in the UK. Now, the numbers look good. Let us quickly look at what country takes up what percentage of the revenue, shall we?
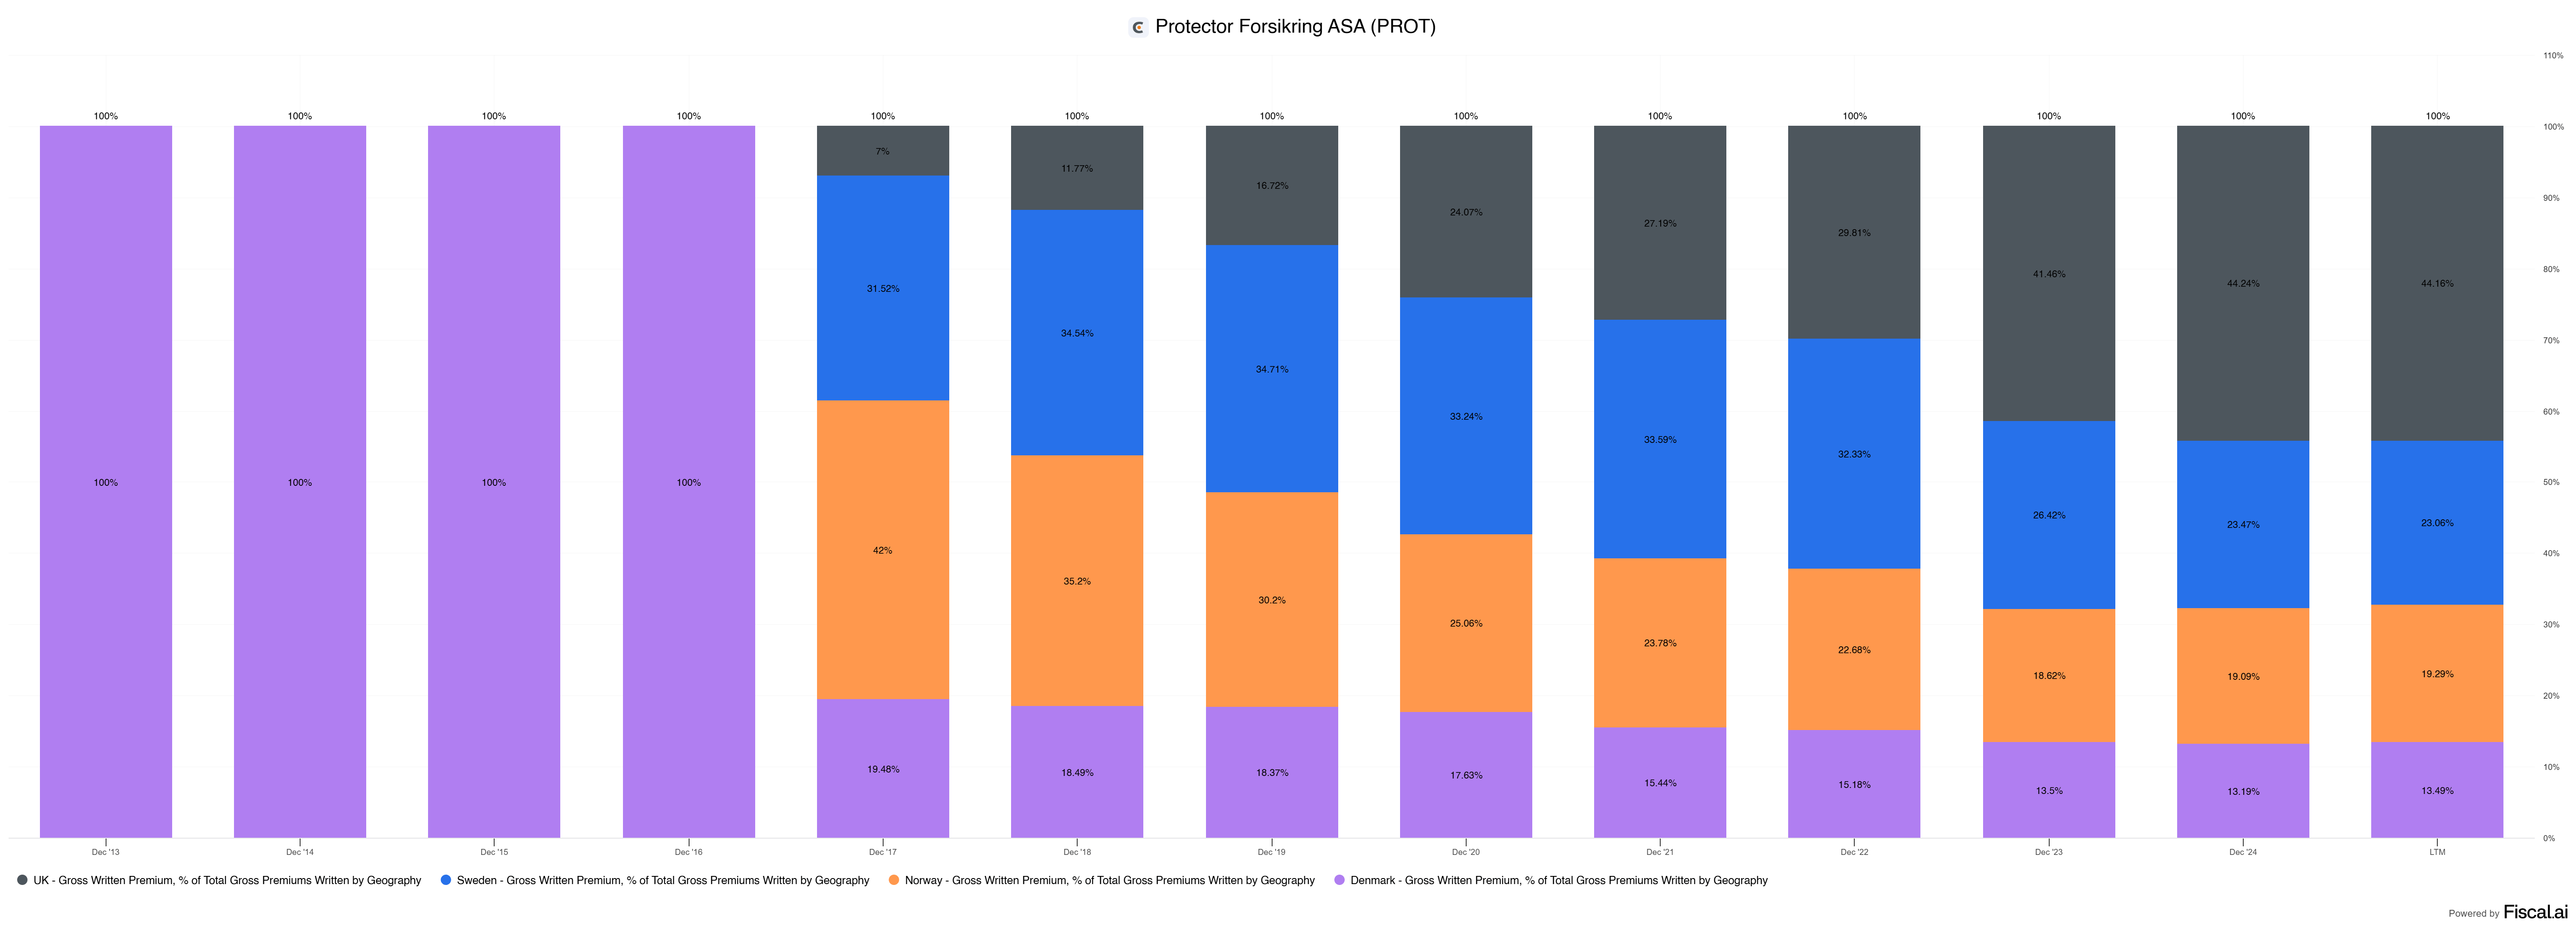
The UK accounted for only 7% of the total revenues in 2017. This number increased to 44.16% over the latest twelve months. Denmark has remained a stable contributor to the total revenue. Back in 2017, Denmark accounted for 19.48% of the total revenue. As per the latest twelve months, Denmark accounts for 13.49% of the total revenue.
Countries like Norway and Sweden (including Finland) and their shares in the total revenue declined. Does this mean they brought in less revenue? No, not at all.
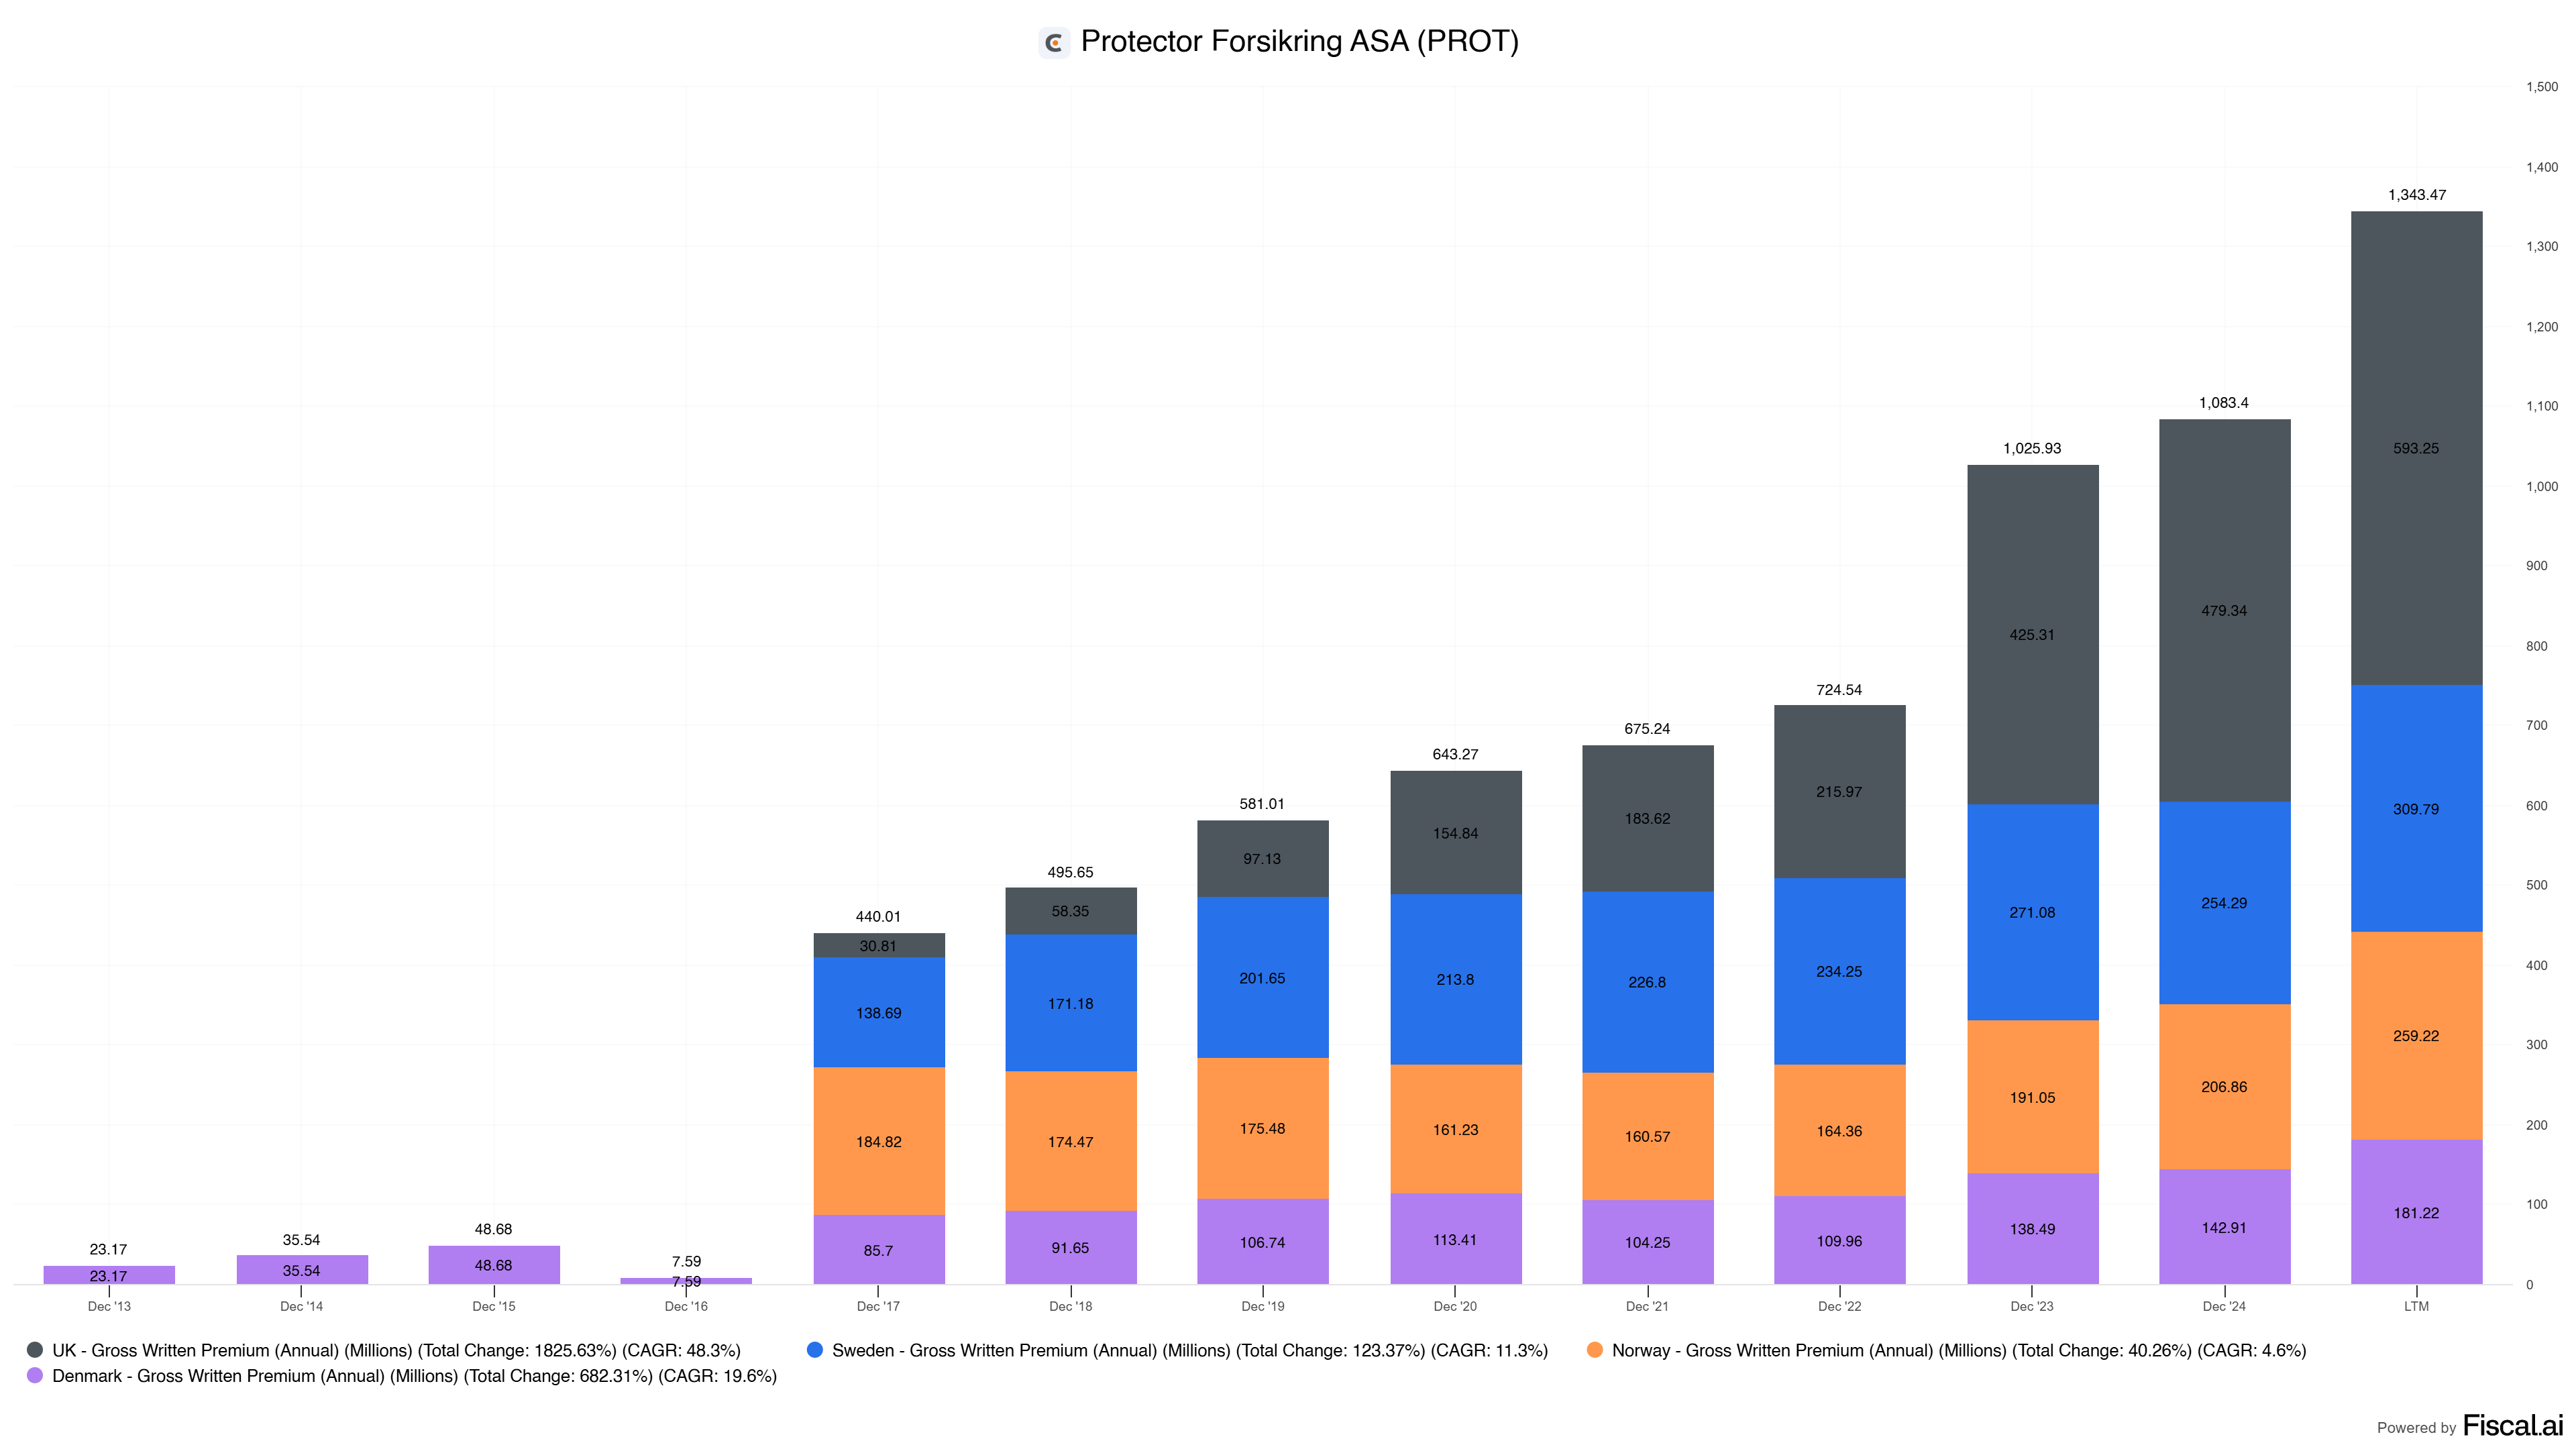
As shown here, all countries continued to show revenue growth. The UK, however, has been a significant growth driver for Protector Forsikring, accounting for a larger share of the total revenue.
Pretty funny - a Norwegian insurer that generates most of its revenues from the UK. Norway ranks third in terms of top revenue contributors… Protector Forsikring managed to do this via aggressive positioning in targeted settlements. Protector Forsikring's strategy focuses on high-growth, high-value sectors rather than spreading itself too thinly across countries.
Well, their strategy is definitely working in the UK!
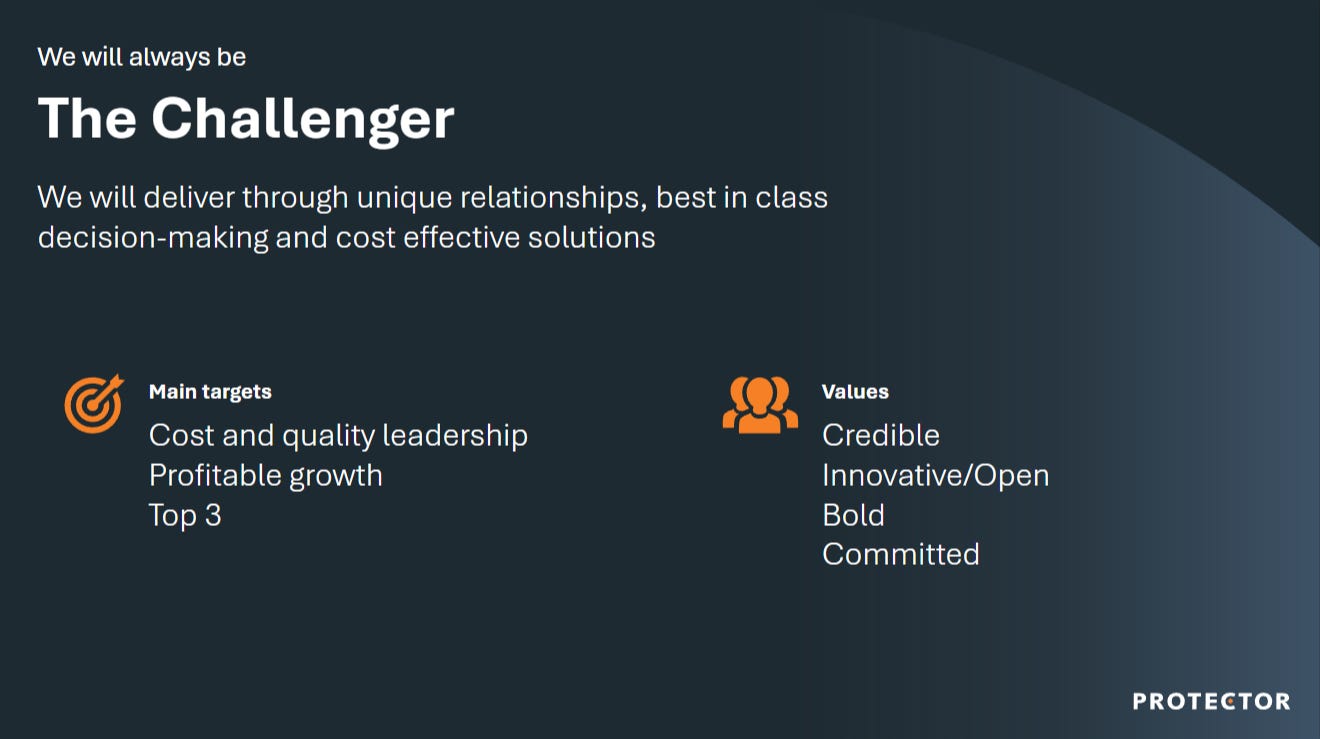
Their values include ‘‘bold’’ and ‘‘committed’’.
They most definitely are geography-wise.
And they’re doing so while remaining satisfied by the consumers, that’s unique. Aggressive growth often comes with the cost of consumer dissatisfaction, but this is not always the case.
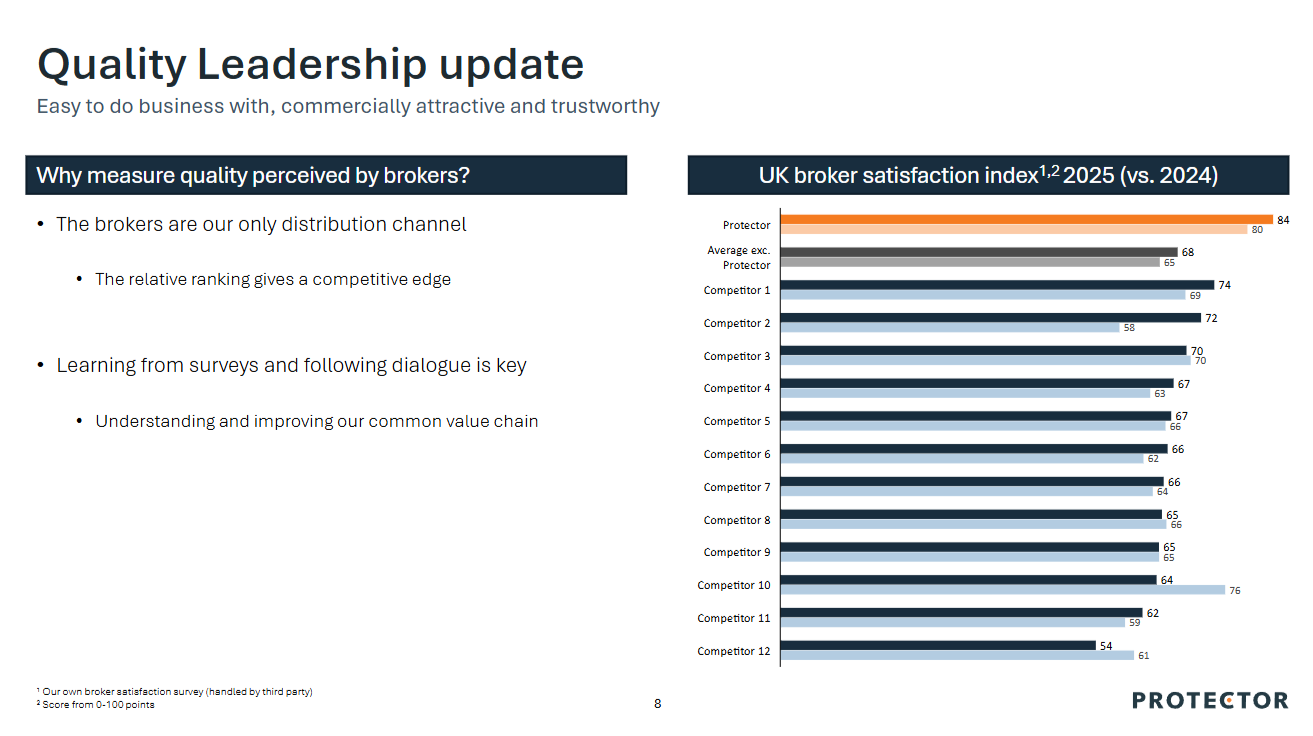
Yes, yes, yes… earning slides tend to make things look prettier than they actually are. But after a couple of Google searches, Protector Forsikring comes out on top in almost all the searches (I searched the satisfaction rate amongst insurers in the non-life industry)
1.3 KPIs
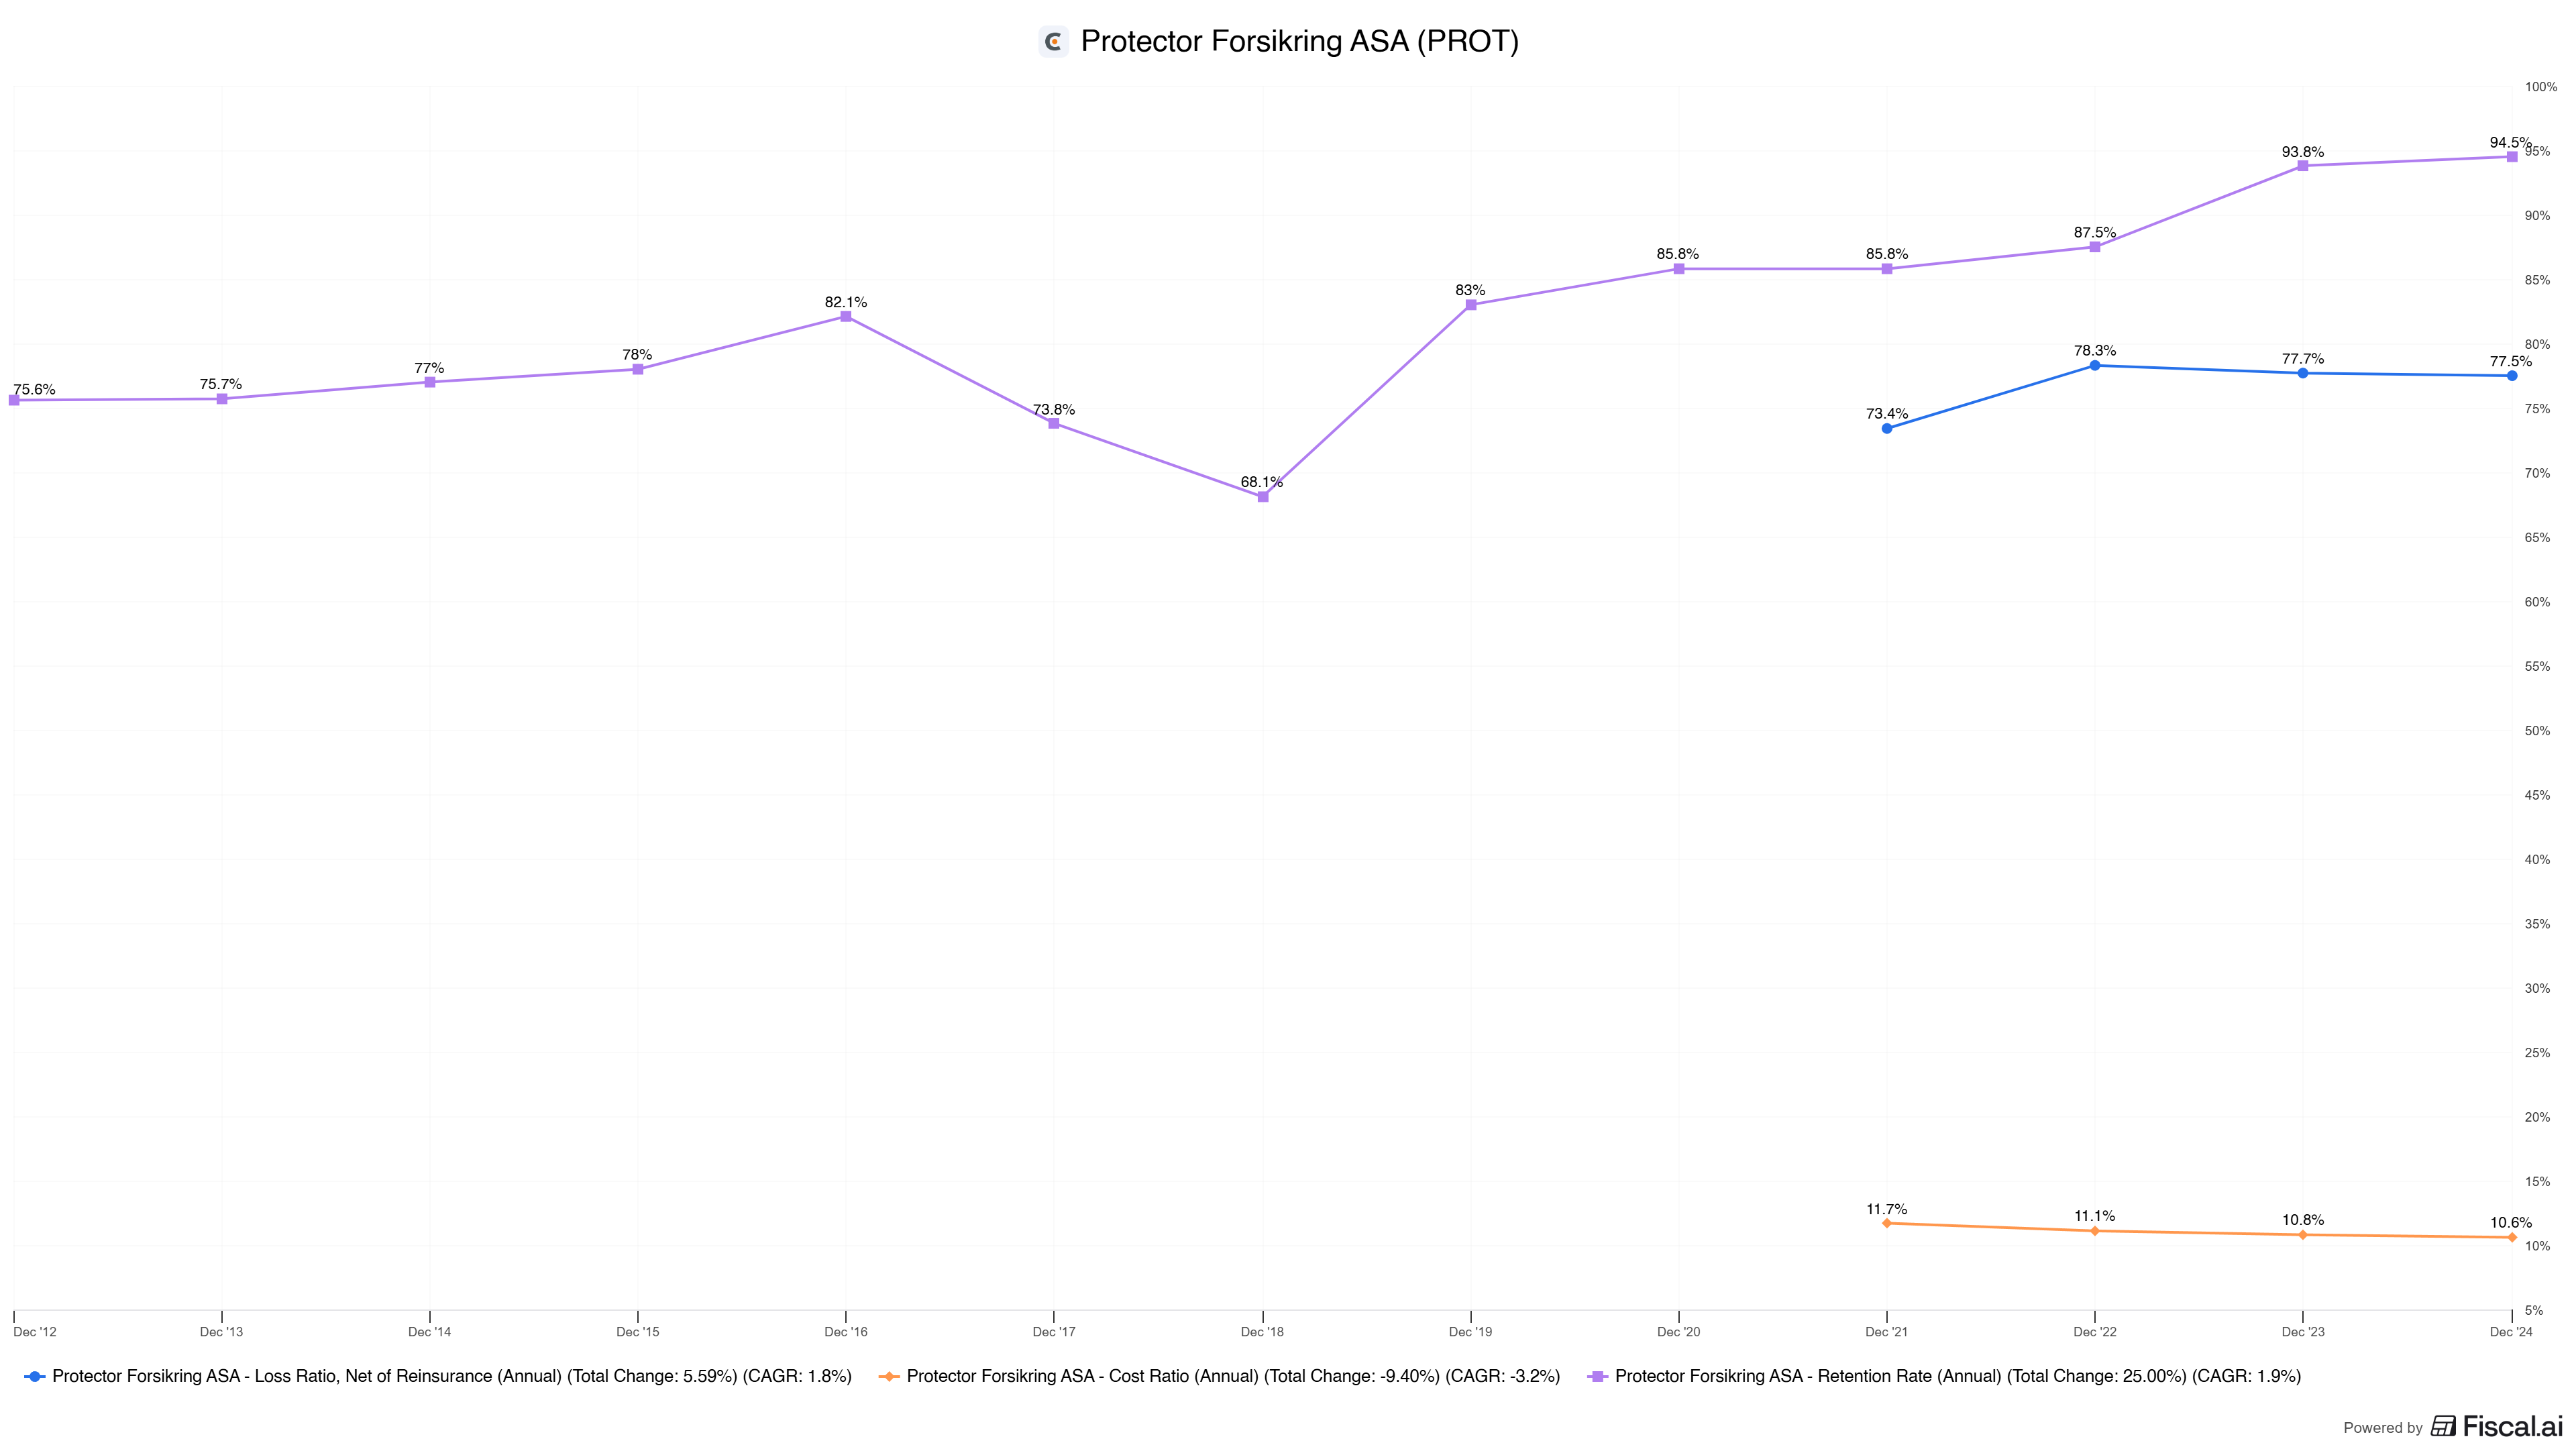
A quick overview of some of the important KPIs for Protector Forsikring ASA.
Loss Ratio, Net of Reinsurance: % of premium paid out in claims after reinsurance. Lower = better underwriting.
Cost Ratio: % of premium spent to run the business (commissions, admin). Lower = leaner operations.
Retention Rate: % of customers/premium insurers who renew. Higher = stickier, cheaper-to-serve book.
One of the best ways to understand an insurer’s quality is through its underwriting KPIs. For Protector, three numbers stand out: the loss ratio, the cost ratio, and the retention rate. Together, they tell us how well the company prices risk, how efficiently it runs, and how “sticky” its customer relationships are.
The loss ratio, which measures the share of premiums paid out in claims after reinsurance, is the clearest indicator of underwriting discipline. Protector’s loss ratio spiked in 2022 as inflation drove up claims severity and frequency across the industry. What’s notable is how quickly the ratio stabilized, settling into a tight band in the high 70s. That stability suggests that Protector has been able to adjust pricing in step with claims pressures, an essential sign that management can maintain underwriting profitability even in a more challenging claims environment.
The cost ratio tells a different but complementary story. This metric indicates the proportion of each premium krone allocated to running the business, including commissions, administration, and operating expenses. Protector’s cost ratio has consistently hovered around 10–11 percent, which is leaner than almost any major Nordic competitor. Over time, the company has managed to squeeze additional efficiency from its model, a reflection of both scale benefits and tight cost control. Even a half-point or one-point improvement here translates directly into a more substantial underwriting margin, and Protector has made a habit of defending this efficiency edge.
Perhaps the most impressive trend is the retention rate. A decade ago, roughly three-quarters of Protector’s customers renewed their policies. Today, that figure stands above 94 percent. This is more than just a number; it speaks to the durability of Protector’s franchise. High retention means lower acquisition costs, as fewer customers need to be replaced each year. It also supports compounding growth and, critically, it strengthens risk selection. The policyholders who stay are the ones Protector understands best, and that familiarity reduces the risk of unpleasant surprises in claims.
Taken together, these KPIs show a company that has become stickier, leaner, and more resilient over time. Protector’s high retention rate locks in customers and lowers costs, its cost ratio demonstrates exceptional operating discipline, and its loss ratio indicates that pricing power is intact despite inflationary pressures. This combination forms the backbone of Protector’s underwriting advantage—and helps explain why its profitability metrics, particularly ROE, sit well above industry averages.
2. Executive Leadership
2.1 CEO Experience
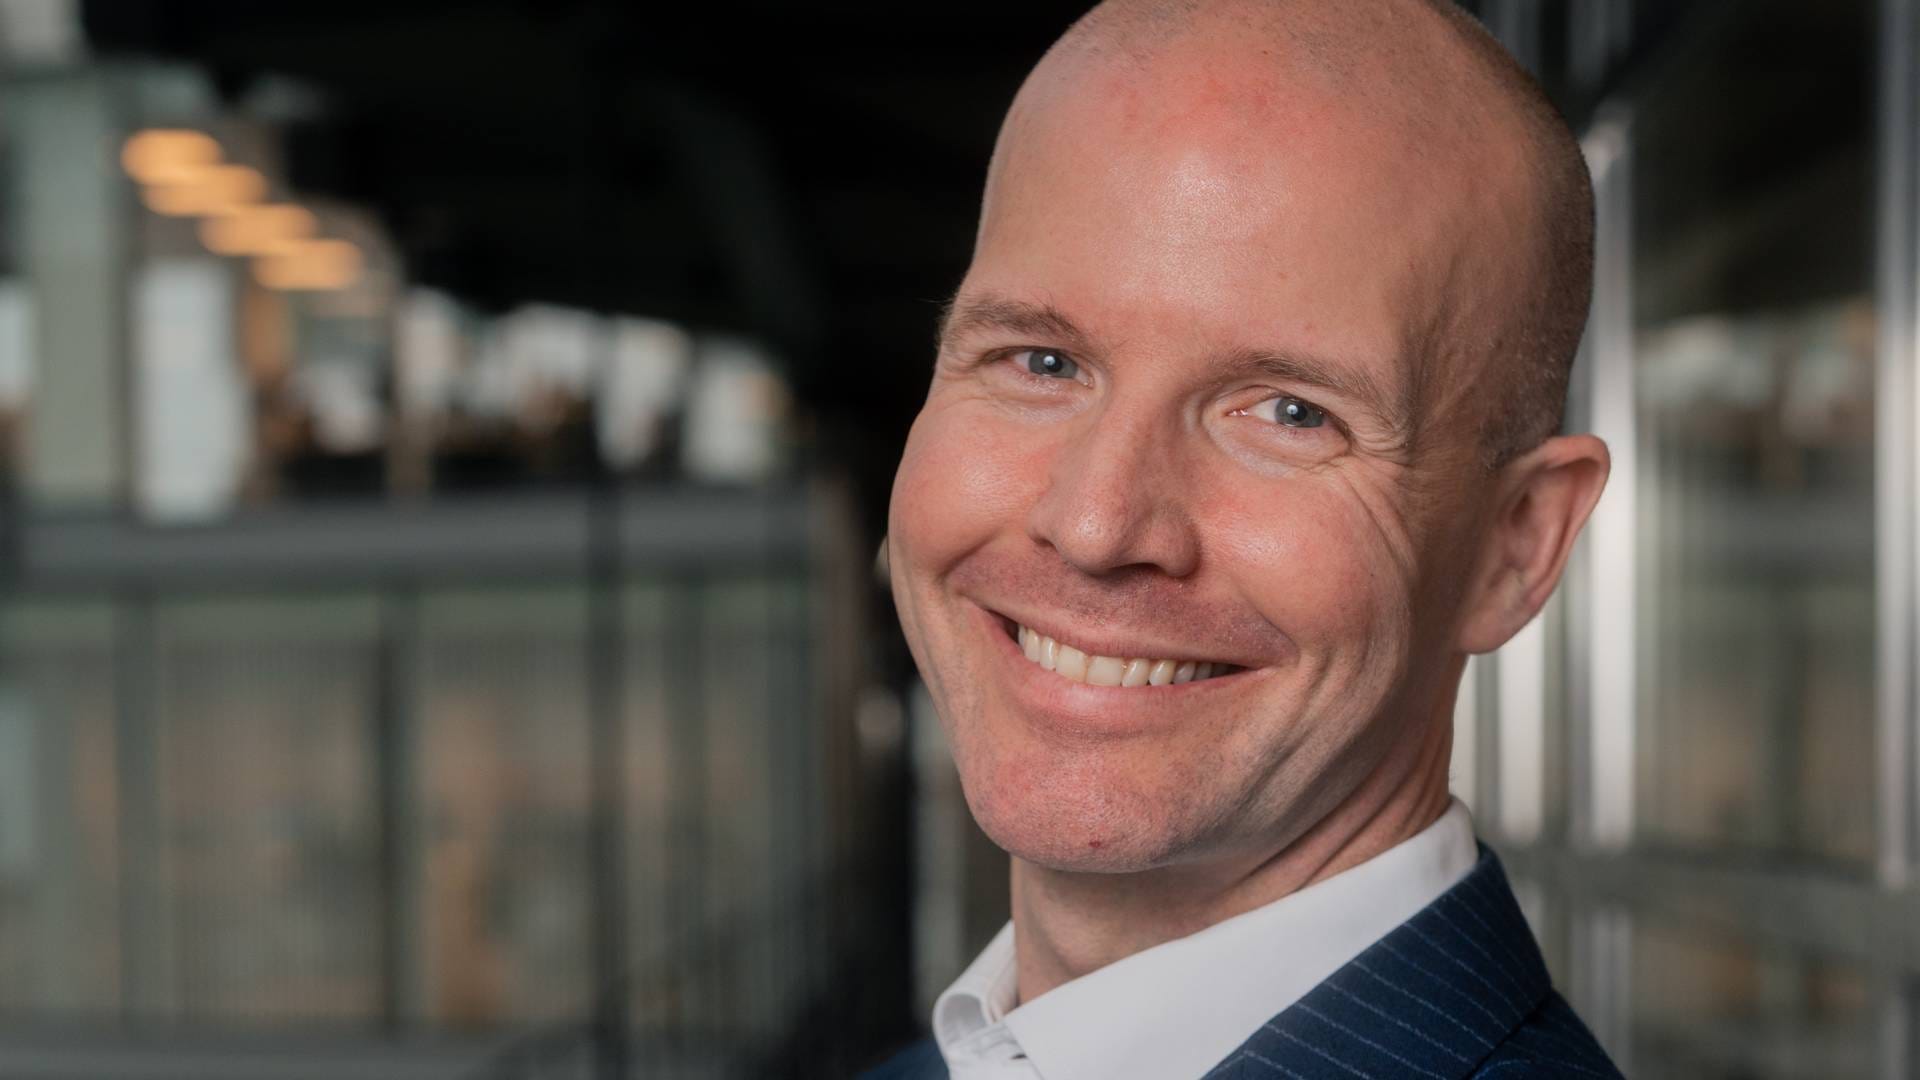
Henrik Golfetto Høye is the CEO of Protector Forsikring ASA.
Henrik holds a Bachelor’s degree in Economics/Finance from the University of Colorado Boulder, specifically from the Leeds School of Business and the College of Arts and Sciences.
Henrik Golfetto Høye joined Protector in 2007, assuming leadership roles that included establishing Protector’s presence in the UK and managing its public sector portfolio. For five years, he served as Deputy CEO under founder Sverre Bjerkeli. In June 2021, Henrik officially became CEO of Protector Forsikring ASA, succeeding Sverre Bjerkeli upon his retirement.
Henrik Golfetto Høye holds 282.2K shares worth roughly 121.1M, which is 0.34% ownership in Protector Forsikring ASA.
Henrik Golfetto Høye has been with Protector for some time, helping the company explore new territory outside its backyard, creating immense value for the company and its shareholders. As we’ve seen in the revenue statement, their expansion into other countries has added significant value, making their work in this area crucial to the company's growth.
I would argue that there’s a competent man at the helm of this company.
Moreover, Henrik Golfetto Høye has significant skin in the game. If we go over his salaries, we can see to what extent exactly.
In 2021, Henrik Golfetto Høye brought home a total of 19.7 million NOK, which is roughly $ 1.87 million. Of that total salary, roughly $ 650,000 was his base salary; the rest was bonuses based on his performance. The performance goals are long-term objectives, such as improvements in underwriting and enhancements to processes that optimize customers' and personal experiences, among others.
In 2022, Henrik Golfetto Høye earned 9.0 million NOK, equivalent to approximately $860,000 in total. Of that total, roughly $ 530,000 was his salary, while the rest was compensation, including bonuses/stock.
Let’s now go to 2024.
Here, Henrik Golfetto Høye took home NOK 14.57 million, approximately $1.38 million, with a base salary of roughly $620,000; the remainder was comprised of bonuses and stock compensation.
Comparing his salaries and bonuses, Henrik Golfetto Høye has significant skin in the game, as shown down here.
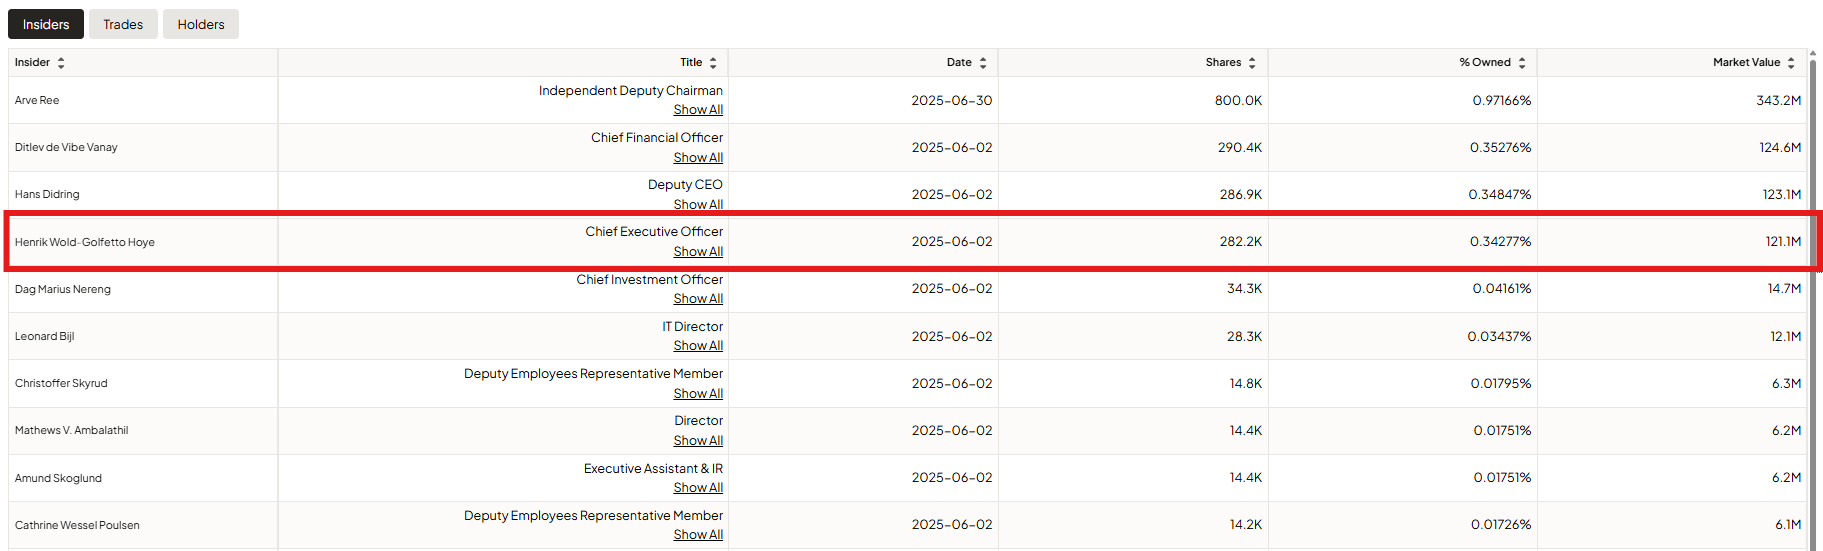
Skin in the game for management, independent directors, and other key roles plays a significant role in our investable universe, as well as in the value-accrual decisions management and its board will make on behalf of the company and its shareholders.
If management has little skin in the game and hefty salaries, their decisions will be felt to a limited extent when compared to management that has significant wealth invested in their company. In the latter, every decision matters to their own benefit (or not) and that of the company.
2.2 Employee Satisfaction Ratings
I’ve been skimming through LinkedIn, Glassdoor, Boardroom, etc, to find verified reviews from (ex) employees. I did find some reviews from these (ex) employees, but I can’t verify these to a certain degree.
It is often the case with these younger companies, which typically have limited employee turnover. I hate to disappoint readers here, but I will not be pushing out reviews that I can not verify to be for Protector Forsikring ASA (since sites are using their name, but reviews do not match up with locations and dates)
2.3 CEO Value Creation
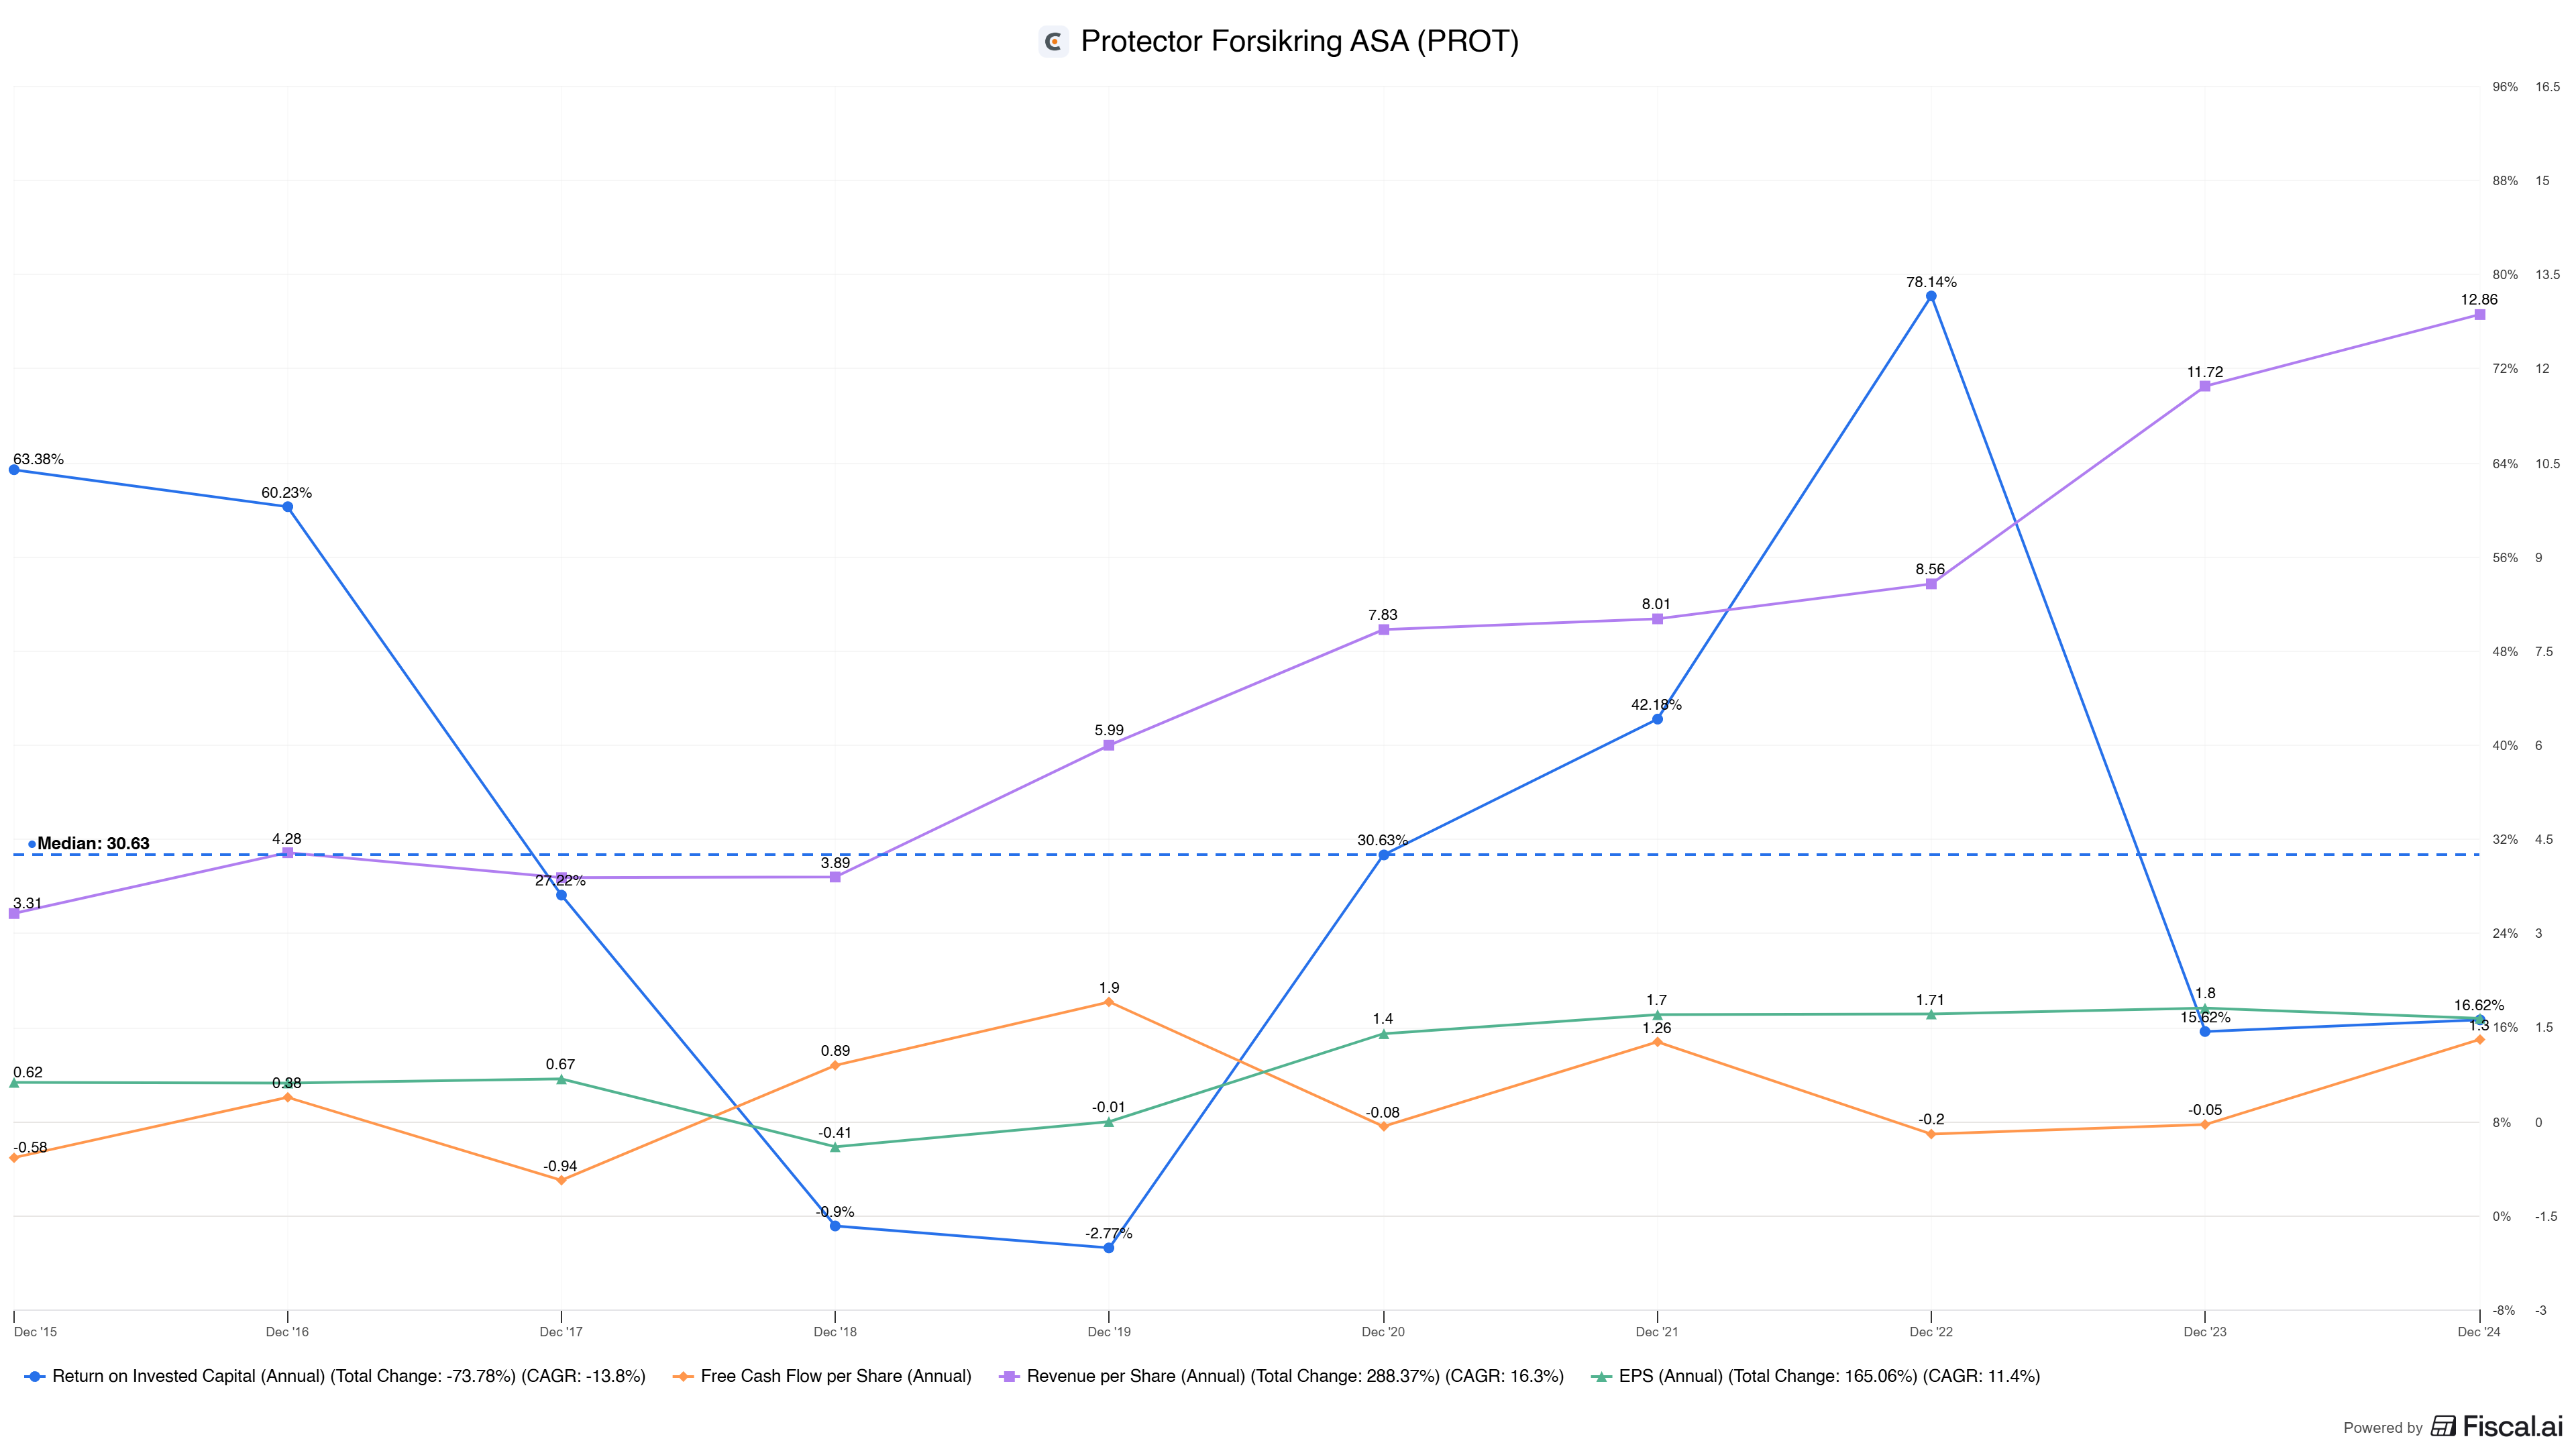
Management is creating value for its shareholders.
It’s not as flashy as the U.S. tech stocks you might be used to. But we’re seeing a median ROIC of 30%, increasing revenue per share, and increasing free cash flow per share (be it a bit cyclical).
As a shareholder, you’re getting more on a per-share basis. By allowing earnings and free cash flow to compound and be reinvested at a roughly 30% ROIC, Protector Forsikring is positioning itself for significant growth in both earnings and free cash flow.
3. Insider Ownership
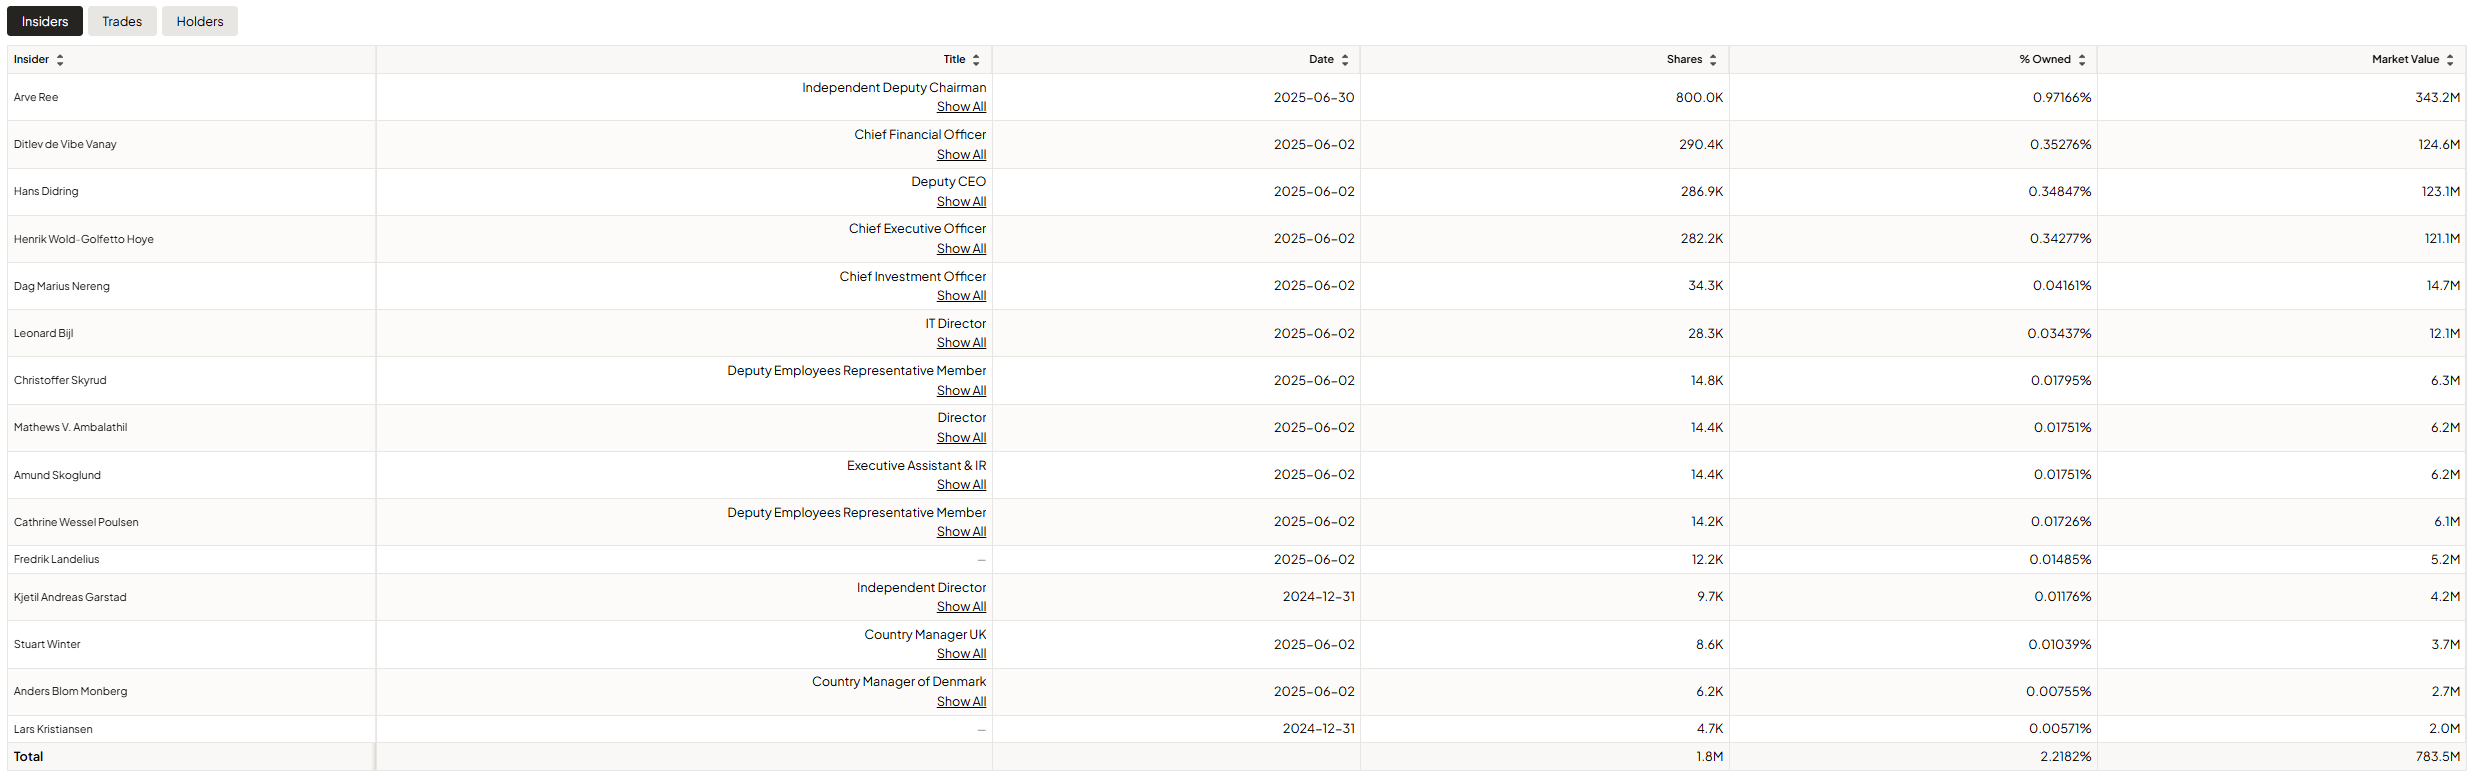
I hear you thinking ‘‘2.2% inside ownership isn’t that much, right?’’.
Well, it is decent. We prefer inside ownership to be equal to or larger than 3%. However, we also need to consider their salaries in comparison to this. I will not bore you with the top 10 their salaries, compensations, etc. However, most of them have at least five times their annual salary invested in the company's stocks.
That’s good!
We’re seeing decent insider ownership and significant skin in the game when comparing annual salaries to the amount of cash invested in stocks/options within the company.
👉 You're one step away from joining the Fluent Few, rational investors who don't just watch from the sidelines. Get full access to this investment case, future deep dives, and the private portfolio by upgrading today.
(upgrading via the website saves you money)
