

To all the Fluenteers and the Fluent Few, welcome back. 👋
Have you ever crossed paths with someone and followed them, only to smell something sweet, musky, sour, or any other scent? You probably have.
Most people around the globe enjoy this diverse palette of flavors and perfumes. Behind this smell is a company providing these people with their perfumes.
That company is Interparfums.
Today, we will go over Interparfums in great detail, and by the end, you will know everything you need to know, including whether now is the right time to buy Interparfums or not.
Thank you for joining me today. I’m forever grateful.
With that said, happy compounding! 😀
Table Of Contents
Corporate Analysis
1.1 Business Overview
1.2 Revenue BreakdownExecutive Leadership
2.1 CEO Experience
2.2 Employee Satisfaction Ratings
2.3 CEO Value CreationCompetitive and Sustainable Advantages (Economic Moat)
Industry Analysis
5.1 Industry Growth Prospects
5.2 Competitive BenchmarkingRisk Assessment
Financial Stability
7.1 Asset Evaluation
7.2 Liability AssessmentCapital Structure
8.1 Expense Analysis
8.2 Capital Efficiency ReviewProfitability Assessment
9.1 Profitability, Sustainability, and Margins
9.2 Cash Flow AnalysisGrowth Projections & Expect Annual Return
Value Proposition
11.1 Dividend Analysis
11.2 Share Repurchase Programs
11.3 Debt Reduction StrategiesQuality Rating & Checklist
Valuation Assessment
1. Corporate Analysis
1.1 Business Overview
Interparfums was founded in 1982 by Jean Madar, along with Philippe Benacin. The two started Interparfums right after business school. After learning about the high margin of this industry, they were sold on the idea directly. Not long after, in 1988, Jean and Philippe took Interparfums public at a valuation of $4 million. Interparfums now boasts a valuation of $3.3 billion.
Currently, Madar oversees Interparfums U.S. operations, and Philippe oversees Interparfums European operations. The U.S. is the largest source of revenue, followed by Europe in respectable second place.
So, what does Interparfums do exactly? They sell perfume. But don’t be fooled. Interparfums doesn’t just sell perfume. They sell the likes of:
Coach
Jimmy Choo
Montblanc
Lacoste
Rochas
Lanvin
Karl Lagerfeld
Moncler
And plenty of other brands.
You might wonder how they’re able to sell perfume from other brands? The most logical question I expected.
Interparfums licenses the intellectual property of brands such as Lacoste, Jimmy Choo, and many other notable brands. To put it simply, they sign an agreement stating that Interparfums can produce and distribute perfumes using the branding of the companies from which they acquired licenses. Here’s an overview of the process.
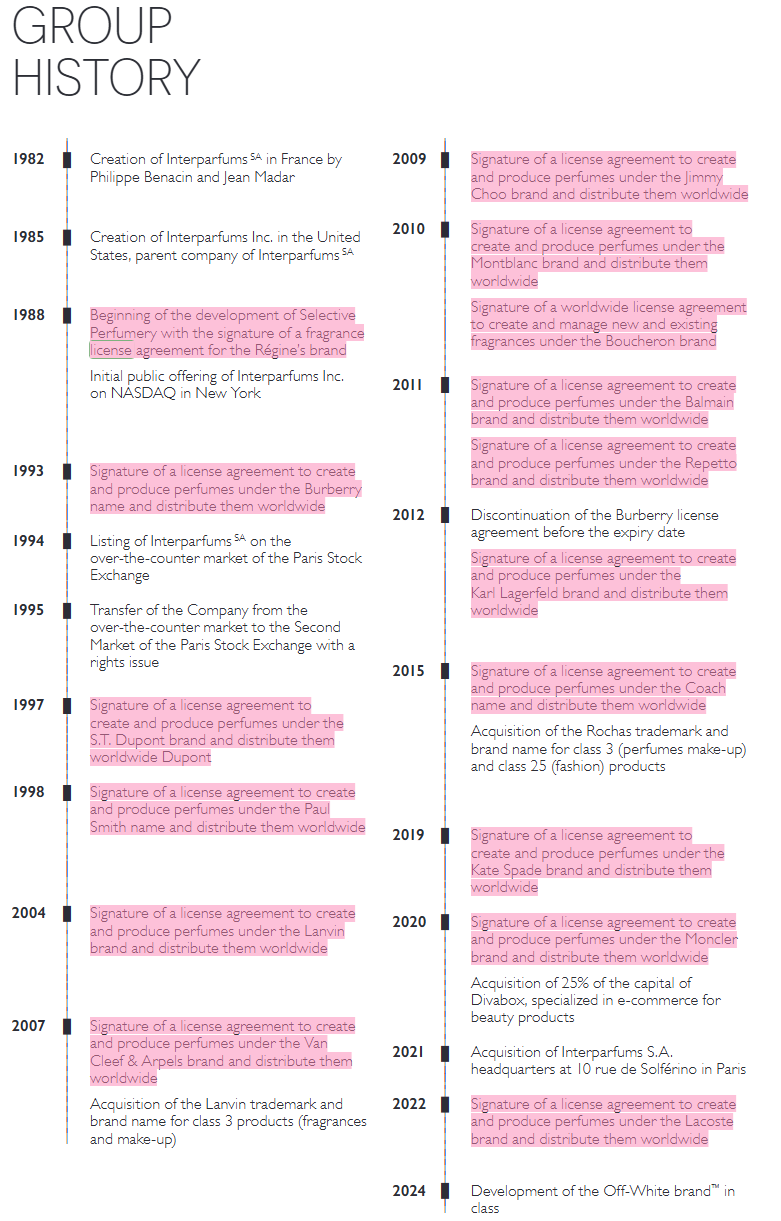
It’s a fantastic business model, in my opinion. They’re able to produce perfume, which tends to be moderately priced, and utilize the branding of well-known names to help boost their sales. These licenses stretch over an extended period of time.
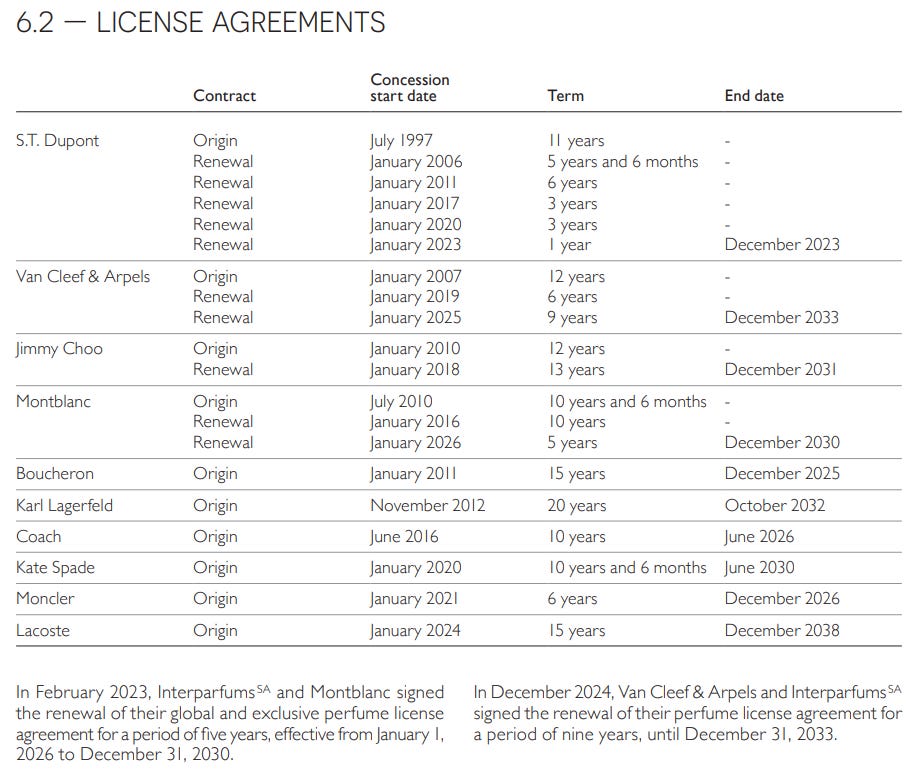
We’re clearly seeing long-term dedication from both parties. Other brands and Interparfums sign a substantial agreement. And the beauty of this all is that a significant number of brands tend to extend this partnership.
This isn’t only beneficial for Interparfums, but also for the other brands. Interparfum has specialized knowledge in producing and distributing perfumes globally, which benefits other brands. Moreover, brands like Karl, Lacoste, and Jimmy Choo do not need to carry the risks of producing perfumes, which tend to be a significant investment. Following these investments in these brands, the question remains whether these perfumes will resonate with perfume enthusiasts. Interparfumes takes away a considerable amount of risk by taking the whole process out of these brands ‘ hands.
Yes, Interparfum takes on risks. But Interparfumes specializes in this industry. For them, this kind of work is their day-to-day business.
Lastly, brands like Lacoste, Karl, Boucheron, etc, want to keep their focus on their primary goal, and Interparfum gives these brands the breathing room to do so by producing and distributing them themselves.
It’s a win-win for both the brand and Interparfums.
Of course, in return, Interparfum pays the companies from which it licenses a royalty, which is a % of their revenues. This is to be expected and only fair, since Interparfum is using its brands to produce perfumes.
In 2024, Interparfums paid €65.901 in royalties. To put this in perspective, their total sales for 2024 were €1.45 million. That means 4.54% of their total revenue will go to the brands in the form of royalties, this is doable.
If we look at the previous years, going back to 2021, we see that royalties have been somewhat stable as a percentage of total sales.
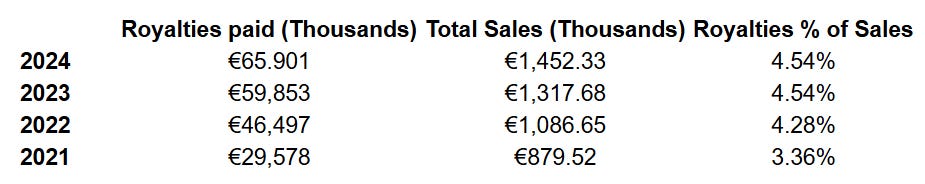
Carrying legacy brands, their branding to sell perfumes, and all that for a bit of royalty? Sounds like a solid business model to me.
Now that we understand how Interparfums' business operates, let’s examine its revenues.
1.2 Interparfums Revenue Breakdown
To join our investable universe, we prefer companies to be selling their products or services globally, as is the case with Interparfums. This is to ensure that there is limited concentration on one market, which could pose a danger if the economy/country faces headwinds. If a company is limited to, let’s say, France, and France is heading into a pit, the company and its revenues head in the same direction.
Therefore, we prefer companies that operate on a global scale. Interparfums ticks this box.
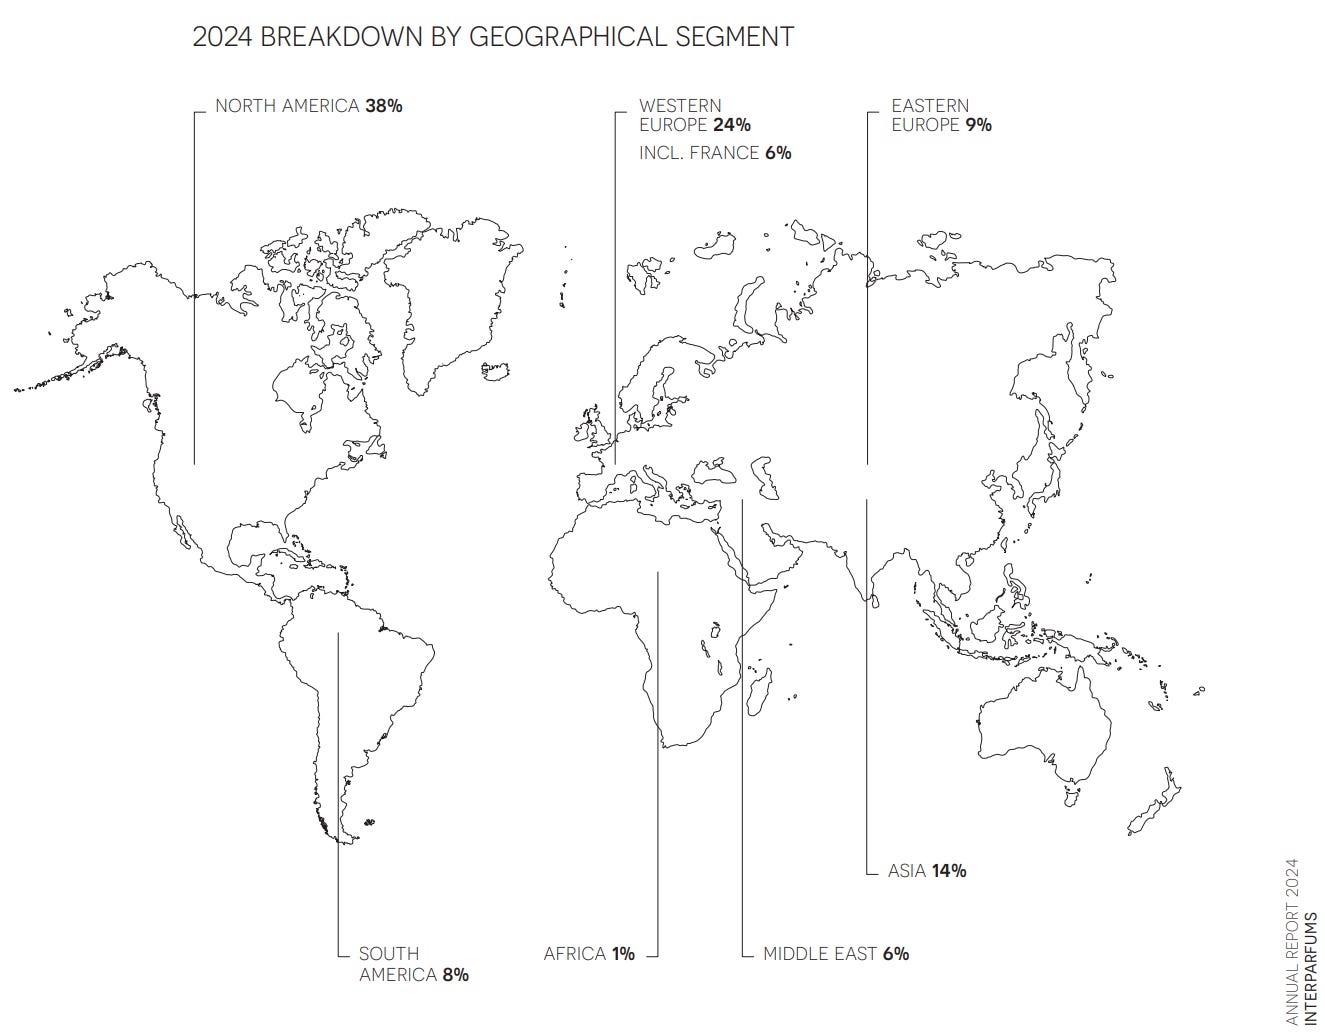
Some might argue that Interparfum remains highly active in North America, with 38% of total sales, and Western Europe, with 24%. But they are expanding operations in South America, Africa, the Middle East, Eastern Europe, and Asia. Asia, Eastern Europe, and South America are emerging as key regions for their operations.
In these regions, disposable income is growing, and the desire for beauty, including perfumes, has consistently been high among all groups. An increase in disposable income and the status/desire/prestige that consumers seek from products like perfumes will dramatically benefit Interparfums.
In the following graph, you will see a breakdown of global revenue by region.
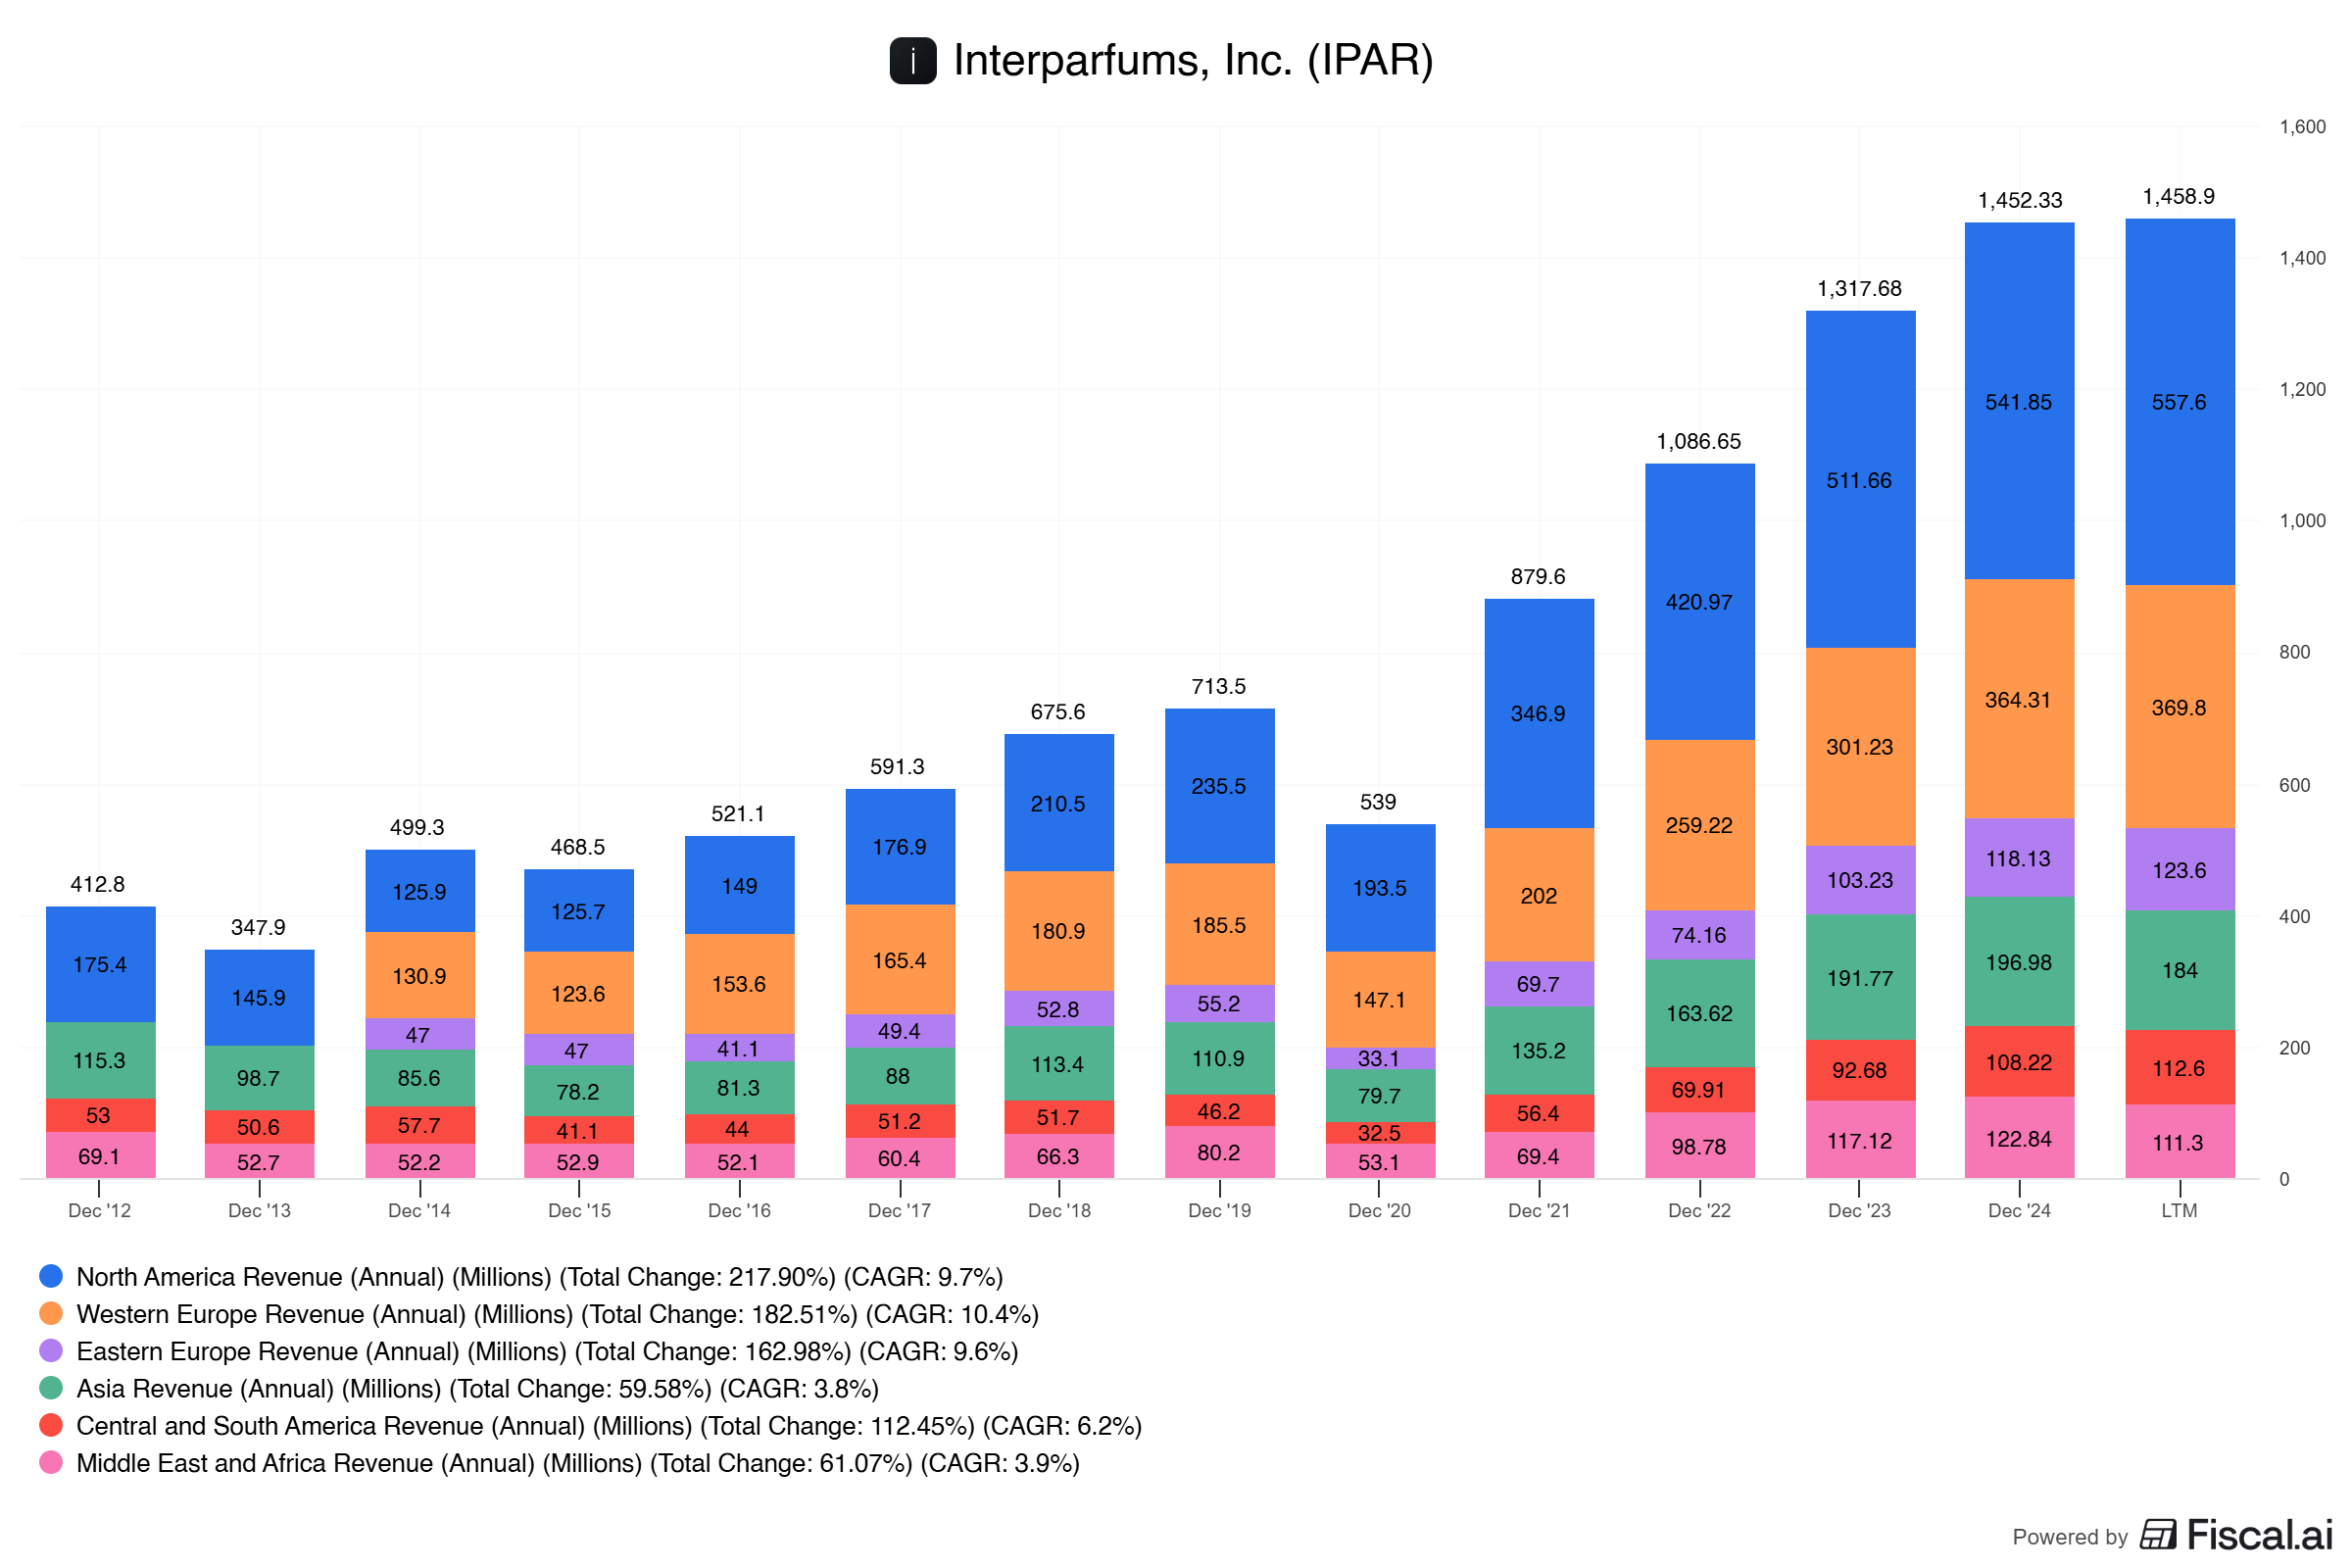
Overall, Interparfums is showing modest growth in all regions, including those that are more challenging to penetrate, such as Africa and the Middle East.
Nonetheless, since 2012, Interparfums has been compounding in most regions.
The next question we should ask ourselves is ‘‘What revenues are coming from what license/brand?’’ As some of you may know, global diversification is key, but also healthy diversification within the segments. In the Interparfums case, this is on a per-license/brand basis for the perfumes.
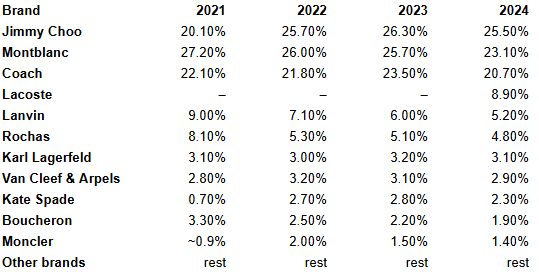
We’re clearly seeing a diversified portfolio of perfumes, all contributing to the total revenues. Jimmy Choo, Montblanc, and Coach carry Interparfums‘ portfolio in terms of revenue.
Lanvin has been experiencing a decline in its sales contribution. The same is said for Rochas. Other brands, such as Karl Lagerfeld, Kate Spade, Boucheron, and Moncler, are experiencing an overall uptrend in their contribution to Interparfums' total sales.
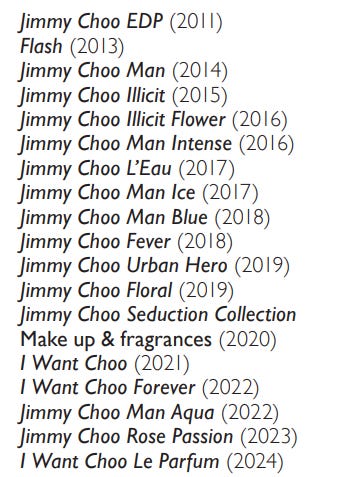
Brand awareness is one contributing factor to this gap between the top contributors and the detractors in the portfolio. If we look at the product on the market for Jimmy Choo, we have the following list:
Now, if we move on to another active contributor to Interparfums' sales, the same pattern can be observed.
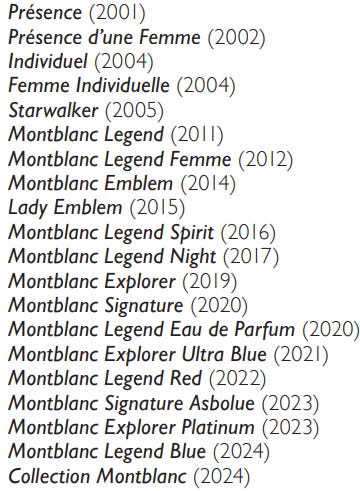
The top contributors, in general, have a wider portfolio of products available on the market. In addition to this, these brands have been partnered with Interparfums for an extended period, allowing their brand to gain more time to ‘marinate’ with consumers.
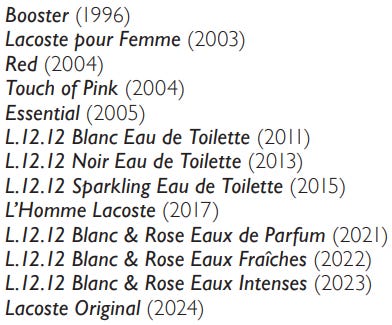
Lacoste is the latest addition to their portfolio of partners. Already managing a significant portfolio of perfumes, I’m confident that Lacoste will be another key growth driver for Interparfums. Lacoste is a well-known brand that sponsors athletes and other public figures, providing free promotion for the perfumes offered by Interparfums. Since their partnership started this year, Lacoste has already contributed 8.90% of the total sales, which is a good start for both Lacoste and Interparfums.
This, in return, will most likely result in a long and enduring partnership between these two. And this is also the case with other partners. Jimmy Choo, Montblanc, and Coach are receiving substantial royalties, and their perfumes continue to compound. The most logical step for one of these is to continue their partnership and let the revenue compound for decades to come.
Here’s a list of the licensed perfumes by Interparfums from Lacoste.
2. Executive Leadership
2.1 CEO Experience
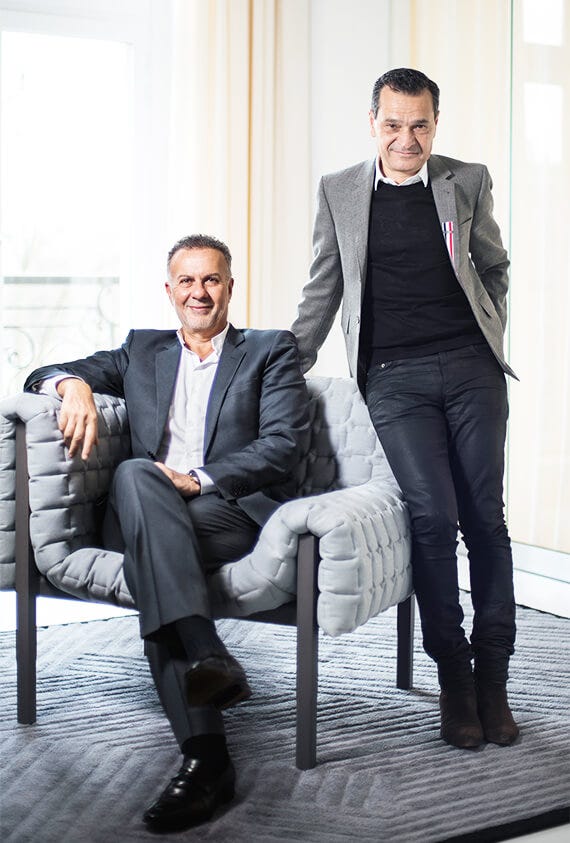
Two longtime partners and friends built up Interparfums Inc..
Interparfums was founded in 1982 in France by Philippe Benacin and Jean Madar. Benacin and Madar combined their complementary skills to build a business model centered on licensing and developing fragrances for established fashion and luxury brands. In 1985, they created Interparfums, Inc. in the United States as the parent company of Interparfums SA.
The company experienced steady growth throughout the late 1980s and early 1990s. In 1988, Interparfums entered the selective perfumery segment by signing its first fragrance license agreement for the Régine’s brand. That same year, Interparfums, Inc. completed its initial public offering on NASDAQ in New York. In 1993, the company signed a significant licensing agreement to create and distribute Burberry perfumes worldwide. The following year, Interparfums SA was listed on the Paris Stock Exchange.
During the late 1990s and 2000s, Interparfums continued to build its portfolio. It signed license agreements with S.T. Dupont in 1997, Paul Smith in 1998, Lanvin in 2004, and Van Cleef & Arpels in 2007. The Van Cleef & Arpels fragrance license was later renewed in 2019 and again in 2025, extending the partnership through December 2033.
The company entered a new phase of expansion in the late 2000s and 2010s with a series of high-profile brand agreements. In 2009, Interparfums signed with Jimmy Choo (later renewed in 2018 through December 2031), followed in 2010 by Montblanc (renewed in 2023 through December 2030) and Boucheron (set to run until December 2025). In 2011, the company added Balmain and Repetto, and in 2012, it initiated a long-term partnership with Karl Lagerfeld, which included a license valid until October 2032.
After the discontinuation of the Burberry license in 2012, Interparfums strengthened its portfolio with other global names. In 2015, it signed a 10-year agreement with Coach (expiring June 2026), and in 2019, with Kate Spade (valid until June 2030). In 2020, it added Moncler with a six-year deal (through December 2026). The most recent additions include Lacoste, which was acquired in 2024, with a 15-year license agreement running until December 2038.
Through this steady progression, Jean Madar and Philippe Benacin transformed Interparfums from a small French startup into a dual-listed global fragrance house. Today, the company manages licenses for major brands, including Montblanc, Jimmy Choo, Coach, Van Cleef & Arpels, Karl Lagerfeld, Kate Spade, Moncler, Boucheron, and Lacoste. The license durations, often ranging between six and twenty years, secure long-term revenue streams and reinforce the founders’ original vision of building a transatlantic fragrance powerhouse.
This story is one I admire because of its simplicity: two entrepreneurs had an idea, started it, and are devoted to making it work, no matter what.
Jean Madar and Philippe Benacin both hold a significant stake in Interparfums. According to the latest filings, Jean Madar holds approximately 22% of the total outstanding shares, while Philippe Benacin holds approximately 21% of the total outstanding shares.
That’s a whopping 43% of inside ownership by the co-founders alone.
Some independent directors also hold shares in Interparfums, but this is not a significant holding.
2.2 Employee Satisfaction Ratings
Inter Parfums' employee ratings are mixed, with an overall rating of 3.1 out of 5 stars on Glassdoor based on 66 reviews. While only 40% of employees would recommend working there to a friend, Indeed shows slightly more positive scores, with users rating aspects like pay and benefits higher. Other platforms, such as Comparably, present a less favorable outlook on the company's overall culture.
Key Ratings and Trends
Overall Rating (Glassdoor): 3.1 out of 5 stars.
Recommend to a Friend (Glassdoor): 40%.
Business Outlook (Glassdoor): 49% of employees have a positive outlook on the company.
Ratings by Category
Indeed:
Pay and Benefits: 4.3 out of 5.
Work-Life Balance: 4.1 out of 5.
Management: 3.7 out of 5.
Culture: 3.7 out of 5.
Job Security and Advancement: 3.0 out of 5.
Glassdoor:
Employees rate compensation and benefits favorably, although specific ratings vary by location and company version. For Interparfums (France), for example, compensation and benefits received a rating of 4.0 out of 5.
Interparfums is offering a healthy workplace for employees, which is a must for our investable universe. We should, and do, demand that companies have employees who are truly aligned with the company's long-term goals. In addition to this, this comes at a cost of modest salaries and excellent contracts for the employees, but this, in return, has a significant ROI for the company.
Improving the environment for your employees has been proven to result in lower burnout rates, reduced sick leave, lower departure rates, and increased productivity within the company. This, in turn, makes operations smoother for the company and saves the company significant cash.
You want to keep the best, provide the best, and you will become the best. It’s all about creating a healthy environment, providing support, offering adequate compensation, and fostering long-term partnerships with your employees.
2.3 CEO Value Creation
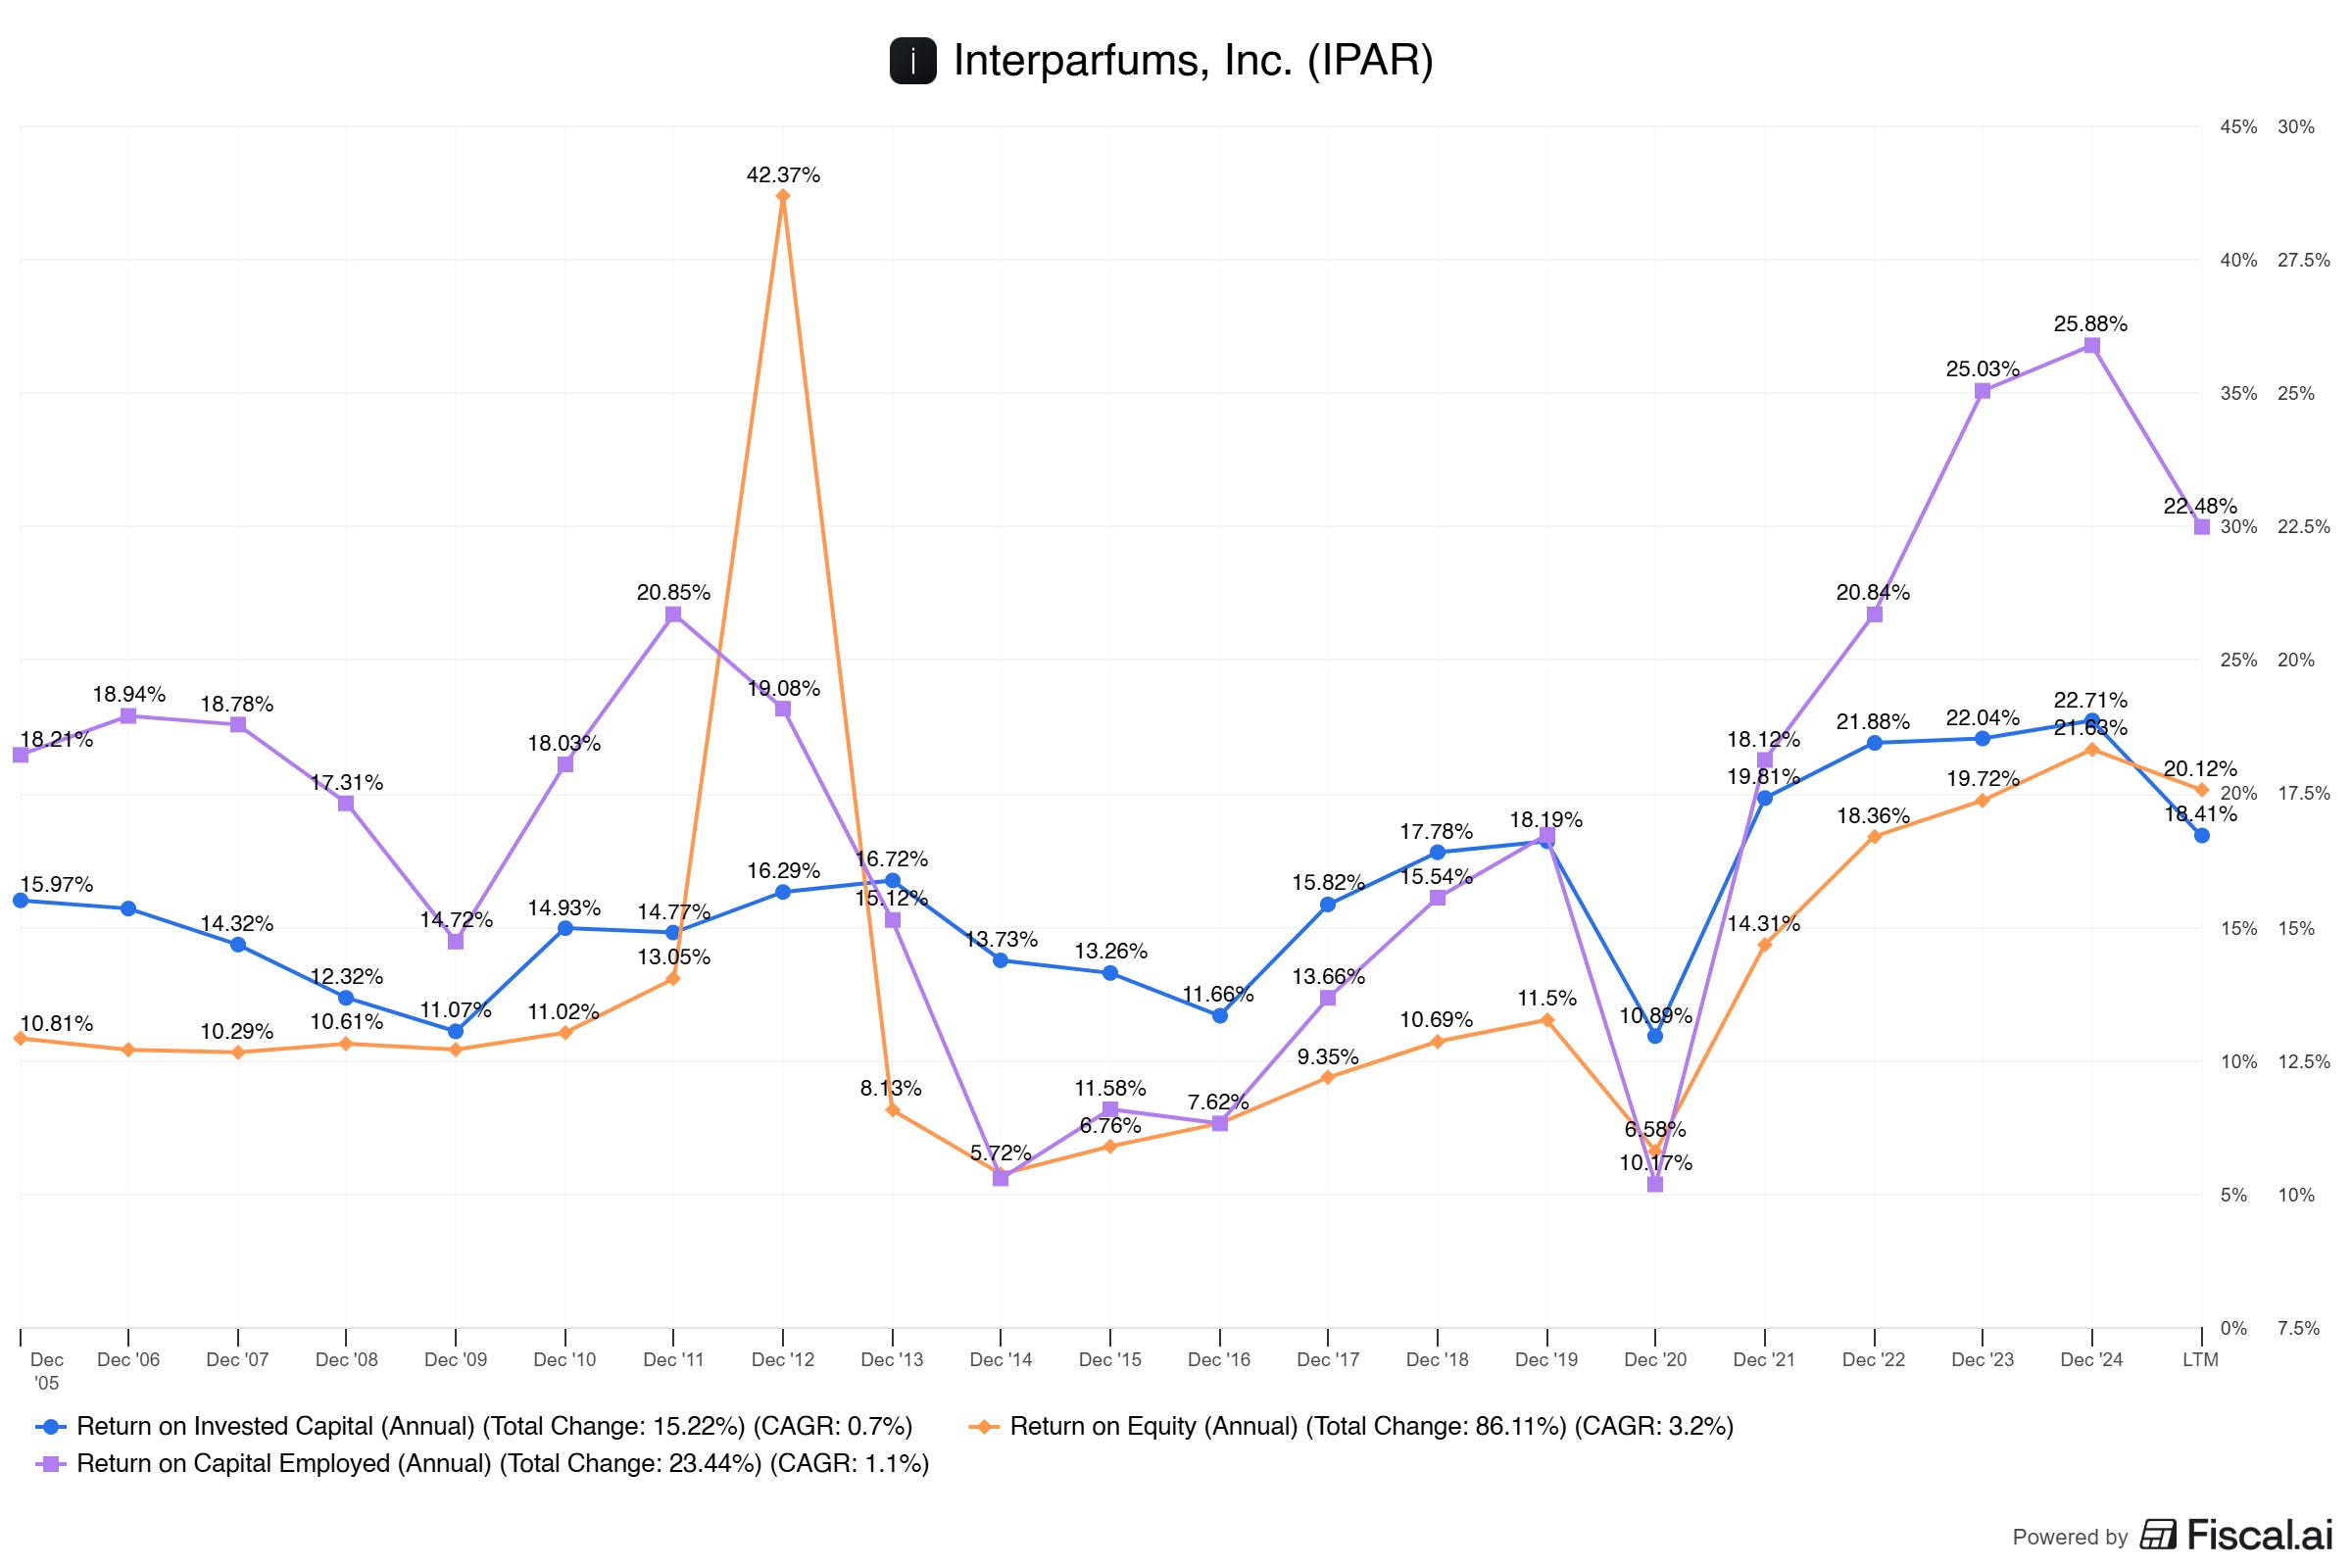
Let's examine Interparfums' Return on Invested Capital (ROIC), Return on Equity (ROE), and Return on Capital Employed (ROCE). We see that management, for the most part, has been creating significant value.
Yes, all metrics have shown significant volatility from 2009 to 2012 and again in 2020; however, if we look at the median over this time period, Interparfums has an excellent score.
ROCE 20-year median: 18.3%
ROIC 20-year median: 15.82%
ROE 20-year median: 10.69%
These types of returns make Interparfums attractive to us, quality investors.
Yes, management is creating value for Interparfums and its shareholders.
Now we’ll be covering a crucial part of Interparfums, their economic moat.
The next section is reserved for the inner circle, the Fluent Few. 🔒
By joining today, you unlock:
(Bi-)weekly deep dives into high-quality, high-potential small caps
My full personal portfolio with every buy & sell explained
Private community access + “Best Buys” alerts
Right now, you can join for only $34.99/month or $340/year.
👉 Go yearly and save $79.88 compared to monthly.(For context: my original pricing is $44.99/month and $440/year — this is your chance to lock in a much lower rate for life.)
Important: If you’re on iOS or Android, subscribe via the website. App stores charge a 30% fee, which makes it more expensive for you. The website saves you real money.
Join the Fluent Few today and start compounding with conviction.
