

Fluenteers, welcome back! And a special salute to the Fluent Few — our inner circle of long-term compounders and partners. 👋🏻
I was browsing Substack and other forums in search of another small-cap to add to my investable universe.
After some doomscrolling and filtering out the noise, I came across this company, EverQuote. My interest was piqued, to say the least.
I’ll be sharing everything you need to know in this article.
I’ll also add my personal bullish and bearish theses to this and future investment cases. This is to ensure I add more nuance and give you a clear sense of both the bullish and bearish sides of the story.
A coin has two sides. Every bullish thesis comes with a bearish thesis.
Moreover, I’ve listened to all your advice, needs, and recommendations. Therefore, a technical analysis component will be included in the valuation going forward.
A triple whammy!
Grab a coffee, a pen, and a piece of paper, and take notes as we ride along.
Happy compounding! 😀
Table Of Contents
Corporate Analysis
Business Overview
Revenue Breakdown
Executive Leadership
CEO Experience
Employee Satisfaction Ratings
Management Value Creation
Competitive and Sustainable Advantages (Economic Moat)
Industry Analysis
Industry Growth Prospects
Competitive Benchmarking
Risk Assessment
Financial Stability
Asset Evaluation
Liability Assessment
Capital Structure
Expense Analysis
Capital Efficiency Review
Profitability Assessment
Profitability, Sustainability, and Margins
Cash Flow Analysis
Growth Projections & Expect Annual Return
Value Proposition
Dividend Analysis
Share Repurchase Programs
Debt Reduction Strategies
Bullish Thesis
Bearish Thesis
Quality Rating & Checklist
Valuation Assessment
Technical Analysis
1. Corporate Analysis
A) Business Overview
EverQuote offers an online platform where consumers can enter their information and find a suitable insurance plan for their car or property (for both renters and homeowners). EverQuote itself does not cover the consumer; it links the consumer to an agent or carrier for the actual insurance. EverQuote is a middleman.
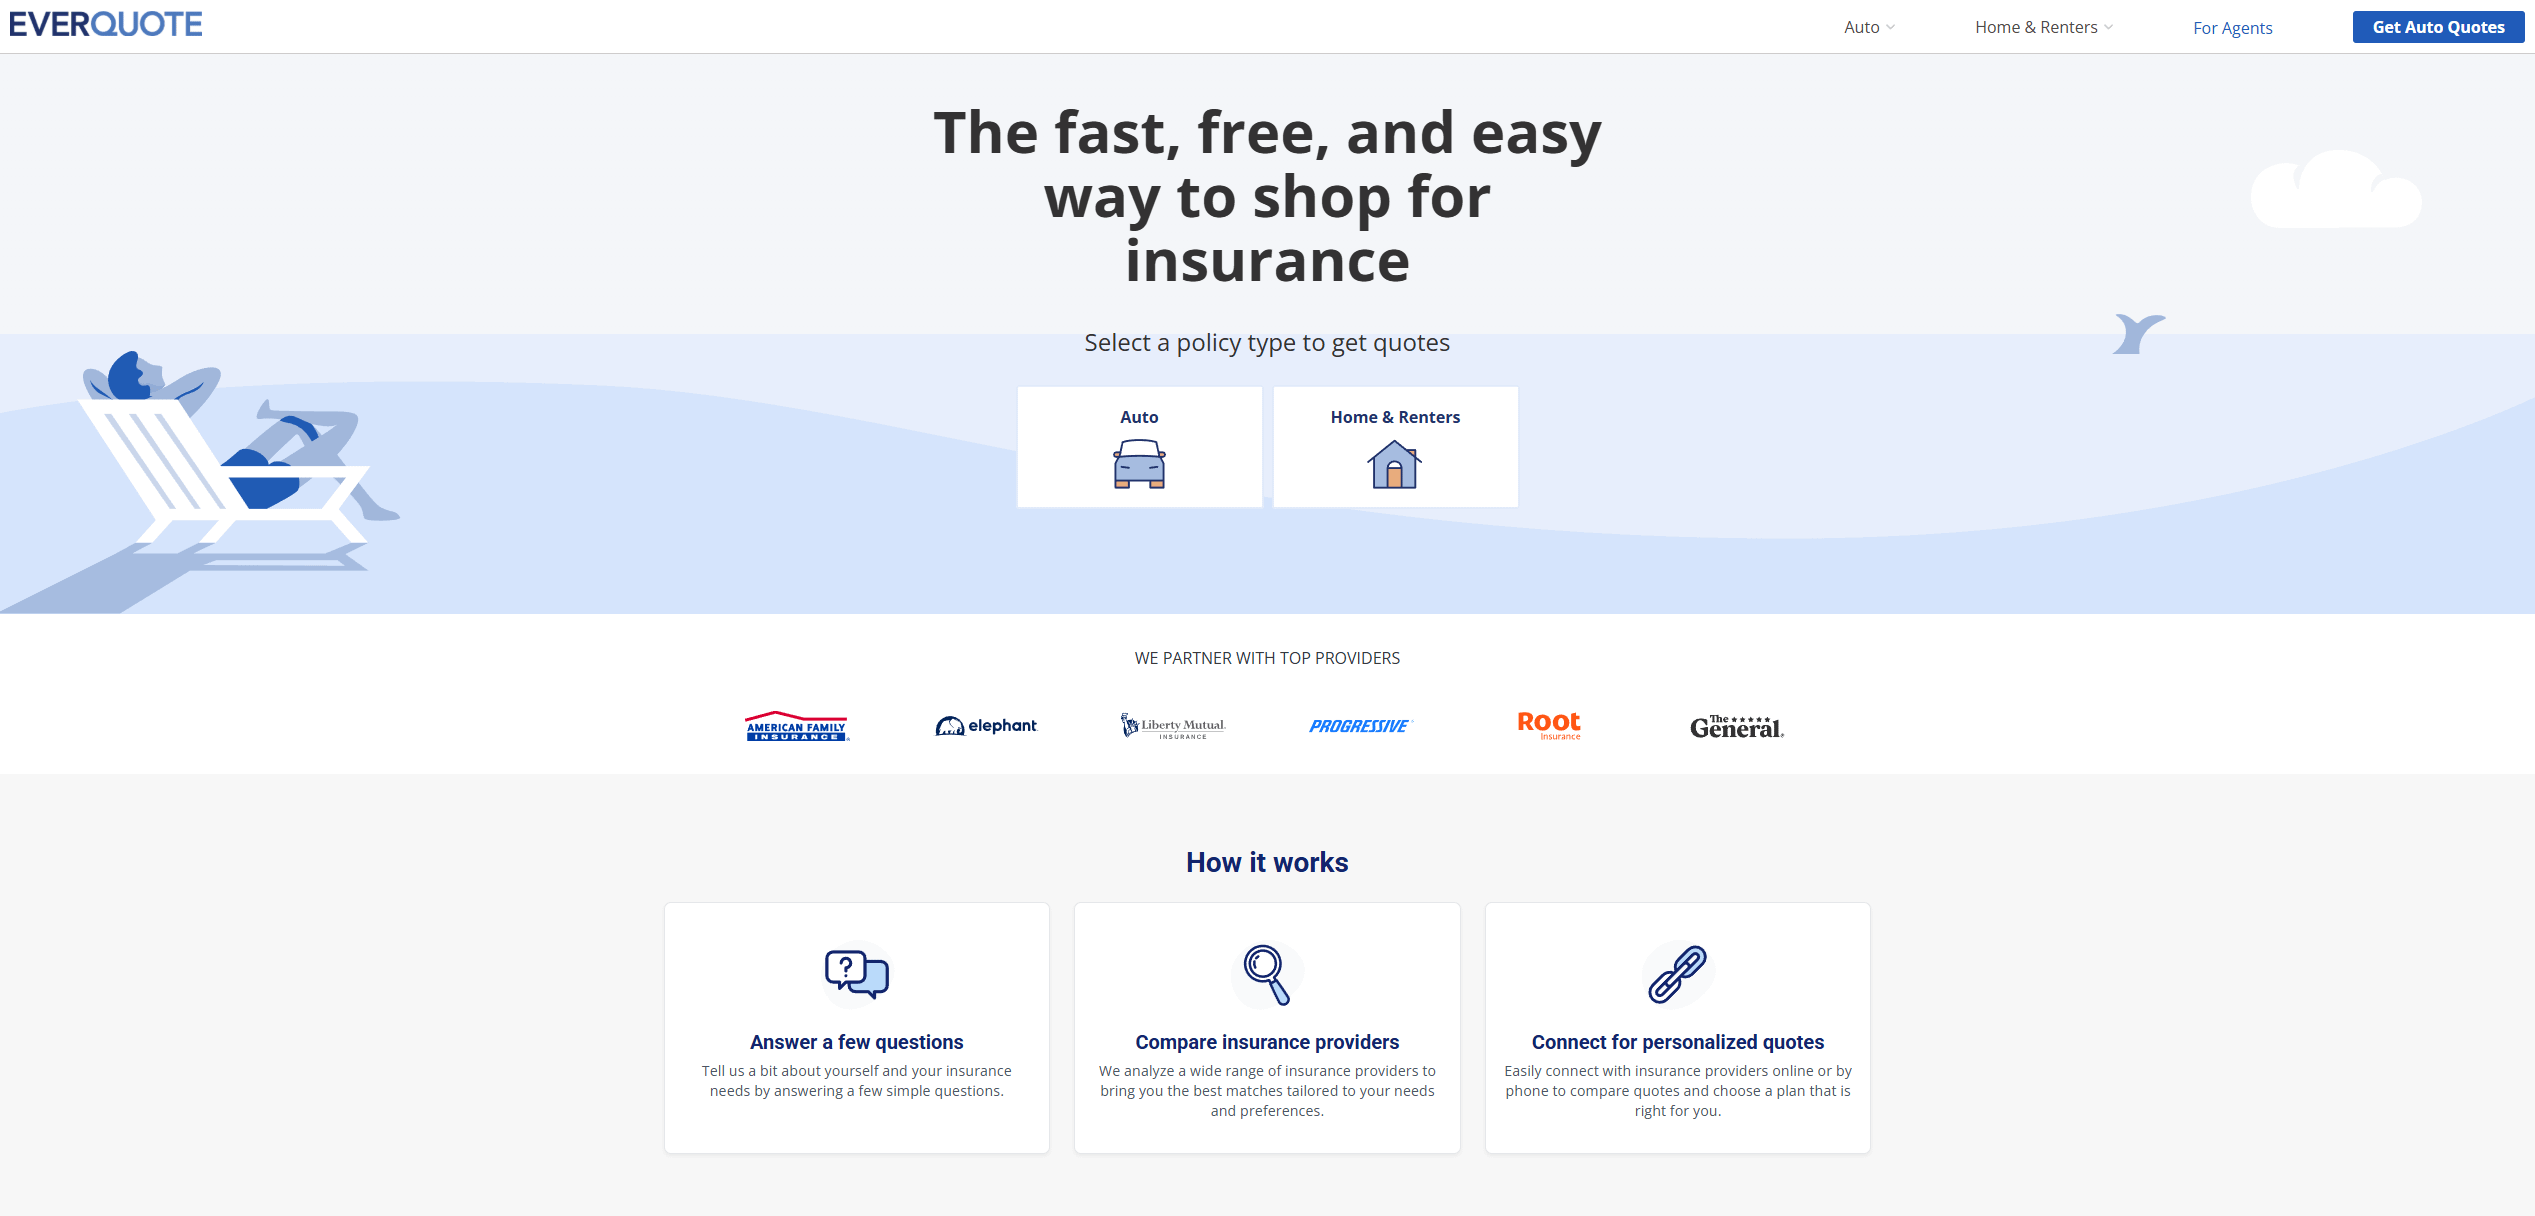
As you can see from the photo, EverQuote asks you a few questions, compares insurance providers, and helps you connect with the right agent or carrier to choose a plan that fits your needs.
It’s as easy as that.
Quick backstory on why and how EverQuote was founded to give you some more insights into the business.
EverQuote was founded by Seth Birnbaum, Tomas Revesz, and David Blundin. They started the company (originally as AdHarmonics) in 2008, evolving it into the online insurance marketplace EverQuote by 2011, with Birnbaum serving as the visionary CEO until his passing in 2020.
Their mission is, according to multiple press releases, to ‘‘transform the complex, often frustrating, insurance shopping experience by using a data-driven, scientific approach to match consumers with the best insurance options, saving them time and money.’’
B) EverQuote Revenue Breakdown
Let’s talk about the numbers, shall we?
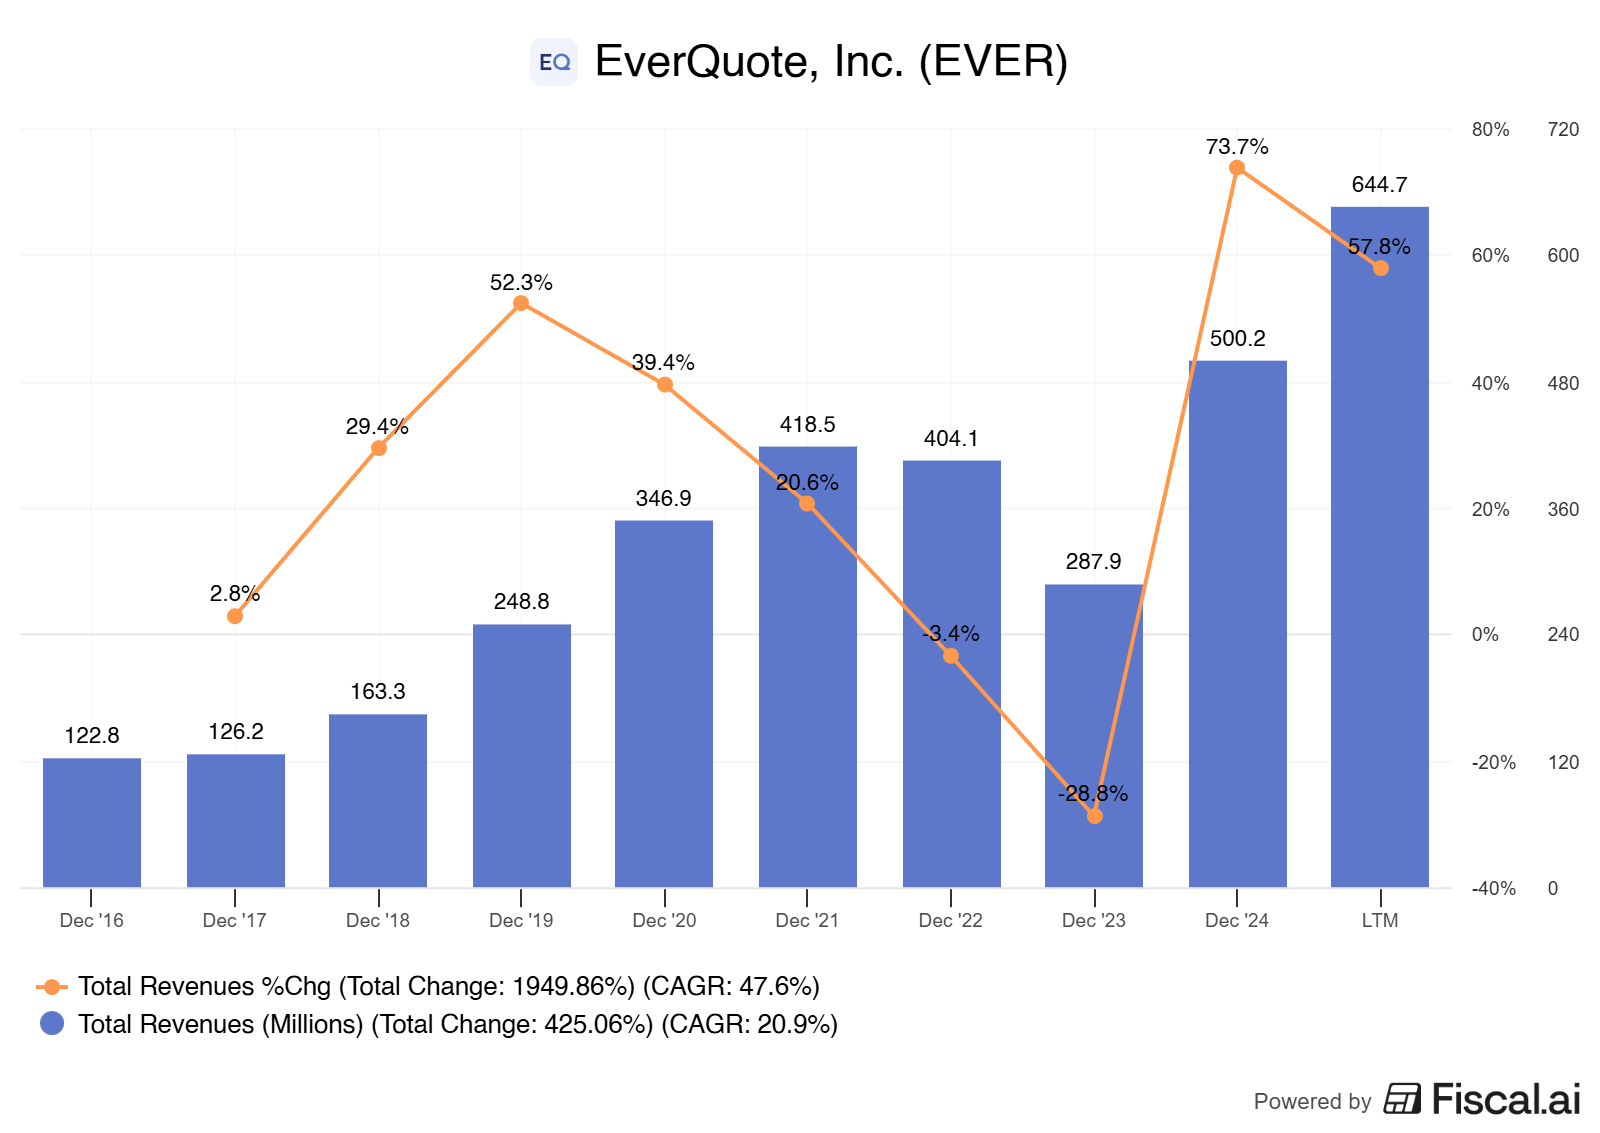
EverQuote has seen substantial growth in its total sales since 2016. We’re seeing a 20% CAGR in their sales, even with the decline from 2021 to 2023. This dip in revenue was due to an industry-wide pullback in the carrier marketing spend, particularly in auto (their primary revenue segment, more on this later), and EverQuote’s exit from their health insurance DTC segment.
A positive side note is that the headwinds were clearly cyclical, not structural.
On average, EverQuote has grown its sales by ~27% since 2016, which is impressive to say the least. We do see a slight ‘‘decline’’ in year-over-year revenue growth in the latest year, but this shouldn’t be of any worry in my humble opinion. When companies grow their sales, the law of large numbers slowly starts creeping up, suppressing the year-over-year revenue growth.
For now, all I see is a middleman growing its sales at significant rates without fail.
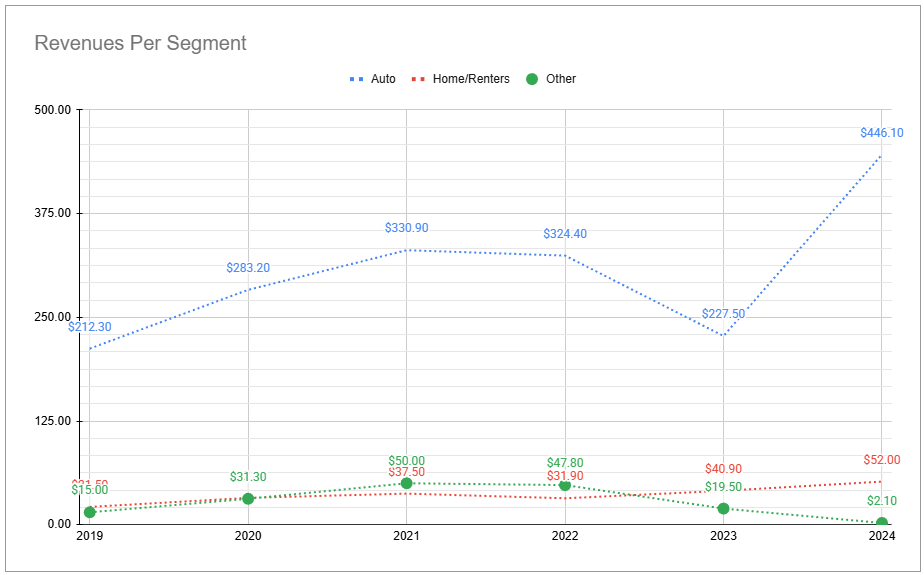
If we take a closer look at how revenues are made up, we clearly see EverQuote’s primary revenue driver.
EverQuote primarily gets its revenues from linking consumers who are looking for car insurance, such as:
liability insurance
collision insurance
comprehensive insurance
uninsured motorist insurance
personal injury insurance
rental reimbursement insurance
To the right agent or carrier.
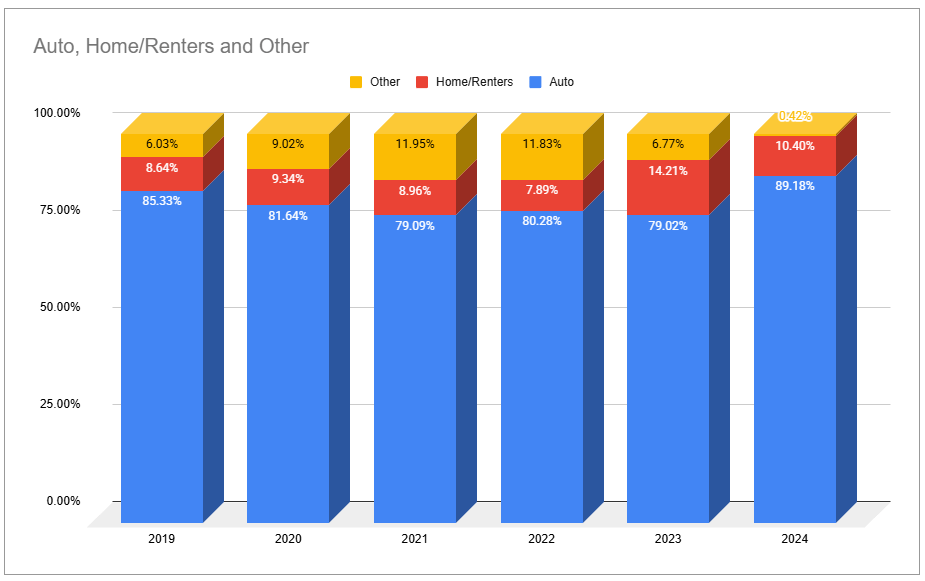
As shown here, their auto segment has consistently accounted for more than ~76% of their sales.
I do see a significant risk here, as we’ve seen with their headwind in 2021 that lasted until 2023. There was a considerable slowdown in the auto segment, directly impacting their top and bottom lines. There’s a significant dependence on their auto segment, which should be on any investor's mind.
Dependence creates weakness.
After their ‘‘auto’’ segment, we see that their ‘‘home/renters’’ segment takes the honorable 2nd place. This segment has been somewhat stable as a % of total sales, as shown above. After this, we see ‘‘other’’. Other revenue consists of life, health, and other insurance verticals. The health insurance vertical was exited on June 30th, 2024, resulting in a significant decline across revenue segments. Since they’ve exited this segment almost completely, we’ll avoid discussing it further.
When we’re analyzing a company’s revenue, we ideally would like to see a diversified portfolio of services or products with limited dependence on any single service or product.
This is not the case for EverQuote.
EverQuote is highly dependent on its ‘‘auto’’ segment. Their ‘‘home/renter’’ segment has seen growth from 2019 up until 2023, from 2023 to the latest twelve months, we see that even this segment is showing a decrease in % of total sales. This decrease isn’t because the sales of the home/renter segment are decreasing; their auto segment is growing at a more substantial rate.
(their home/renter segments grew from $40.9M in 2023 to $52.0M LTM, marking a 27.14% YoY growth, while their auto segment grew from $227.5 in 2023 to $446.10 LTM, marking a 96.09% YoY growth).
So, yes, there are some worries here about their dependence on the auto segment. We’ve seen the drastic impact a slowdown can have; we would not like to see a repetition of this headwind.
Usually, I made a geographic breakdown as well, but EverQuote solely operates in the U.S., which created another sore we should monitor.
Diversification in revenue applies geographically as well. Being tied up in one country brings another bag of risks as well. If the U.S. economy slows down while others prosper, or if the U.S. faces headwinds, EverQuote is again highly concentrated. I do, however, deem this ‘‘risk’’ less of a sore than the revenue part.
2. Executive Leadership
A) CEO Experience
Meet Jayme Mendal, the current CEO of EverQuote.
Jayme Mendal became Chief Revenue Officer at EverQuote in 2017. After only 1 and a half years in this position, Jayme became the Chief Operating Officer at EverQuote. After fulfilling this role, Jayme became the CEO of EverQuote.
Before joining EverQuote, Jayme held mostly marketing-related positions at PowerAdvocate (acquired by Verisk) from 2013 to 2018 and at Monitor Deloitte (formerly Monitor Group) from 2007 to 2010. Before that, he worked as an investment banking analyst at Citigroup in 2006, for just the summer.
What I do notice is the short tenures with the companies he’s worked for and the odd shift from niche marketing positions to revenue officer, ultimately becoming the ceo.
EverQuote had the following to say on his promotion to CEO:
“Over the last 3 years, Jayme has led the team to execute against our long-term growth model and has demonstrated a strong compass on strategic direction for traffic, product, distribution, and innovation. Jayme has hired, developed, and scaled EverQuote teams, building support, respect, and commitment throughout the organization. Above all, he has consistently demonstrated tenacity, heart, and ownership, and has truly defined what it means to bootstrap innovation at scale."
Jayme Mendal currently owns ~31K EverQuote shares worth roughly $830K. While it might sound impressive, it is not.
Jayme took home a salary of $375,000 in 2023, with an additional bonus of $1,400,000. Additionally, she received $948,600 in stock awards and $1,329,600 in option awards. Lastly, he took home $70,313 in non-equity incentive plan compensation.
Adding in all other compensation of $4,751, we get a total of $4,128,264 in compensation per the 2025 reported proxy statement.
For fiscal year 2024, it looked as follows.
A salary of $565,000 with a bonus of $107,272 (proxy notes a special one-time cash bonus program for 2024). Some stock awards (grant-date value) of $4,181,765 and non-equity incentive plan compensation: $847,500—all other compensation came down to $24,366.
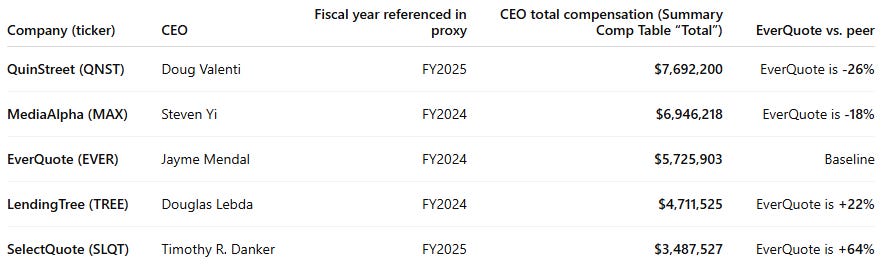
Total compensation comes down to $5,725,900.
So, I would argue that Jayme has limited skin in the game.
I would say a CEO has skin in the game once he has 5x his annual salary (not total compensation) locked in stock in the company. This is to ensure that his actions and the consequences are felt by himself as well.
With this salary, I doubt he would feel any actual pain.
How’s his salary compared to competitors? Here’s an overview. Jayme sits in the middle. So, although his compensation is significant, it’s modest compared to that of its competitors.
B) Employee Satisfaction Ratings
As many of you know, I’m a fan of a company that has (ex) employees boasting about working at the company.
By having satisfied employees, the company ensures fewer sick days, longer tenure, and employees who contribute significantly to the company's success. And this isn’t just ‘‘personal preference’’, this is based on facts, here’s just one example from this Oxford Study.
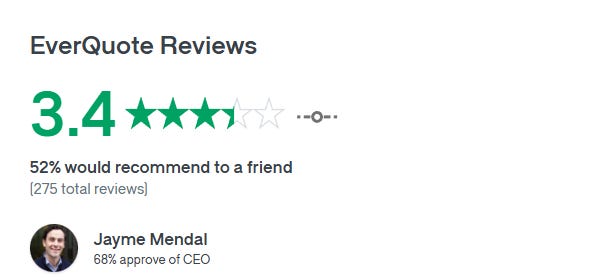
On first glance, it looks decent! To get a better understanding, let’s dive into the most recent reviews left by (ex)employees.


The overall culture seems to be alright, according to the reviews. A recurring theme is management and its approach to the employees. Moreover, I’ve seen a significant amount of negative reviews on their onboarding process. I can, however, somewhat understand the latter. It’s a relatively young company, which logically might experience some hiccups in its early years.
However, management is a point of feedback that, no matter the age, should be in check from day one. Hiccups are understandable, but not at this rate.
However, I’m somewhat positive about the reviews. Yes, there are some hiccups here and there, but it’s up to us to keep track of these hiccups to monitor if these are temporary or permanent.
I’ll keep this in the back of my mind.
C) Management Value Creation
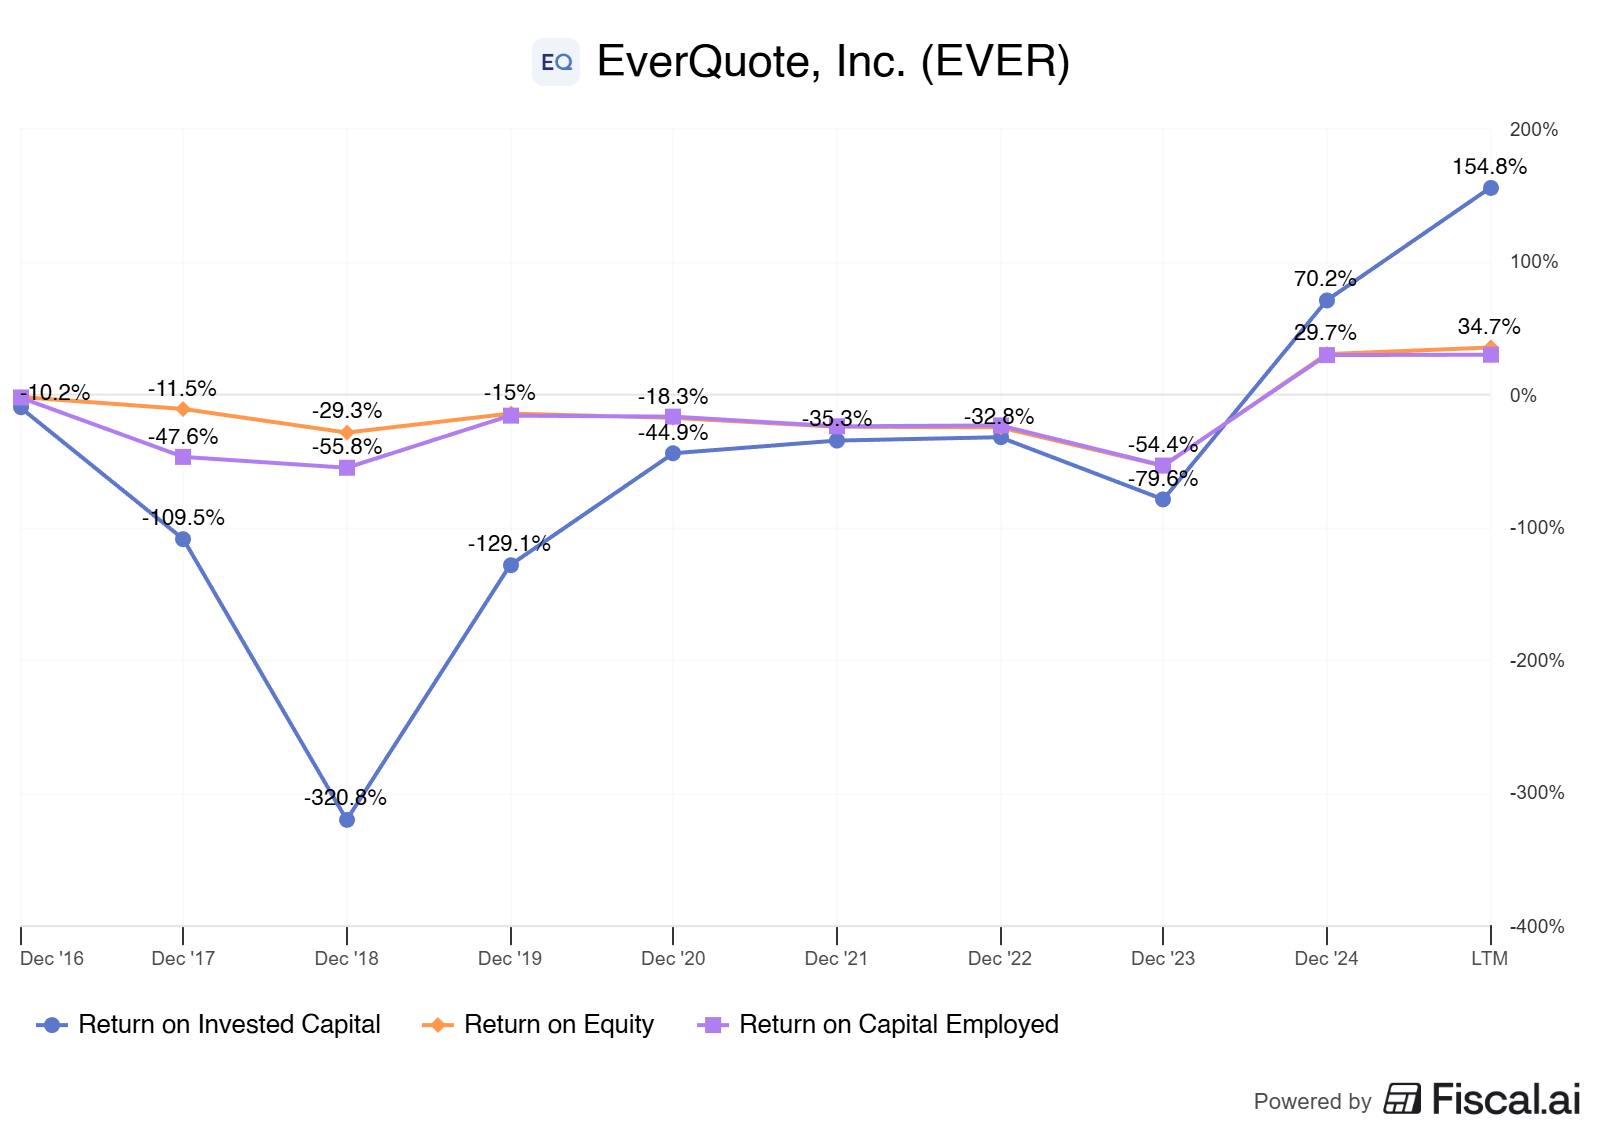
Keep in the back of your mind that EverQuote became profitable in March 2024. Therefore, their return on invested capital (ROIC), return on equity (ROE), and return on capital employed (ROCE) have been negative before 2024, it’s more noise than an accurate representation.
We do see, however, that after becoming profitable in FY24, EverQuote's ROIC, ROE, and ROCE shot up. It’s tough to give the conclusion right now that this is a trajectory that will continue. It’s even tougher to say at what levels these metrics will stabilize, so we can make our assumption based on these returns.
It’s a good start to see significant improvement in value creation here by management.
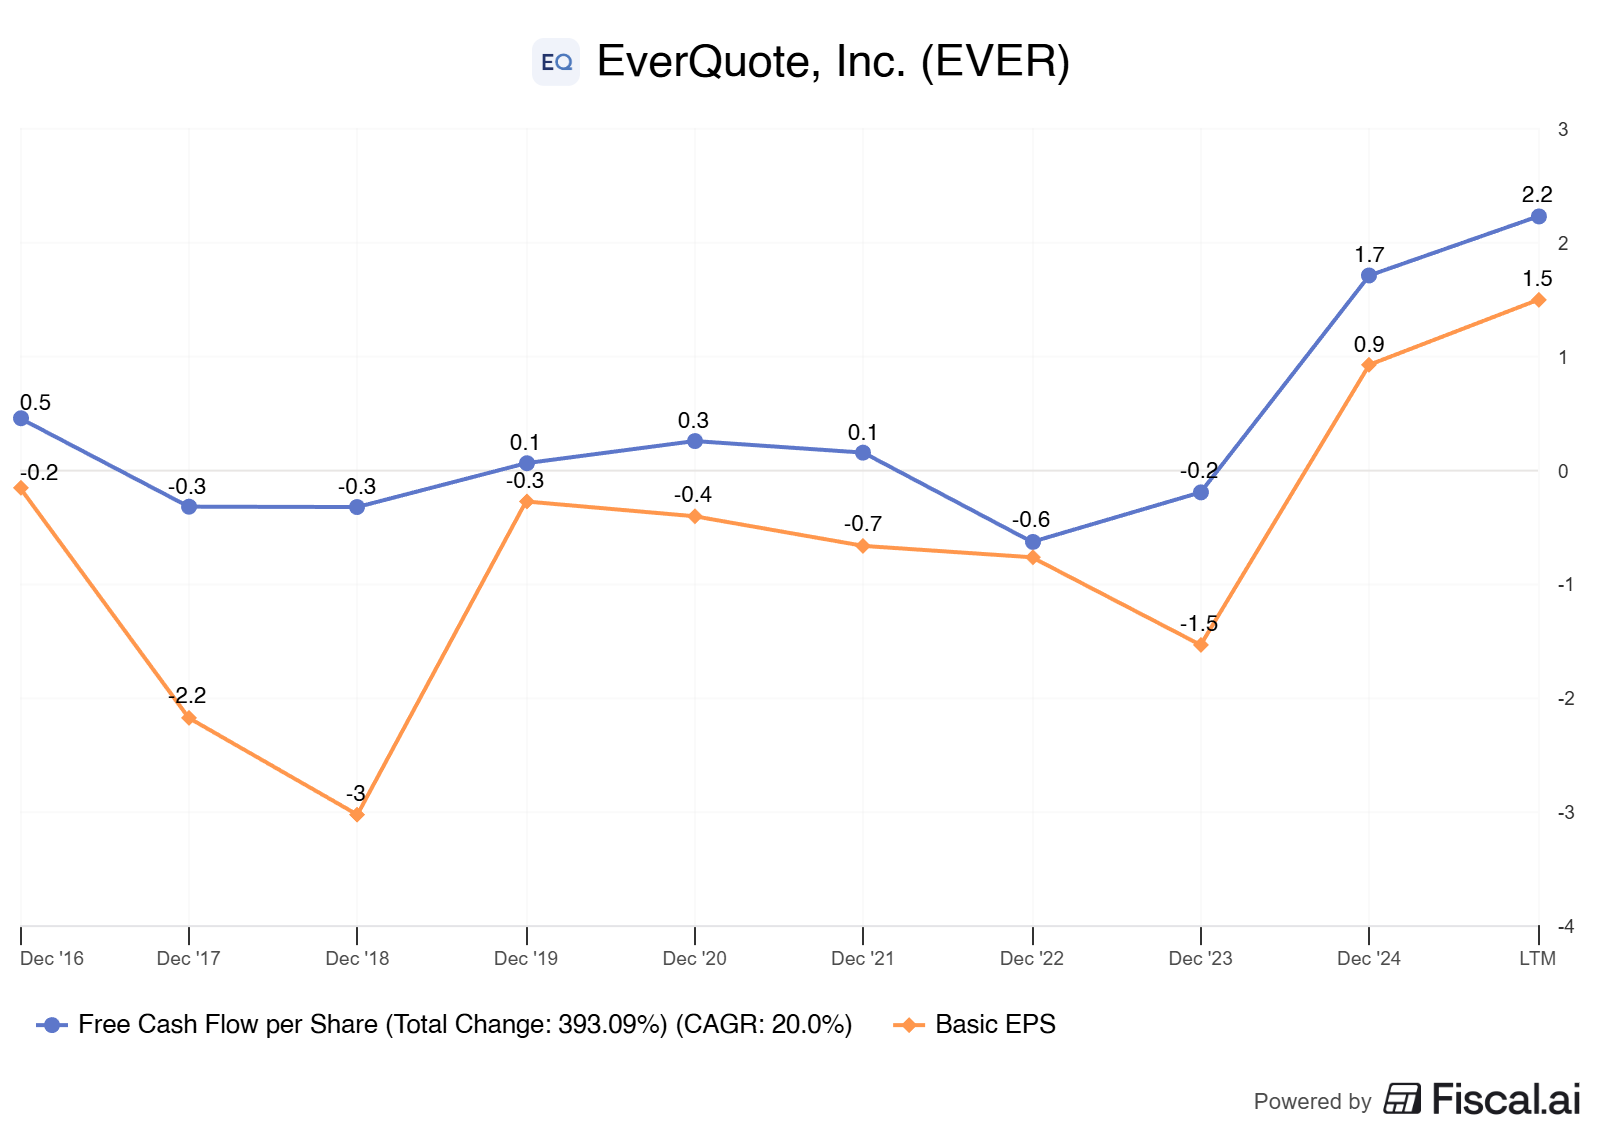
Taking a closer look at the free cash flow per share and earnings per share, we see something similar to what we’ve seen on the return metrics. I weigh more on the free cash flow per share since free cash flow is more complex to make it look more favorable via accounting practices than earnings per share are.
We see that both earnings per share and free cash flow per share are on the right trajectory. It’s even a bit more impressive knowing that the weighted shares outstanding have a CAGR of 5.73%, meaning they’re actively diluting shareholders by issuing more shares. This shows that the growth in both the earnings and free cash flow is contributing significantly more, even outstripping the dilution.
Unlock this mid-cap compounder, and every future one, before the crowd catches on.
Don’t wait. The best mid-caps move fast, once they’re discovered, the upside is gone.
Right now, you can join for only $34.99/month or $340/year.
👉 Go yearly and save $79.88.
If you’re on iOS or Android, subscribe via the website. App stores charge a 30% fee, which makes it more expensive for you. The website saves you real money.
You’re fully protected by a 7-day money-back guarantee — no questions asked, no risk. You’ll either get massive value or your money back. Simple.
