

I need to start with a confession.
I didn’t find this business. Ferg did.
He dropped it in our Fluent Few Discord a few weeks ago, almost as a side comment. I nearly scrolled past it. A medical vest company. Bronchiectasis. Airway clearance. Not exactly the kind of ticker that jumps off the page.
I’m glad I didn’t scroll past it.
I spent the following weeks doing what I always do before I write anything for you: listening to a stack of earnings calls, reading through the 10-Ks line by line, digging into management’s track record, and stress-testing every number I could get my hands on against the primary filings. Somewhere in that process, the “side comment” turned into “I need to write about this.”
Here’s the short version of why.
This is a company that’s:
Grown revenue for 13 to 14 consecutive quarters, straight through a genuine pandemic-era collapse and back out the other side
Tripled its capital efficiency in three years, without taking on a single dollar of debt
Dominating a niche so small that Baxter and Tactile Medical, both far larger competitors, don’t seem to be trying very hard to stop it
And almost nobody outside a small circle of small-cap investors seems to be paying attention.
That doesn’t automatically make it a buy. I want to be upfront about that too. There are real caveats here: a reimbursement model that depends entirely on decisions made in Washington, a balance sheet where nearly half the assets are money owed by insurers, and a stock that’s already re-rated hard enough that the easy money may be behind us, not ahead.
But “not a slam dunk” and “not worth understanding” are two very different things. This one’s worth digging into. So let’s dig in.
Once again, credit where it’s due: thank you, Ferg.
What Will be Discussed?
Corporate Analysis
Business Overview
Revenue Breakdown
Executive Leadership
Management
Management Compensation
Management Value Creation
Competitive and Sustainable Advantages (Economic Moat)
Industry Analysis
Industry Growth Prospects
Competitive Benchmarking
Risk Assessment
Financial Stability
Asset Evaluation
Liability Assessment
Capital Structure
Expense Analysis
Capital Efficiency Review
Profitability Assessment
Profitability, Sustainability, and Margins
Cash Flow Analysis
Growth Projections & Expect Annual Return
Value Proposition
Dividend Analysis
Share Repurchase Programs
Debt Reduction Strategies
Bull & Bear Thesis
Valuation Assessment
Disclaimer: This content is for informational and educational purposes only. Nothing here constitutes investment advice, a solicitation, or a recommendation to buy or sell any security. Always consult a qualified financial advisor before making investment decisions.
I may hold positions in securities mentioned, which creates potential conflicts of interest that readers should factor into how they weigh my analysis. All analysis reflects my personal opinions and may contain errors, omissions, or outdated information — do not rely on it as a complete or accurate account of any company or security. Past performance of any security or strategy discussed is not indicative of future results. Any securities, funds, or assets mentioned are illustrative only and may not be suitable for your individual financial situation, risk tolerance, or investment objectives. You are solely responsible for conducting your own due diligence before acting on anything discussed here.
I make no representations or warranties, express or implied, as to the accuracy, completeness, or timeliness of the information provided. I accept no liability for any loss or damage arising from reliance on this content.
For full terms, see my complete disclaimer here.
Corporate Analysis
Business Overview
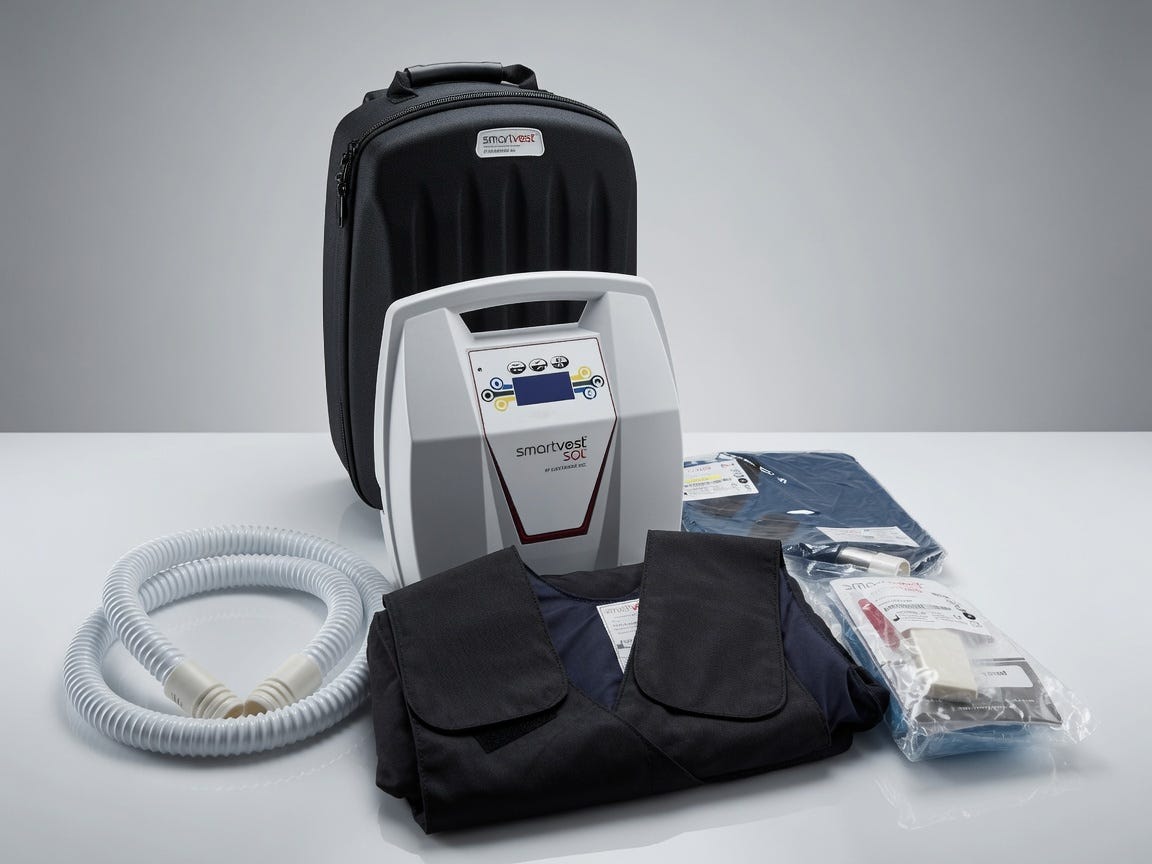
Electromed makes a medical vest called the SmartVest. The product is almost stupidly simple. You put it on, it vibrates fast, and the vibration shakes mucus loose in your lungs so you can cough it out. That’s the entire product.
It’s built for people with chronic lung conditions, mostly bronchiectasis. In this disease, the airways are permanently damaged, and mucus keeps building up. Left alone, that mucus turns into infections, and infections cause more lung damage. Doing the vest daily is a bit like brushing your teeth, except it’s for your lungs instead of your mouth.
The company sells almost entirely in the U.S., direct to patients, at home. A pulmonologist writes the prescription. Electromed handles the insurance paperwork. The vest shows up at the patient’s door. Medicare, Medicaid, and most commercial insurers cover it.
Here’s what makes the business interesting. Electromed says there are roughly 923,000 diagnosed bronchiectasis patients in the U.S. Of those, only 16% are currently using this specific therapy, called high frequency chest wall oscillation. That’s a huge gap. Most of these patients are treated with cheaper, manual airway clearance methods instead, like huffing techniques or breathing exercises. Some aren’t treated at all, because their doctor never prescribed anything or their insurer pushed back.
That gap is Electromed’s whole growth strategy. Educate more doctors. Get more insurers on board. Hire more reps. Slowly convert manual-method patients and untreated patients into vest users.
One product. One country. One disease. A very focused business.
Revenue Breakdown
This part should be fun and quick at the same time since they offer only one product and offer it primarily in the United States.
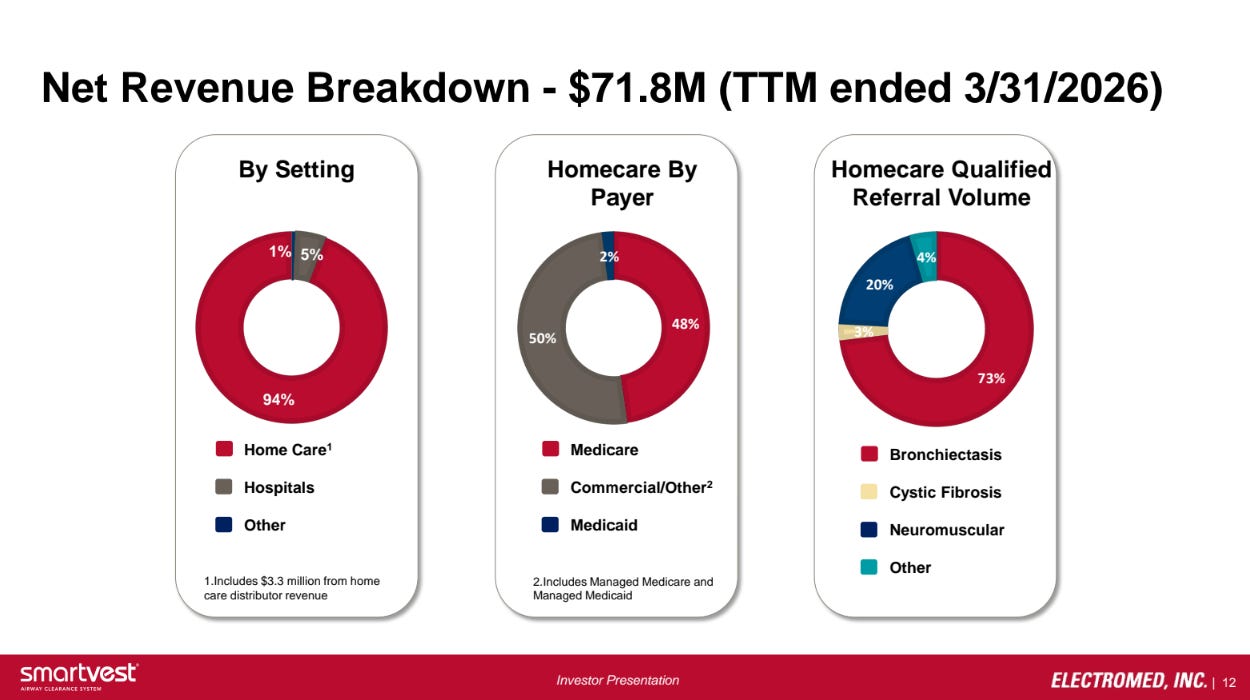
$71.8M in trailing revenue. 94% comes from home care. Someone gets prescribed a SmartVest, it gets shipped to their house, and insurance pays. That’s the whole engine. Hospitals (5%) and other (1%) are basically rounding errors for now.
Within home care, the payer split is almost exactly 50/50 Medicare vs. commercial insurance, with Medicaid a sliver at 2%. And 73% of referrals are bronchiectasis patients, with neuromuscular at 20% and cystic fibrosis/other making up the rest.
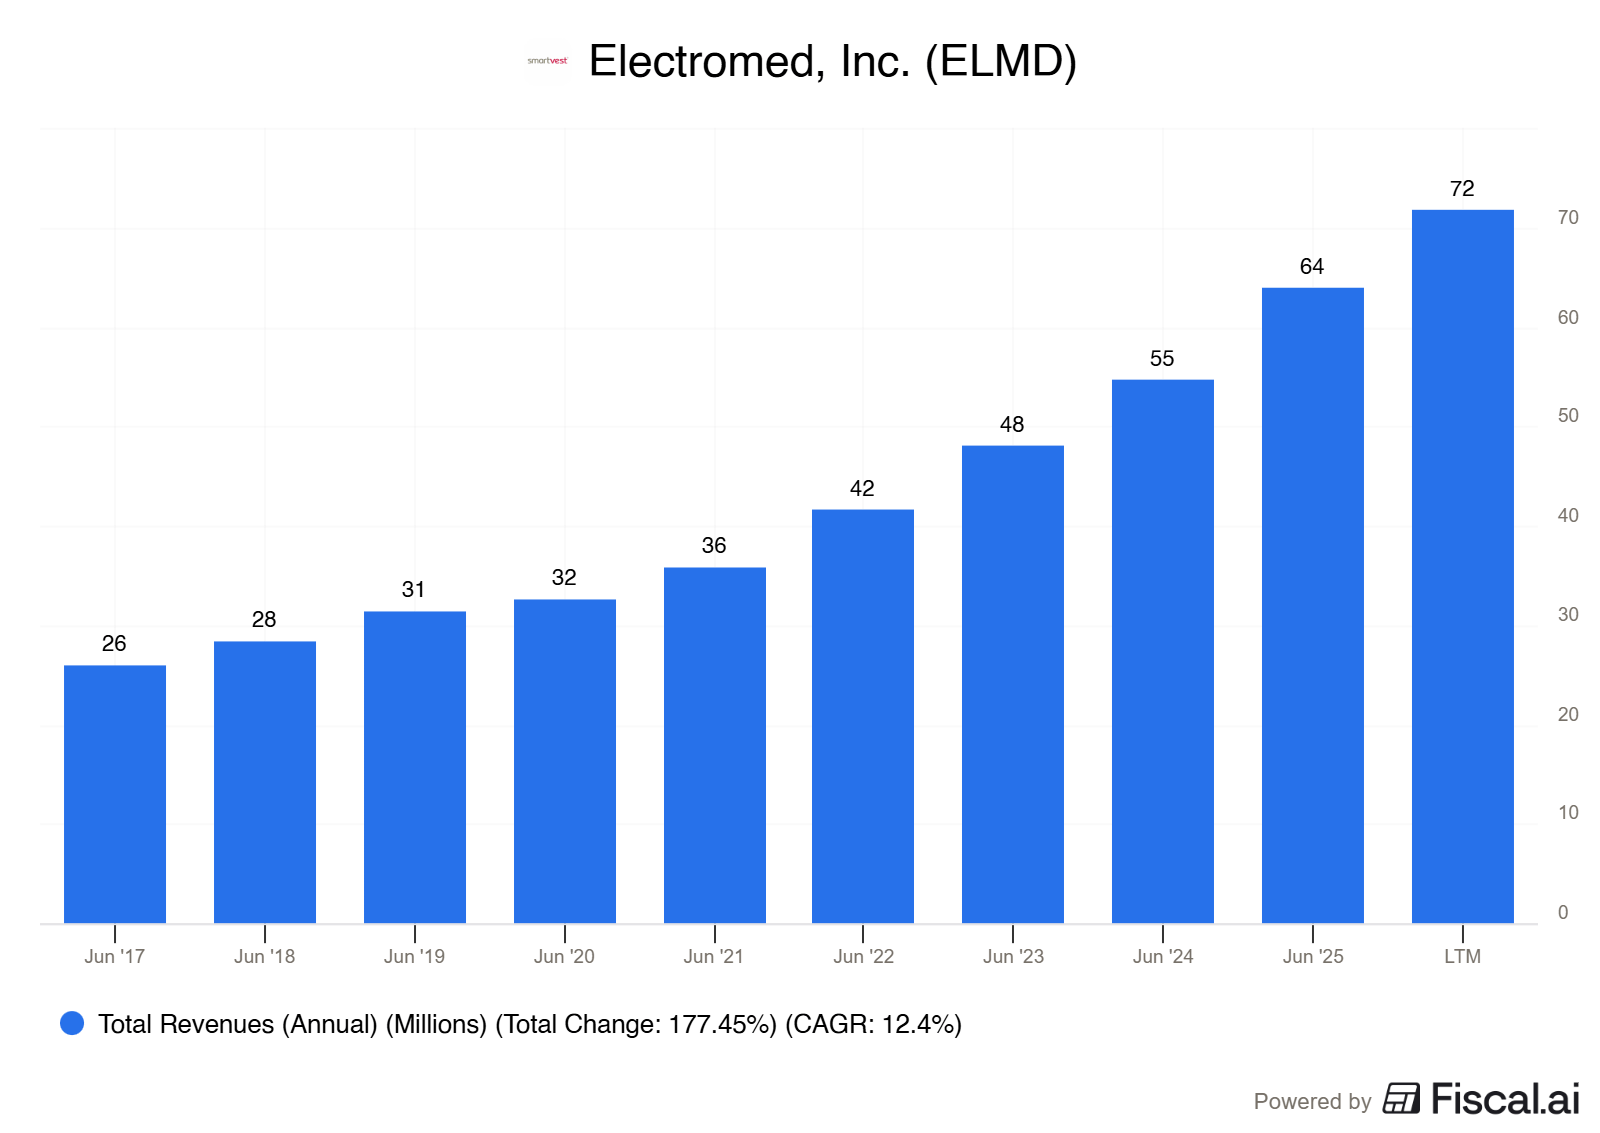
Revenue has compounded at 12.4% annually since 2017, but it’s actually accelerating, the last two years were both 17%+ growth. The model is simple: one product, direct-to-patient, recurring, because bronchiectasis is chronic and irreversible. Patients need this for life once prescribed.
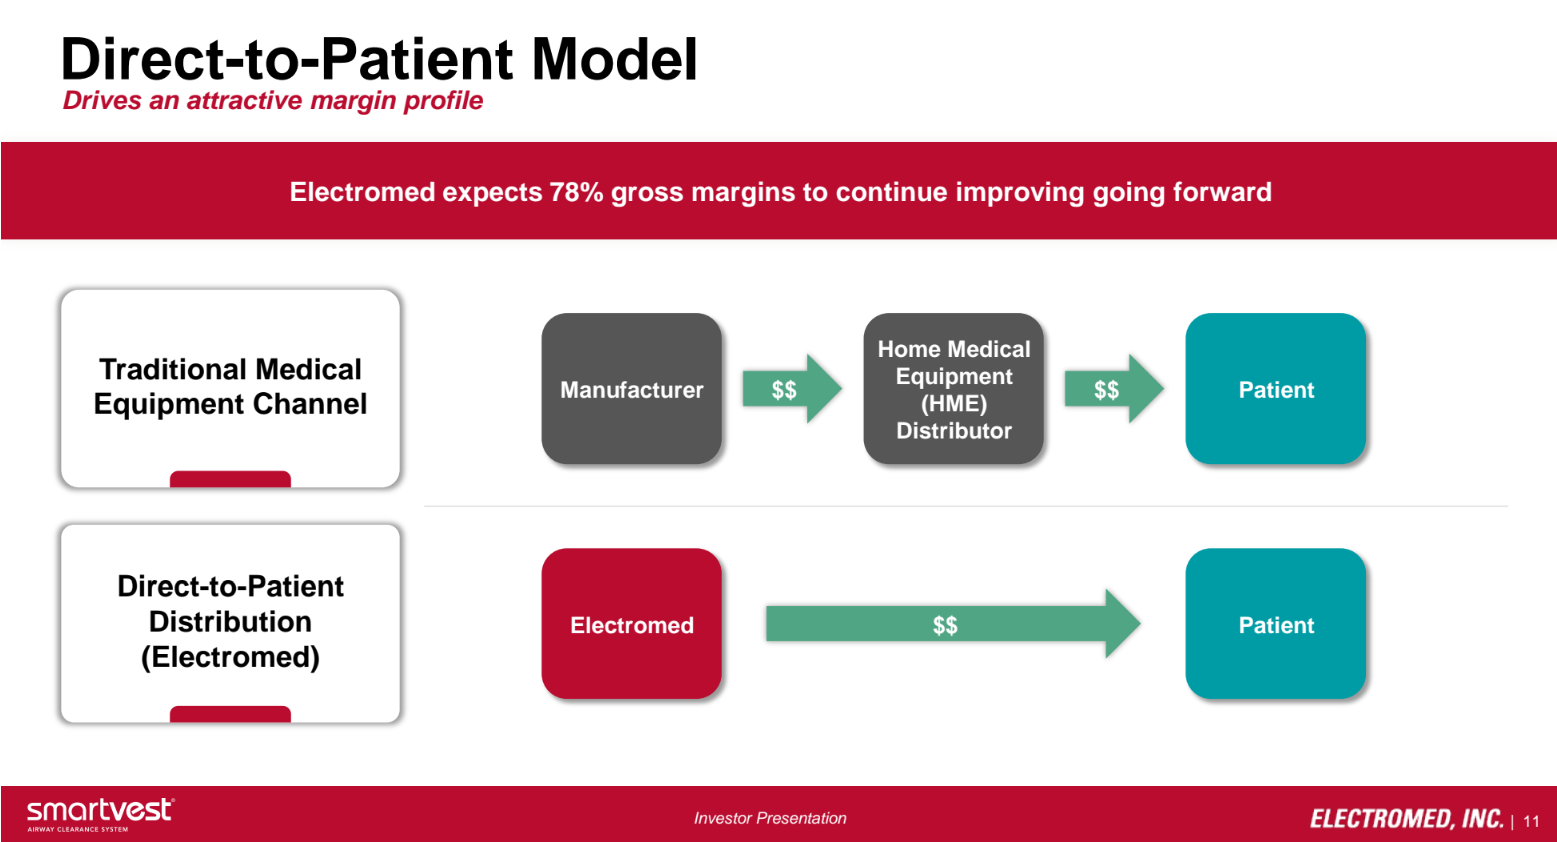
The direct-to-patient model is worth understanding because it's genuinely unusual.
Electromed's sales reps call on pulmonologists, identify patients who qualify, and then Electromed handles everything else itself, including insurance paperwork, approvals, and shipping the vest directly to the patient's door. No middlemen, no distributors taking a cut of the core business. That's why gross margins sit consistently around 78-79%. CEO Jim Cunniff described it on the Q3 FY2026 call as:
"Our productive sales and fulfillment teams, which handle the process from prescription to delivery of the vest to the patient's home" being what "sets us apart in the market."
The 50/50 Medicare/commercial split is worth watching. Medicare is the higher-value payer, CFO Brad Nagel confirmed on the Q2 FY2026 call that:
“We have different sorts of payer targets across commercial versus Medicare, and it worked in our favor this quarter.”
So when Medicare skews higher in a quarter, revenue per rep pops above the target range. It can swing the reported numbers meaningfully without any real change in underlying volume or demand.
94% homecare concentration means this is essentially a single-channel business. The whole model runs through one Medicare billing code, E0483. If CMS reprices or tightens reimbursement criteria on that code, there’s nowhere to hide. That’s not a theoretical risk; it’s happened to other DME companies before.
The 73% concentration of bronchiectasis cuts both ways. The untapped market is genuinely enormous; only 16% of the roughly 923K patients diagnosed with bronchiectasis in the U.S. are currently on airway clearance therapy, leaving around 775K patients unreached. That’s the growth runway. But capturing it depends almost entirely on convincing doctors to prescribe earlier and more often, which is a slow, education-driven process. You can’t manufacture that demand with a product launch or a price cut.
It’s structural. Electromed isn’t fighting a competitor for market share, 84% of their addressable market hasn’t been reached by anyone yet. CEO Jim Cunniff put it plainly on the Q4 FY2025 call:
“One of the opportunities for Electromed is penetrating the large, unrecognized market for bronchiectasis treatment.”
Adding sales reps and educating doctors on a genuinely underdiagnosed disease is the whole strategy. That’s why 14 consecutive quarters of revenue and profit growth happened without any fundamental change to the product. They’re expanding into whitespace, not winning a price war.
Executive Leadership
Management
Jim Cunniff took over as CEO in July 2023, and he’s not some guy learning the ropes on the job. He’s got 30+ years in MedTech, and he’s done basically everything: sales, marketing, manufacturing, finance, M&A.
Quick rundown of where he’s been:
President & CEO of Provista
President & CEO of Leiters Health
Senior VP of Americas at Kinetic Concepts
President of Emerging Markets at Stryker (one of the biggest medical device companies on earth)
Here’s why that background actually matters for Electromed specifically. This isn’t a company that needs someone to invent a new product or reinvent the wheel. It needs someone who can execute: hire good sales reps, get them productive fast, push insurers to cover the vest, get doctors educated on it, and keep the whole fulfillment machine running smoothly. That’s not flashy work, but it’s exactly the kind of work Cunniff has spent his whole career doing.
Now, I want to be straight with you on the numbers here, because I almost got this one wrong myself.
I originally wanted to say “since Cunniff took over, the company’s had 14 straight quarters of growth.” Turns out that’s not quite right. When you map out the actual quarters:
The growth streak actually started about 3 quarters before Cunniff joined, under the previous CEO
Cunniff has personally been at the helm for 11 of those 14 quarters
And in that time, growth has actually sped up: historically, Electromed grew in the low-teens percentage range, and under Cunniff, it’s been running mid-to-high-teens, peaking at 18.4%
Honestly, that’s the better story anyway. He didn’t invent momentum out of nothing. He inherited a business already moving in the right direction and made it move faster. That’s a good sign. It means the growth isn’t just one guy’s magic touch, it’s a real business trend that a strong operator has been able to accelerate.
Whether that’s all Cunniff or the market just finally waking up to the opportunity is probably both. But the match between what this business needed and what he’s spent his career doing is hard to ignore.
Let’s talk about the CFO for a second, Brad Nagel, because his background is one of those “wait, that’s actually perfect” details.
He’s got 15+ years in finance, mostly inside Fortune 500 companies. But here’s the part that matters: he came straight from Medtronic, one of the biggest medical device companies on the planet, where he was Divisional CFO for Global Lung Health and Visualization.
Read that again. Not “generic finance guy.” Divisional CFO for the exact disease category Electromed lives in.
And it gets better. This isn’t even the first time Electromed did this:
Nagel’s predecessor as CFO also came from Medtronic’s Lung Health division
So this looks like a deliberate hiring pattern, not a lucky coincidence
Electromed keeps going back to the same well because they know exactly where the talent that understands this niche actually sits
Why does this matter for a company this size? Electromed is doing around $72M in trailing revenue, still very much in growth mode. That means managing messy insurance reimbursement rules, scaling up a direct sales force, and figuring out how to deploy cash through buybacks, all at the same time. Having a CFO who already speaks the language of lung health reimbursement, and who’s operated inside a much bigger version of this exact business, means he’s not learning the industry on the job. He walked in already knowing where the bodies are buried.
Management Compensation
Let’s talk pay for a second, because comp structure tells you a lot about whether management’s incentives actually line up with yours as a shareholder.
Salaries get set once a year by the Personnel and Compensation Committee, based on individual performance, company results, and what peer companies pay similar execs. For 2025:
Cunniff’s base went from $500,000 to $520,000
Nagel’s base went from $280,300 to $325,000, a solid 16% jump
Worth noting on that CFO raise: the company was explicit that this was a “catch-up to market” adjustment, not a reward for performance. In other words, Nagel had been underpaid relative to peers, and they fixed it.
Now the fun part, the bonus plan. This isn’t some discretionary “we’ll decide at year-end” arrangement. It’s entirely formula-driven, built on two numbers: revenue growth (worth 67% of the formula) and EBT growth (33%). Miss the minimum bar on either one, and the bonus is zero. For 2025, the bars were:
Revenue growth: 6.4% minimum, 12.4% target
EBT growth: 10% minimum, 31% target
Hit the target, you get 100% of your target bonus. Blow past the target, you can earn up to 250% of it. Because Electromed crushed both numbers in 2025, the plan paid out at 156% of target: $405,600 for Cunniff, $202,800 for Nagel.
Then there’s equity. The normal annual grant (restricted stock plus options, handed out every September) is standard retention stuff, vesting a third at a time over three years. Nothing exotic there.
But here’s the part I actually find most interesting: Cunniff’s original hiring package back in July 2023 included 175,000 performance stock units that only vested if the stock actually performed. Half unlocked if the total shareholder return cleared 50%. The other half unlocked if TSR cleared 100%, essentially doubling.
And get this: he already hit both hurdles. The 50% hurdle was cleared by September 2024. The 100% hurdle, the stock doubling, was cleared by December 2024. Both tranches are fully vested now. That’s not a promise of alignment somewhere down the road. That’s proof the alignment mechanism already worked, because the stock had to double for him to collect the full award, and it did.
Put it all together, and you’ve got a three-legged comp structure: a fair-but-not-crazy base salary, a bonus that can swing from zero to 2.5x target purely on hitting real growth and profit numbers, and equity that already forced management to double shareholder returns to get fully paid. That’s a well-built package for a company this size. The one soft spot is that the Committee sets pay using its own judgment rather than an outside compensation consultant, so there’s a bit less independent benchmarking than you’d get at a larger company.
Management Value Creation
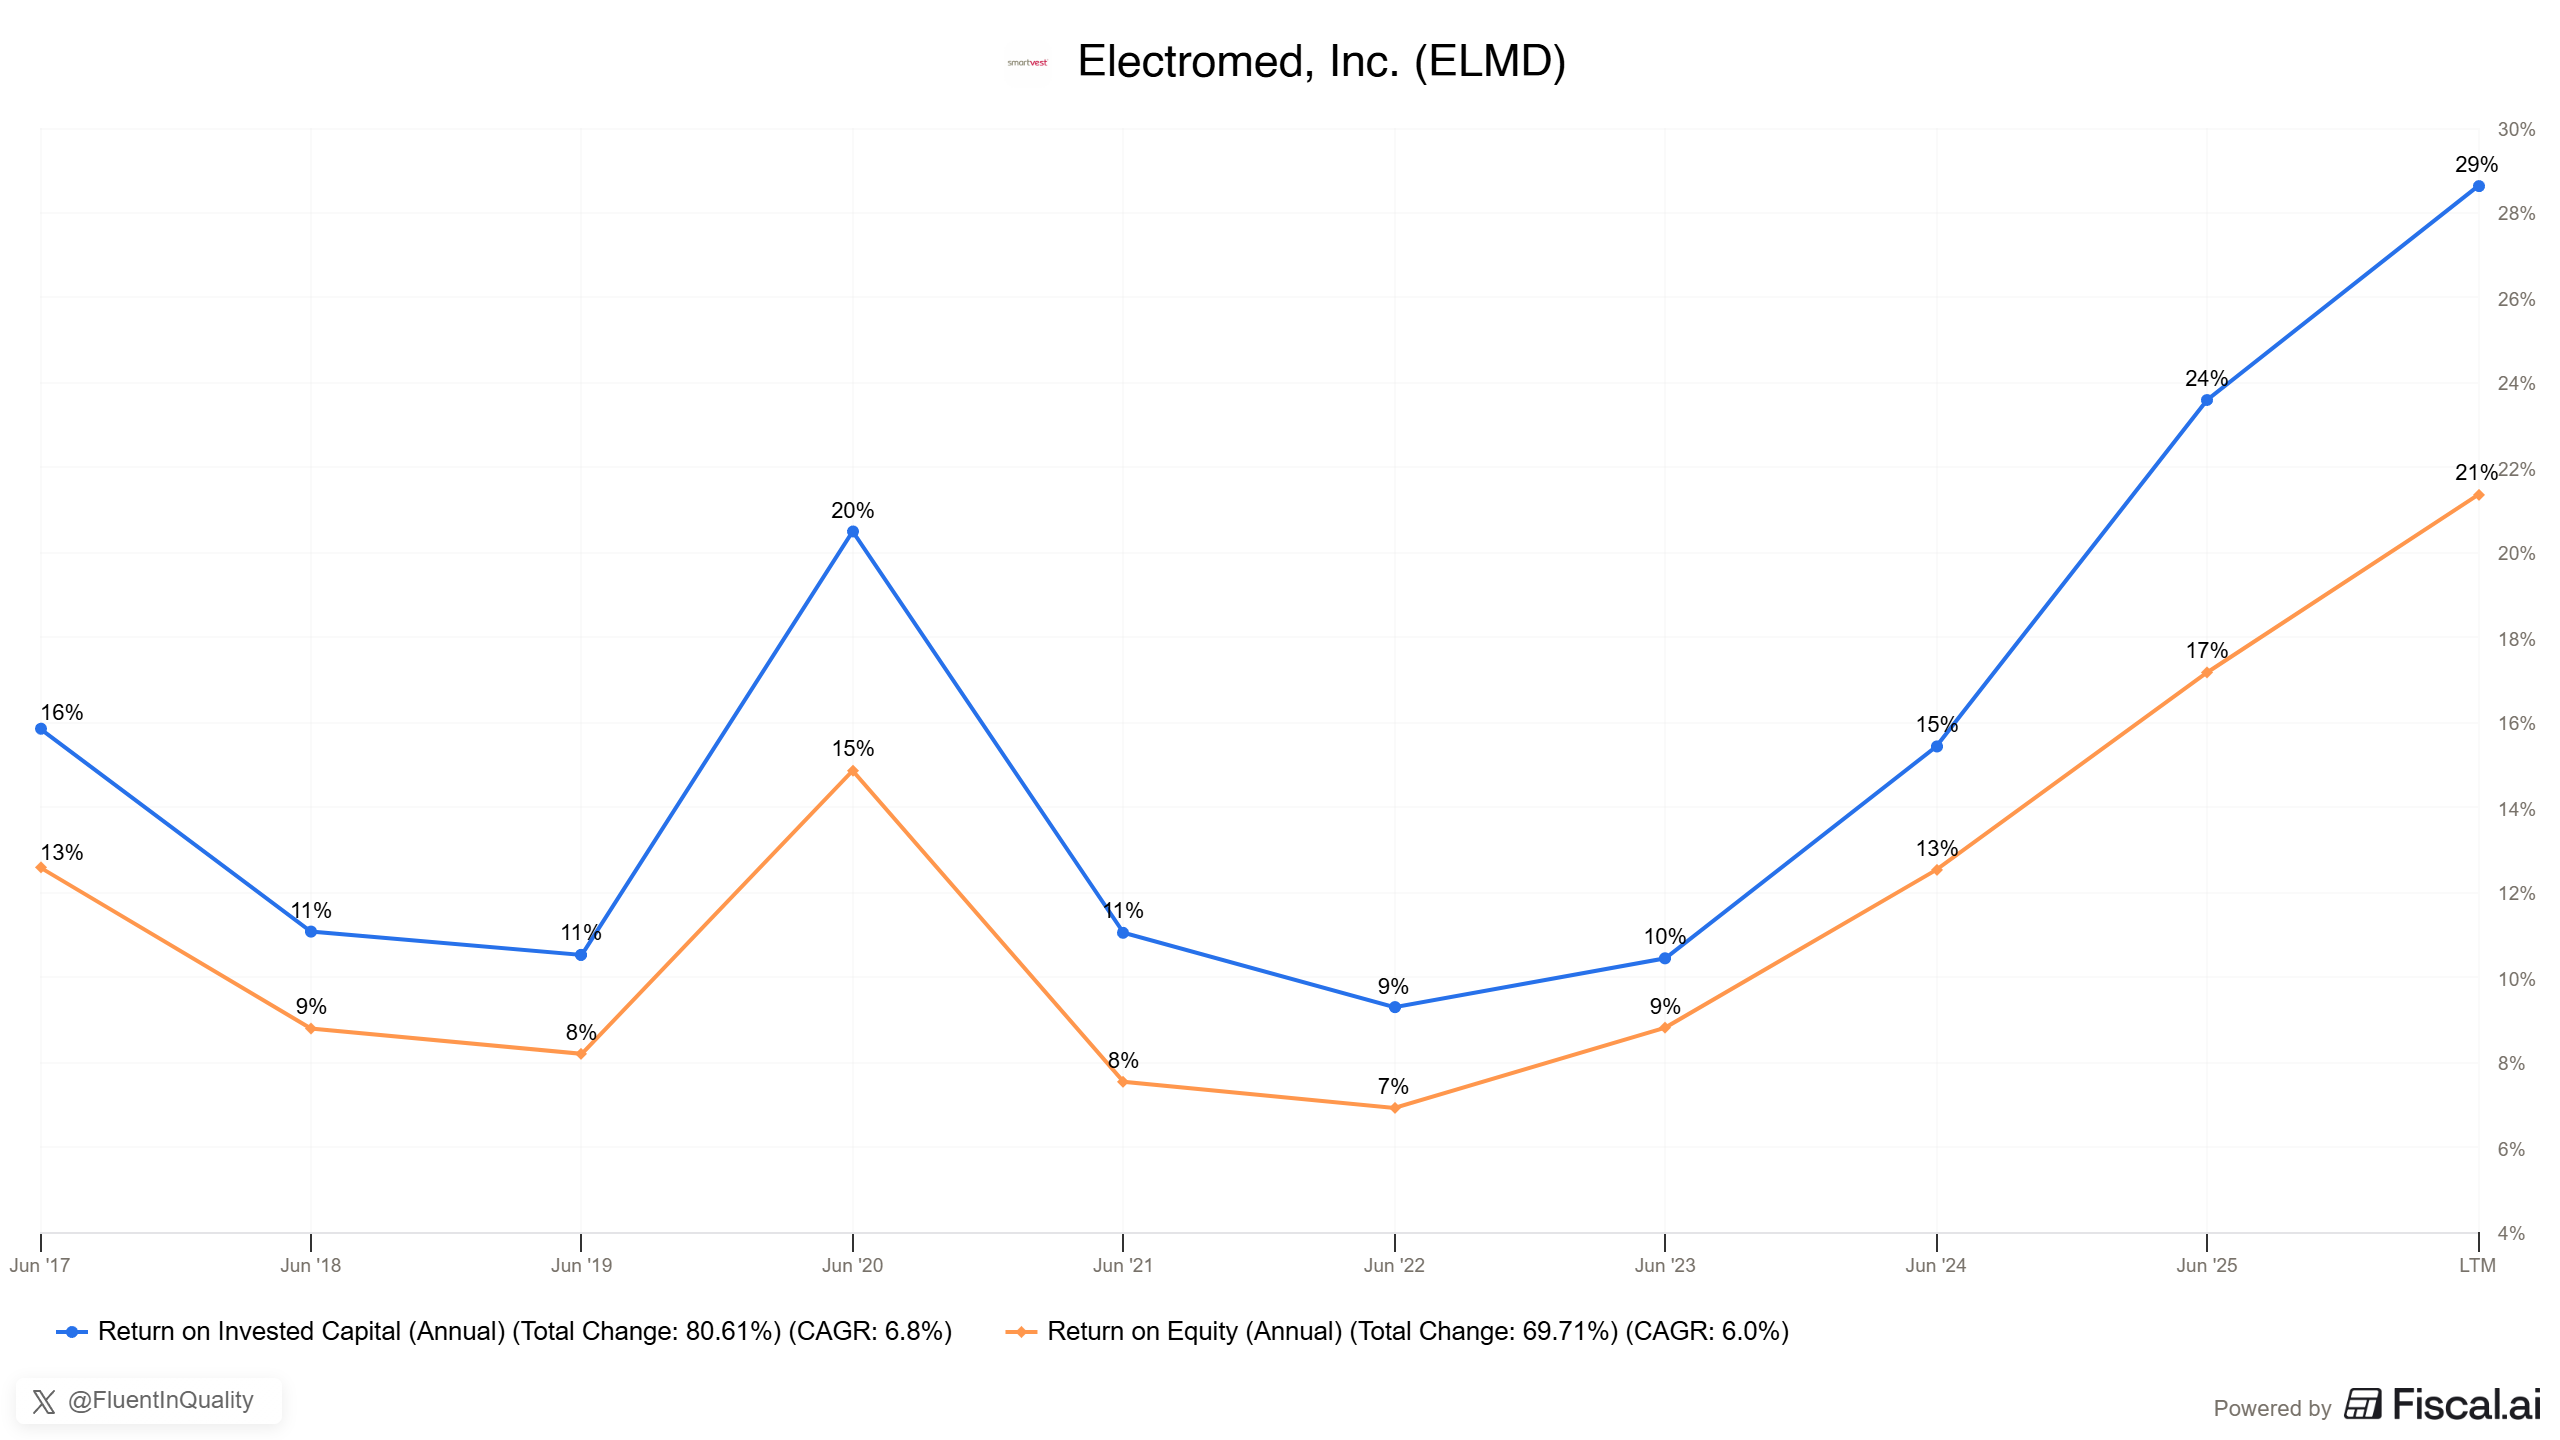
Look at this chart for a second, because it tells a really clean story on its own.
Both ROIC and ROE bottomed out in 2022, at 9% and 7%. Since then, it’s been almost a straight line up:
FY23: 10% / 9%
FY24: 15% / 13%
FY25: 24% / 17%
LTM now: 29% / 21%
That’s roughly a 3x improvement in capital efficiency in three years. And here’s the kicker: Cunniff joined right at the start of 2024, which means basically this entire acceleration phase has happened on his watch. Pair that with the net income trend we already confirmed, $3.17M in FY23, $5.15M in FY24, $7.54M in FY25, and this isn’t some one-time margin bump. It’s compounding operating leverage on a small, efficient asset base.
Now here’s the interesting wrinkle. Normally, you’d expect ROE to run above ROIC because leverage (debt) usually juices the equity return higher. Here it’s flipped. The most likely explanation: Electromed carries no debt and sits on a healthy cash pile. That cash counts toward the equity base (dragging ROE down) but typically gets excluded from the invested capital base used for ROIC. In plain English: the business itself is compounding at 29% returns, but the company is sitting on more cash than it strictly needs to run the business, and that idle cash is what’s dragging the ROE number down below ROIC.
That storyline aligns with what we already know about the buybacks. The board authorized $5 million in repurchases in March 2025, burned through it, then came back with another $10 million authorization in September 2025. That’s management actively working to shrink the equity base and close that ROIC/ROE gap instead of letting cash sit idle. Once you’re generating structural returns north of 25% on the core business, that’s exactly the right capital allocation move.
The rest on this small-cap investment case is for the Fluent Few, the beloved community members.
Join us and get access to this case and all future premium posts.
This business alone could pay your subscription 10x.
For only €25/month or €275/year you can join the community, get premium access, and think and invest along with like-minded investors.
